


EN
MillerKnoll (MLKN) Has Investors Watching, What Is Behind The Fresh Attention?
MillerKnoll (MLKN) shares are in focus after the board confirmed long time insider Jeff Stutz as permanent CEO and added him to the board. This formalizes leadership that investors had been watching in an interim role.
MillerKnoll’s recent leadership decision comes after a mixed stretch for the stock, with a 30-day share price return of 6.18% and a 90-day period where the share price declined 10.90%. The year-to-date share price return sits at 17.69%, and the 1-year total shareholder return is 43.24%, suggesting improving momentum in the shorter term against a tougher multi-year record, including a 5-year total shareholder return that is down 38.80%.
Spot potential leadership and turnaround stories beyond MillerKnoll by scanning our curated list of 19 high quality undiscovered gems across the broader market.MillerKnoll now has a seasoned insider running what many investors already view as a solid furnishings business. The harder call is whether the current share price still leaves enough room for attractive value.
Most Popular Narrative: 35% Undervalued
MillerKnoll’s most followed valuation story pegs fair value at $33 per share against a last close of $21.49. This frames the current price as a sizable discount that hinges on earnings quality and cash conversion staying on track.
Ongoing operational discipline and footprint rationalization, including recent plant closures and restructuring actions that produced several million dollars of year over year operating expense savings, can support structurally higher margins and help MillerKnoll convert more of its existing revenue base into free cash flow and net income.
See why 3 investors see MillerKnoll as 35% undervalued.
Result: Fair Value of $33 (UNDERVALUED)
Still, tariff related earnings headwinds and softer North America Contract orders could pressure MillerKnoll if pricing actions and cost cuts fail to offset weaker demand.
Find out about the key risks to this MillerKnoll narrative.
Another View: How MillerKnoll’s P/E Complicates The Story
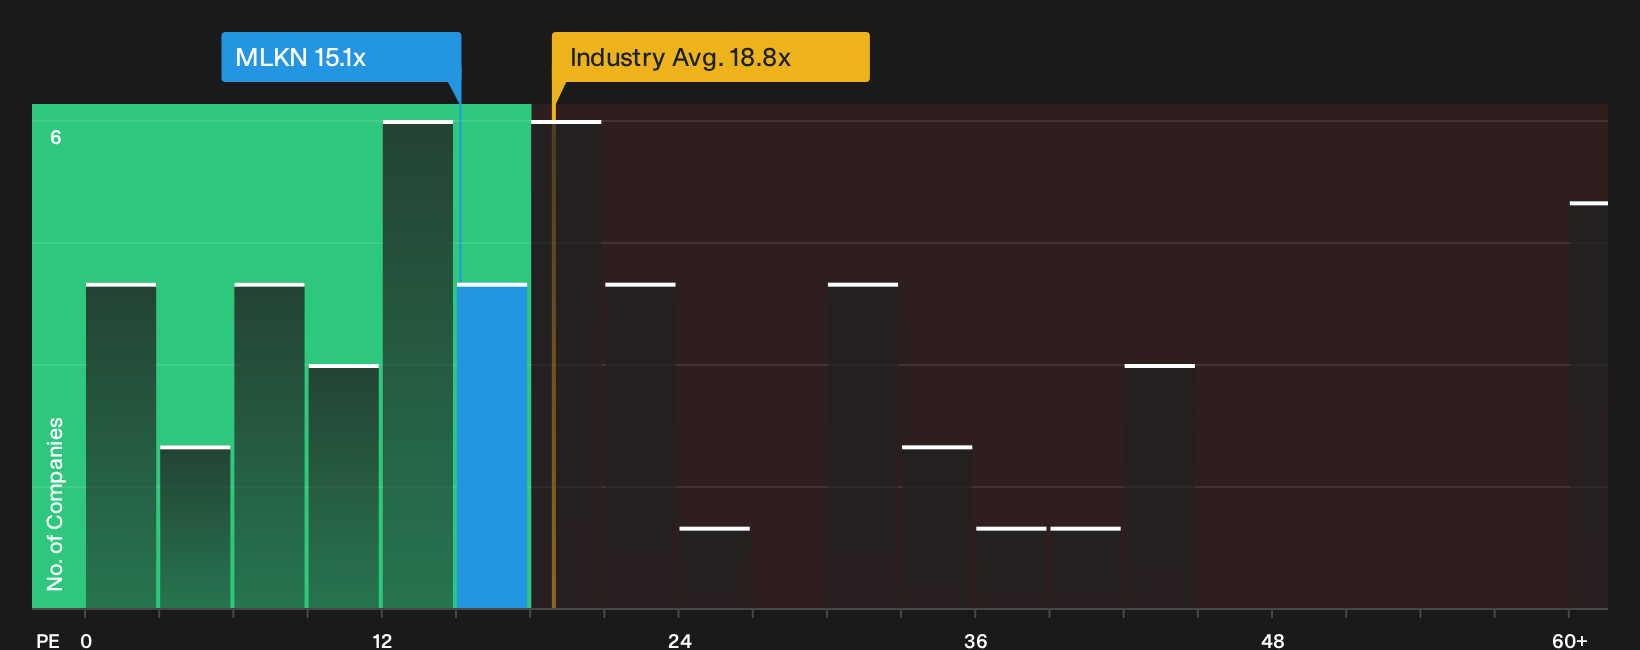
The fair value narrative presents MillerKnoll as materially undervalued, yet the straightforward P/E picture is less generous. At 15.1x earnings, the stock trades above a 13.6x peer average but below the US Commercial Services group at 18.8x and under a 19.9x fair ratio.
That combination suggests a business that appears more expensive than close comparables but cheaper than the broader industry, with potential for the valuation to move toward the fair ratio or converge toward peers. The key question for you is which outcome seems more plausible for MillerKnoll over time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment runs through MillerKnoll, so use that tension as a prompt to move quickly, review the full dataset, and decide what matters most to you after weighing 3 key rewards and 2 important warning signs.
Looking for more MillerKnoll style investment ideas?
If you stop with MillerKnoll, you risk missing other setups that fit your approach. Use the screeners below to widen your opportunity set intelligently.
- Target potential mispricings by scanning a focused pool of 33 high quality undervalued stocks that pair quality fundamentals with compressed multiples.
- Strengthen your income stream by zeroing in on 5 dividend fortresses that aim to combine high yields with resilient cash flows.
- Control downside risk by filtering for 29 resilient stocks with low risk scores that show steadier return profiles and more conservative balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com