


EN
Does Earnings Upgrade Change The Bull Case For Murphy Oil Stock (MUR)?
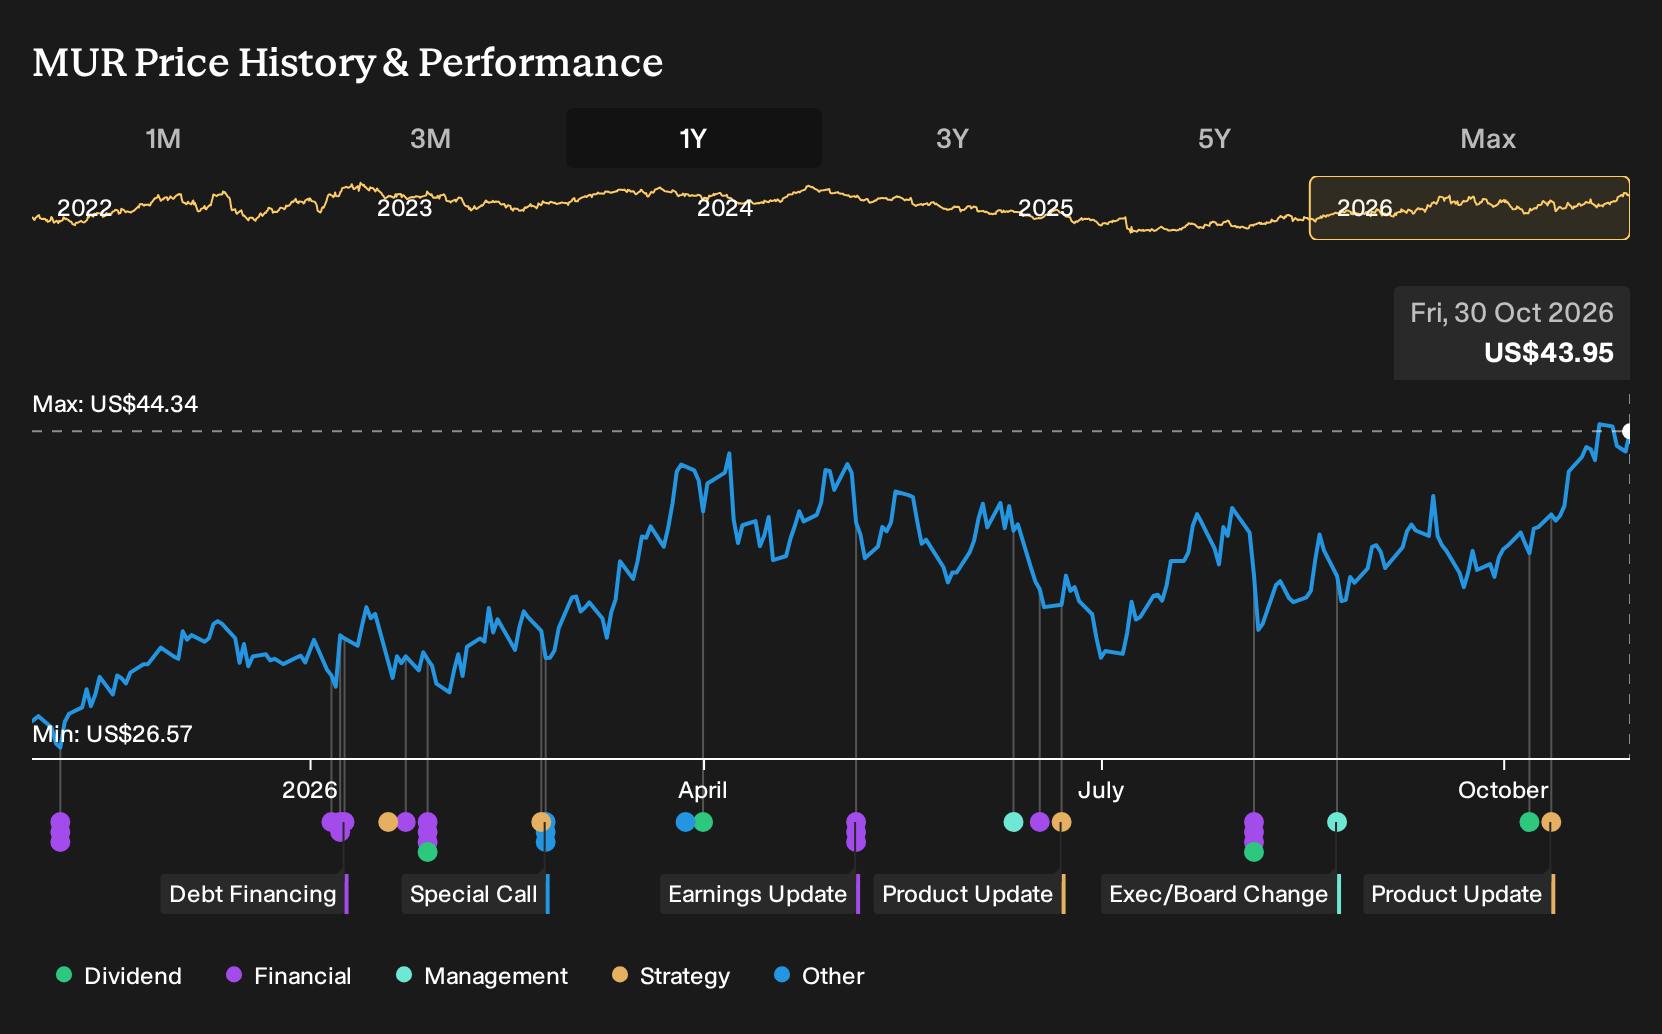
- Murphy Oil recently saw analysts lift earnings forecasts for the current and next year, reflecting higher expected profitability from its producing and development assets across offshore fields and the Eagle Ford.
- The sharper focus now falls on execution, since larger offshore and Eagle Ford programs must deliver volumes and cost control to support those upgraded profit expectations.
- We will look at how Murphy Oil's investment narrative is reshaped by upgraded earnings expectations tied to its offshore and Eagle Ford programs.
Scan other oil and gas producers seeing fresh earnings momentum and valuation tension by reviewing the hand picked 33 high quality undervalued stocks, which may echo elements of the Murphy Oil story.
Murphy Oil Investment Narrative Recap
To own Murphy Oil, you need to believe its heavier 2026 capital program in Bubale, Eagle Ford and Vietnam can translate into sustainable production and solid project returns without stretching the balance sheet. The recent earnings upgrades simply raise the bar on that execution. The core near term catalyst remains converting that higher spend into dependable barrels and cash flow.
The biggest risk sits on the same fault line. If Bubale appraisal wells are expensive yet underdeliver, or if Vietnamese subsurface surprises continue after the Hai Su Vang revision, cash generation could lag the higher capital bill. In that scenario, earnings pressure and tougher capital allocation trade offs become more likely.
The fresh focus on Murphy Oil following the earnings upgrades ties directly back to its enlarged 2026 spending plan. Management lifted the capital expenditure midpoint to about US$1.55b, with sizeable extra dollars pointed at Bubale appraisal and the Eagle Ford ramp. The news event sharpens attention on whether those specific projects can carry the heavier load now baked into expectations.
For you, that means watching a few operational markers closely. Bubale costs and well results need to show that US$140 million type wells can still earn acceptable returns. Eagle Ford volumes have to justify the added rig and budget. Any repeat of the Hai Su Vang resource downgrade in Vietnam would work against the current narrative that Murphy Oil can grow into its higher spending profile.
Murphy Oil's latest analyst framework points to revenues of about US$3.3b and earnings of roughly US$679.5 million by 2029, based on an assumed 3.6% yearly revenue growth rate and an increase in profit from US$295.2 million today. This implies earnings would need to climb by about US$384 million over that period.
Uncover why Murphy Oil's fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate angle on Murphy Oil puts the Eagle Ford ramp front and center as a risk rather than a growth engine. The most cautious analysts were penciling in 3.1% annual revenue growth and about US$504.7 million of 2029 earnings before this news. That is well below the US$679.5 million consensus path, so be open to how views may shift as fresh data arrives.
Explore 2 other Murphy Oil fair value estimates, including one that suggests it could be worth just $41.93.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis.
- A great starting point for your Murphy Oil research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Murphy Oil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Murphy Oil's overall financial health at a glance.
Looking For More Investment Ideas Beyond Murphy Oil?
Once you have a view on Murphy Oil, it can help to widen the lens and compare it with other companies that share similar qualities or offer different risk and income profiles.
- If you want to hunt for potential bargains with quality fundamentals, scan the 33 high quality undervalued stocks that currently match those criteria.
- For investors who care most about income strength and payout, review a focused set of 5 dividend fortresses that may suit a yield oriented approach.
- When capital preservation matters as much as upside, start with a curated 29 resilient stocks with low risk scores that clears Simply Wall St's lower risk thresholds.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com