


EN
Is DT Midstream (DTM) Fully Valued After Lifting EBITDA And Cash Flow Guidance?
DT Midstream (DTM) just paired a fresh set of third quarter earnings with a higher full year EBITDA and distributable cash flow outlook, while also reining in growth spending and flagging near term operational headwinds.
DT Midstream’s stock slipped about 2.1% on the day of the results, yet the 1 month share price return of 2.76% and year to date share price gain of 2.77% suggest momentum has been edging back after a softer 90 day spell. The latest earnings upgrade and reaffirmed dividend sit against a stronger backdrop for long term investors, with 1 year total shareholder return of 16.61% and a 5 year total shareholder return above 200% indicating that the market has already priced in a significant portion of the company’s story while still responding to near term operational risks.
Scan beyond DT Midstream and review other midstream and infrastructure plays that combine cash generation with capacity growth using our curated 41 power grid technology and infrastructure stocks
DT Midstream now trades just below analyst targets while one intrinsic value framework suggests the stock already runs rich. Which signal does the recent post earnings wobble suggest investors should trust as a guide on fair value?
Most Popular Narrative: 17% Undervalued
DT Midstream’s most followed valuation story pegs fair value at about $149.73, comfortably above the last close of $124.34. This helps put the recent pullback in context as investors weigh project execution against a higher implied bar.
Surging U.S. power demand, including large data center and utility-scale load growth in the Midwest and Northeast, is now translating into oversubscribed open seasons on Midwestern and Vector and over 0.5 Bcf/d of new NEXUS interconnect capacity plus a planned 265 MMcf/d lateral to a 900 MW plant, which can support higher long-haul throughput, rate base and earnings tied to power and data center gas demand.
See why 5 investors see DT Midstream as 17% undervalued.
Result: Fair Value of $149.73 (UNDERVALUED)
Still, DT Midstream’s story can change quickly if large expansion projects face permitting delays or if regional gas demand softens and leaves new capacity underused.
Find out about the key risks to this DT Midstream narrative.
Another View: DT Midstream Looks Expensive On Earnings
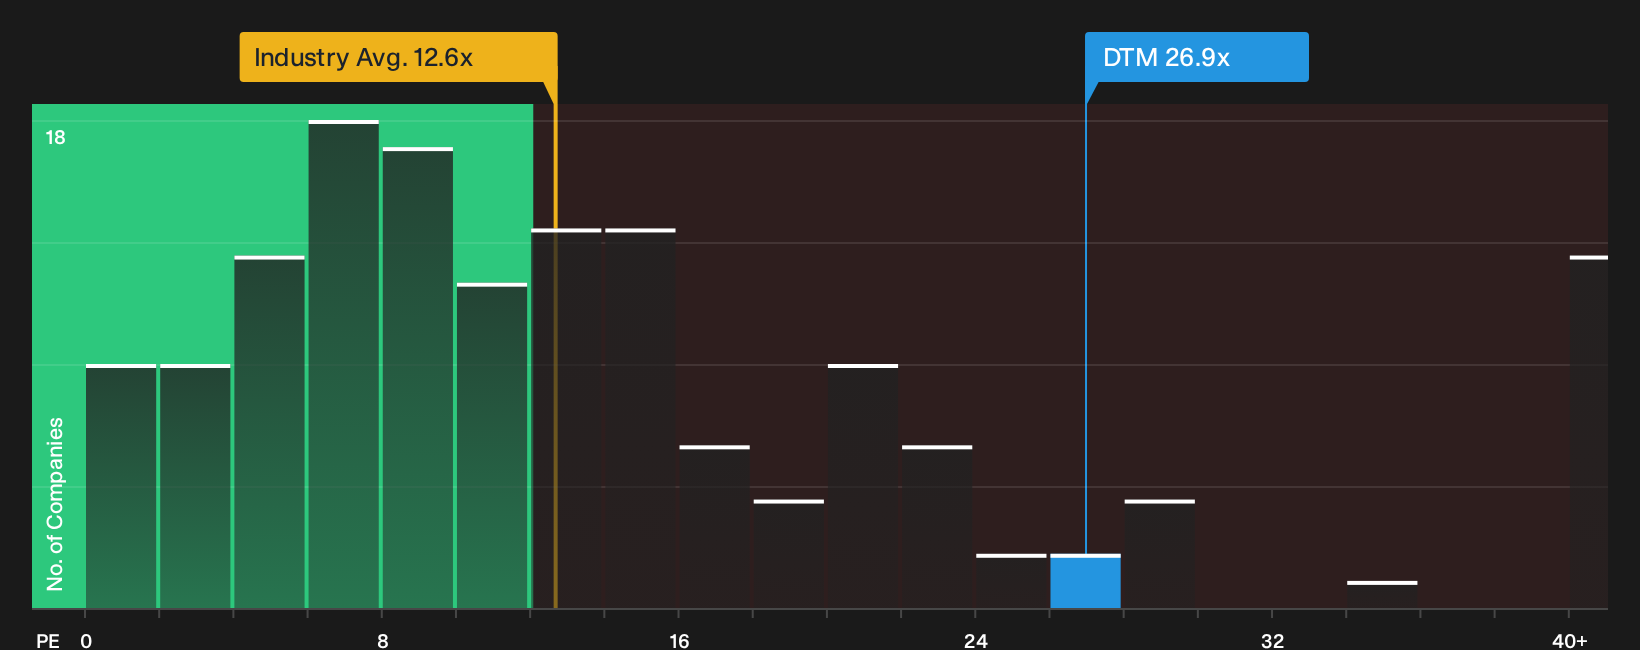
DT Midstream might screen as 17% undervalued on the latest fair value narrative, but the plain P/E math tells a different story. At 26.9x earnings versus a peer average of 15.8x and a fair ratio of 18.5x, investors are paying a hefty premium for the current trajectory. How comfortable are you with that gap if expectations cool?
Before leaning on the earnings based story alone, it is worth stress testing the numbers and seeing what the valuation gap implies for downside risk if sentiment resets, especially compared with peers that trade closer to their fair ratio. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on DT Midstream’s value story can feel messy, so treat this as your cue to move quickly and review the numbers yourself with 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond DT Midstream?
If DT Midstream has sharpened your focus on quality and valuation, do not stop here. Use fresh stock shortlists to test your thesis, spot mispriced stories, and pressure test your portfolio before the next move catches you off guard.
- Target resilience by scanning a 29 resilient stocks with low risk scores that can help you reduce portfolio swings without walking away from equity opportunities.
- Upgrade quality by working through a list of solid balance sheet and fundamentals (24 results) that highlights businesses with healthier debt profiles and sturdier fundamentals.
- Get ahead of the crowd by reviewing a 19 high quality undiscovered gems before capital flows into the same set of familiar tickers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com