


EN
Is GXO Logistics (GXO) Undervalued As Medini Expansion And Robot Rollout Gain Attention?
GXO Logistics (GXO) is back on investors’ radar after two fresh announcements: a new logistics hub in Medini, Malaysia, and an expanded humanoid robotics rollout with Agility Robotics across US facilities.
Recent trading reflects that story catching up with the market. GXO Logistics has seen a 7.97% 1 month share price return, yet its year to date share price return is still down 7.42% and the 1 year total shareholder return is down 10.57%. This points to short term momentum building off a weaker longer term base as investors reassess growth potential and risk after the Medini expansion and humanoid robotics news.
Scan how GXO Logistics compares with other automation driven logistics players by reviewing our curated list of 95 robotics and automation stocks in the sector.
So is this sharp rebound in GXO Logistics a clear signal of improving business economics around Medini and humanoid robotics, or mainly a shift in sentiment that still needs to work through the current valuation?
Most Popular Narrative: 14% Overvalued
According to the most widely followed narrative for GXO Logistics, the fair value sits at $44.27 compared to the recent $50.27 close. This suggests the stock is currently pricing in a significant amount of optimism.
GXO has substantial institutional support, but broad, high-conviction recent accumulation has not been established.
The institutions are present. The insiders are not charging through the front door with checkbooks.
See why 1 investors see GXO Logistics as 14% overvalued.
Result: Fair Value of $44.27 (OVERVALUED)
Still, weaker multi year shareholder returns and unproven robotics economics leave room for disappointing cash conversion to change the GXO Logistics story quickly.
Find out about the key risks to this GXO Logistics narrative.
Another View: What Our DCF Says About GXO Logistics
The earlier fair value of $44.27 suggested GXO Logistics was 14% overvalued. A different lens tells a very different story. The SWS DCF model puts fair value at $101.08 per share, which is roughly double the recent $50.27 price and frames the stock as significantly undervalued.
That gap presents a trade-off for you as an investor. The P/E based work highlights rich earnings multiples today. The cash flow approach relies on forecasts for 41.7% earnings growth each year and stronger conversion. The key consideration is whether future cash generation ends up closer to the cautious earnings multiples or to the optimistic DCF path.
To see how this cash flow driven view is built from the ground up, Look into how the SWS DCF model arrives at its fair value..
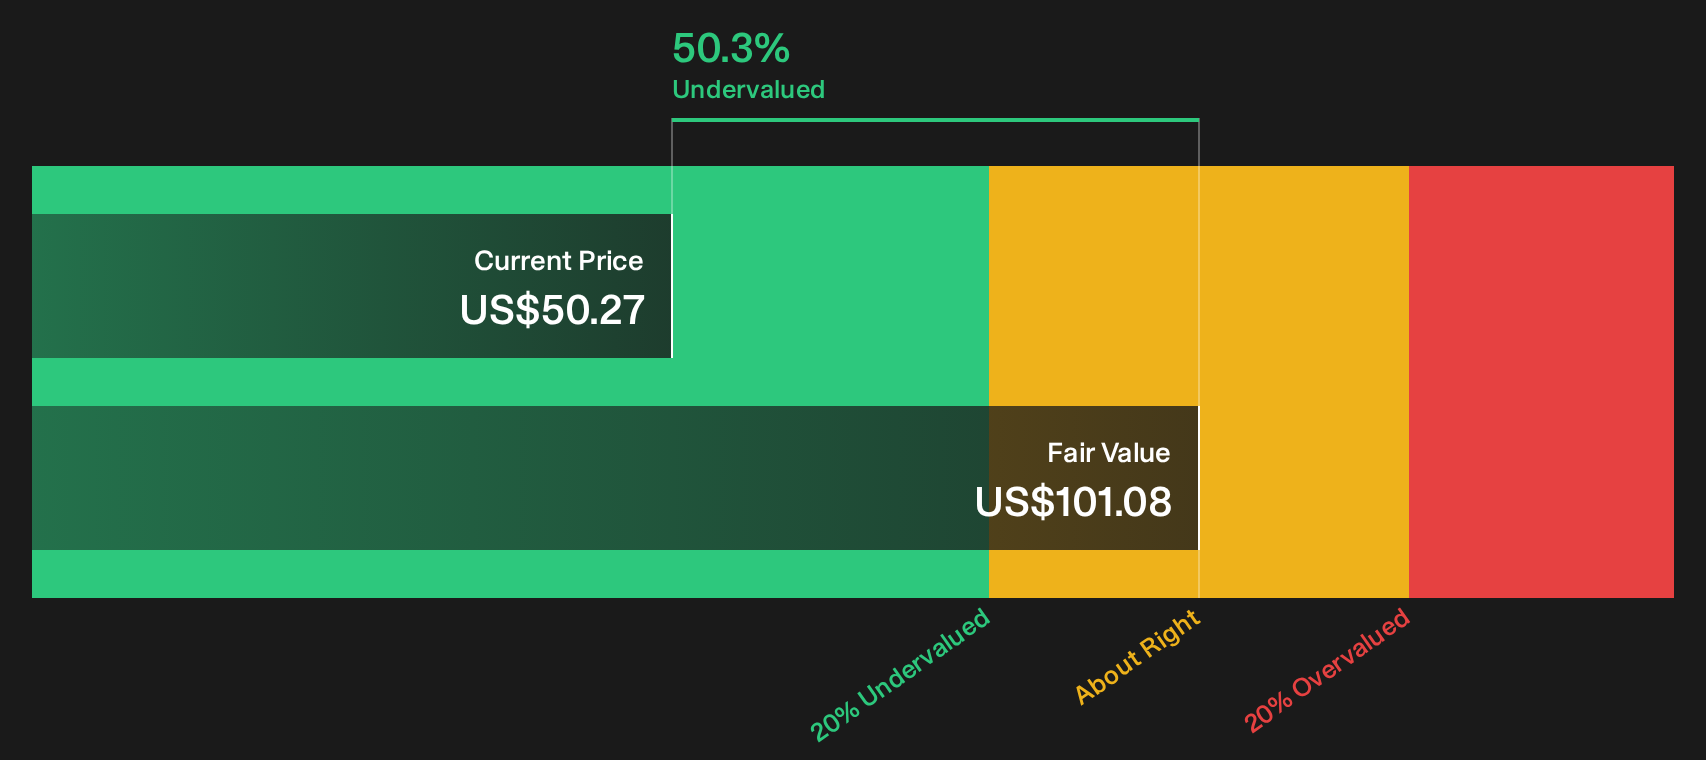
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out GXO Logistics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around GXO Logistics leave you on the fence, move quickly to study the full picture yourself and weigh both sides using the 4 key rewards and 2 important warning signs.
Looking for more GXO Logistics sized investment ideas?
If GXO Logistics has your attention, do not stop here. Broaden your watchlist now so you are not relying on a single story.
- Target resilient compounding potential by focusing on businesses with strong finances and earnings quality using our list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality where fundamentals and price still look out of sync by scanning our 19 high quality undiscovered gems.
- Prioritise sleep at night holdings that aim to limit downside shocks with the support of our 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com