


EN
Is AI Booking Push Altering The Investment Case For Yelp (YELP)?
- Yelp's 2026 Fall Product Release introduced more than 30 AI driven features, including upgrades to Yelp Assistant, new booking tools, Check for Me, My Lists and Smart Lead Reply, plus deeper integrations with OpenTable, ServiceTitan, Housecall Pro, Jobber, Workiz and Shopify.
- The rollout concentrates on higher quality leads and automated responses for local pros, which may influence how effectively Yelp converts engagement into paying advertisers, subscription tools and measurable ad outcomes across its platform.
- We will now examine how Yelp's investment narrative could be affected by AI centered tools such as the upgraded Yelp Assistant.
Scan how Yelp’s AI push compares with other platforms automating local services and bookings by reviewing the 54 AI infrastructure stocks that could be shaping the next wave of real world AI adoption.
Yelp Investment Narrative Recap
To own Yelp, an investor needs to believe its AI heavy product push can keep users engaged and help offset pressure in the core advertising categories where net revenue recently grew 1% with Restaurant, Retail and Other ads down 10% and Services ads flat. The near term swing factor is whether these tools can support more valuable leads without eroding margins.
The main risk is that AI product, Hatch and marketing spend grows faster than the extra revenue, which could limit EBITDA and net margin expansion while ad demand is soft. Legal and regulatory actions around content labels and hiring practices also hang over earnings quality and cash flow.
Among the latest features, the upgraded Yelp Assistant with OpenTable integration and direct bookings sits closest to the current catalysts. It touches both sides of the marketplace. More convenient discovery and booking can support engagement, which is a core input into lead volumes for local advertisers and subscription tools.
The same Assistant also feeds into Yelp's AI search and data story, which analysts already view as a higher margin stream alongside content licensing to partners like OpenAI and Apple Maps. Execution risk is real. If usage of Assistant, Check for Me and Smart Lead Reply disappoints, the expected offset to slow ad categories and the path to better profitability becomes harder to sustain.
Yelp's current analyst script points to forecast revenues of US$1.6b and earnings of US$157.9 million by 2029, based on revenue growth of 2.1% per year and an earnings increase of about US$31.4 million from US$126.5 million today.
Uncover how Yelp's fair value indicates a 32% potential upside to its current price before sentiment closes that gap.
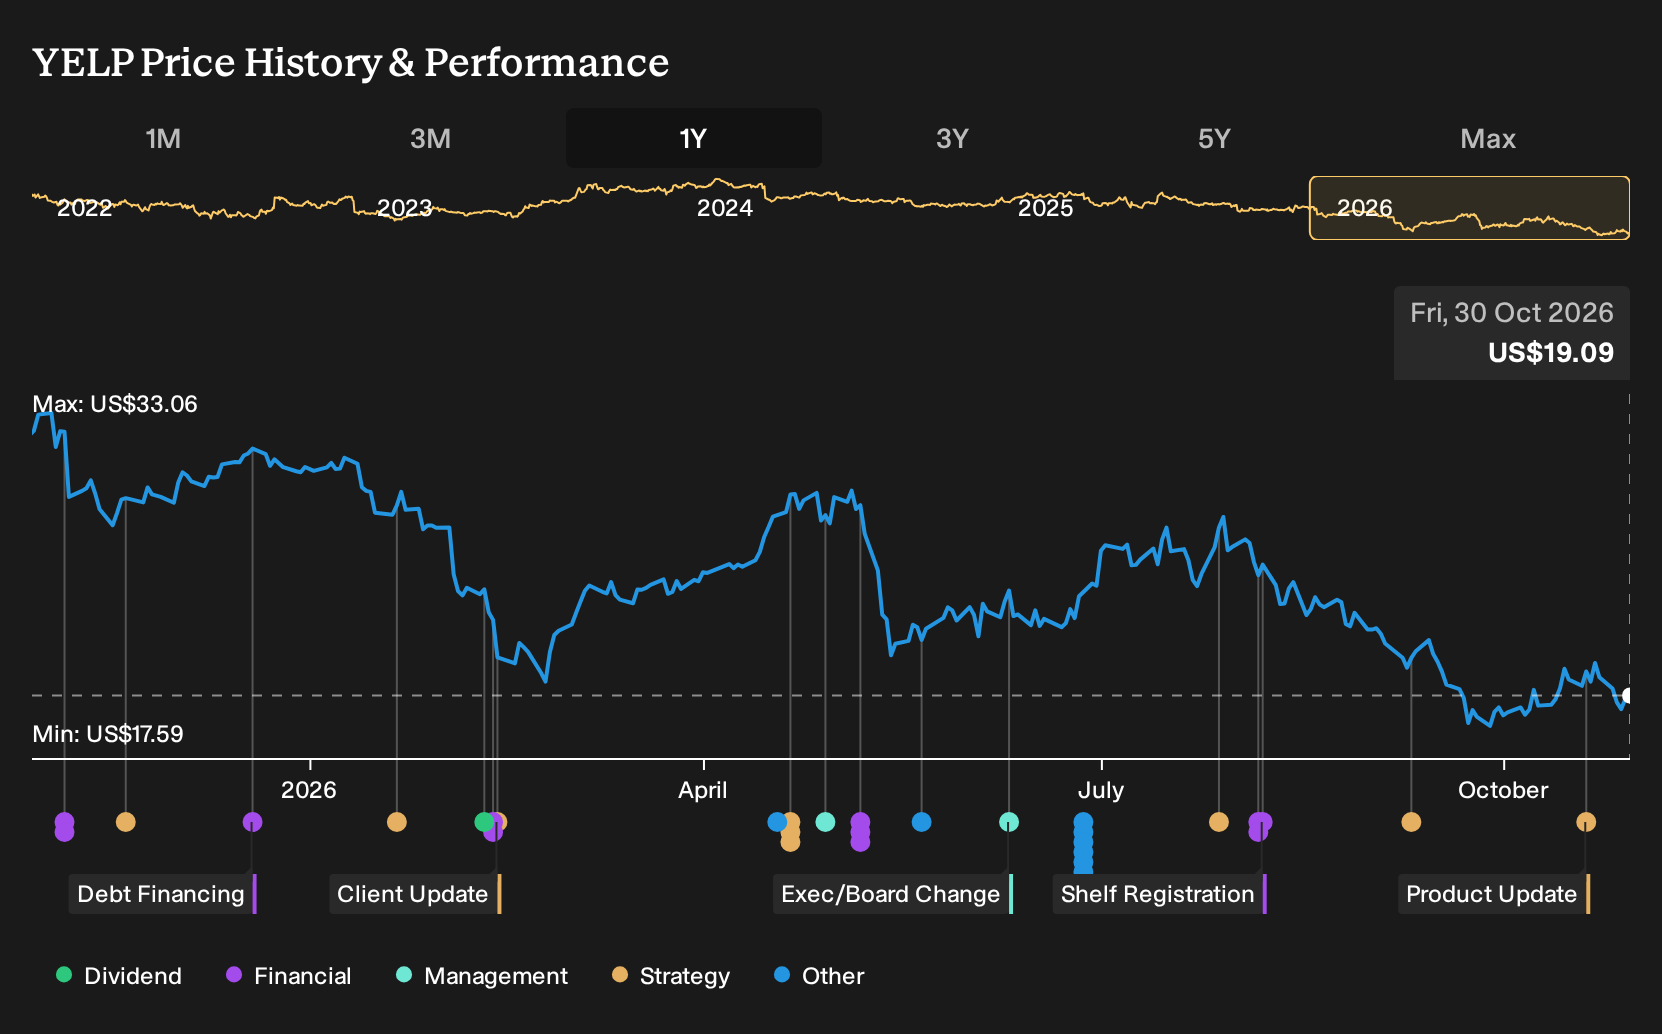
Exploring Other Perspectives
One alternate, more optimistic angle is that Yelp’s AI subscriptions become the main story for you. Bullish analysts were already penciling in revenue growth of 3.1% a year and earnings of about US$171.9 million by 2029 before this Fall Product Release. That gap in expectations shows how sharply views may shift as the new tools bed in.
Explore 4 other Yelp fair value estimates, including one that suggests a potential upside of up to 221% from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Yelp research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Yelp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yelp's overall financial health at a glance.
Looking For More Ideas Beyond Yelp?
Once you have a view on Yelp and its AI heavy roadmap, it often helps to widen the lens and compare it with other companies that share similar traits in quality, balance sheet strength or potential mispricing.
- If you want exposure to potential mispriced opportunities with solid fundamentals, start by scanning a curated 33 high quality undervalued stocks that might warrant a closer look.
- If capital preservation matters just as much as upside, focus your attention on a 29 resilient stocks with low risk scores that screens for resilience first.
- If you prefer steadier businesses with healthy finances, filter through a list of solid balance sheet and fundamentals (24 results) to see which companies have the support to ride out tougher periods.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com