


EN
Middlesex Water (MSEX) Posts Strong Q3 And Lifts Dividend, Is The Stock Pricey?
Middlesex Water (MSEX) is back on investors’ radar after Q3 2026 results showed higher sales and earnings, followed closely by the utility’s 54th consecutive annual dividend increase earlier in October.
The recent 2.6% 1-day share price return and 6.0% 1-month share price gain suggest investors are warming to Middlesex Water again, even though the 1-year total shareholder return of 1.5% and 5-year total shareholder return, which is down 39.3%, point to a much tougher longer-term journey.
Scan how Middlesex Water stacks up against other regulated utilities and income ideas by reviewing our curated list of 5 dividend fortresses.
After a sharp Q3 earnings beat and a fresh dividend lift, Middlesex Water has already rewarded investors who stepped in earlier this year. The key issue now is whether most of the upside has already been claimed or not.
Preferred P/E of 20.9x: Is it justified?
Middlesex Water now trades on a P/E of 20.9x, and that figure sits at the center of how the market is weighing its recent earnings momentum against a share price of $56.79.
The P/E ratio compares the current share price to earnings per share. For a regulated utility like Middlesex Water it often reflects what investors are willing to pay for steady profit streams and modest growth. With earnings growing 21% over the past year and 4.7% per year over five years, a higher earnings multiple can indicate that the market is comfortable paying up for consistency and a long operating history rather than rapid expansion.
Compared to peers, the picture is mixed and the gaps are not trivial. The stock trades on a P/E of 20.9x, which is slightly below the peer average of 21.5x and below the broader Water Utilities industry average of 22.3x. However, it is above the Global Water Utilities industry average of 16.4x and well ahead of an estimated fair P/E of 17.1x that the SWS model suggests the market could eventually gravitate toward.
Explore the SWS fair ratio for Middlesex Water.
Result: Price-to-earnings of 20.9x (OVERVALUED)
Still, the recent share price rebound sits against 3-year and 5-year total returns that are down 10.2% and 39.3%, which could restrain enthusiasm.
Find out about the key risks to this Middlesex Water narrative.
Another view on Middlesex Water’s value
The earnings multiple points to a stock that looks a bit rich. The SWS DCF model takes a different route and values Middlesex Water’s future cash flows at $40.72 per share, well below the current $56.79 price. If the cash flow view is right, how much margin for error do you really have?
Look into how the SWS DCF model arrives at its fair value.
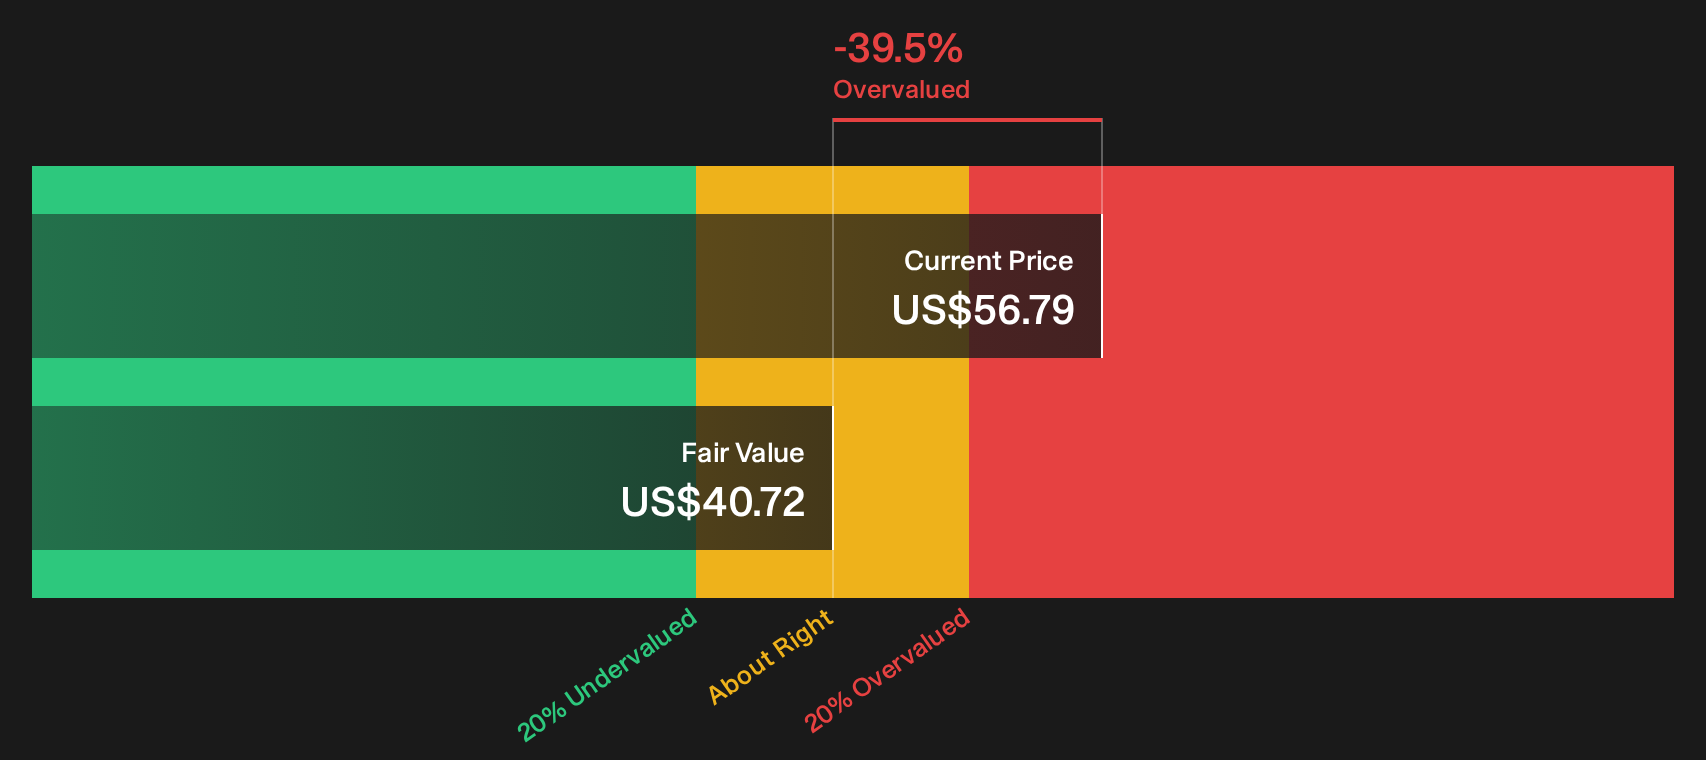
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Middlesex Water for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Middlesex Water leave you on the fence, move quickly to review both sides of the story and shape your own view with the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Middlesex Water?
Do not stop at one utility. Broaden your watchlist with a few focused stock ideas that match different goals and risk levels, so you are not relying on a single theme.
- Target potential mispricing by scanning a curated pool of quality companies that look cheap on fundamentals through the 33 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses with cleaner finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for promising smaller stocks with resilient metrics before the crowd pays attention by checking the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com