


EN
Can China Shenhua Energy (SEHK:1088) Justify Its Premium On Nine Month Earnings?
China Shenhua Energy (SEHK:1088) just posted nine-month earnings to September 30, 2026, reporting net income of CNY 47,317 million and basic EPS from continuing operations of CNY 2.198, slightly ahead of last year.
Recent trading has been choppy for China Shenhua Energy, with a 7.42% 7 day share price return and the stock at HK$42.56 after a 1 day move of 1.87%. The 30 day share price return is down 4.06% and the 90 day share price return is down 2.07%. Longer term momentum remains positive, with a year to date share price return of 7.31% and a 5 year total shareholder return of 320.10%, hinting that investors have generally been rewarded for staying invested as earnings updates filter into expectations.
Scan how China Shenhua Energy compares with other cash generative, asset heavy operators by reviewing our hand picked list of solid balance sheet and fundamentals (199 results).China Shenhua Energy looks like a solid cash engine, yet the share price has cooled over the past month after a long winning run. Is this one of those moments where quality and value actually line up?
Preferred P/E of 14.2x: Is it justified for China Shenhua Energy?
On simple earnings terms China Shenhua Energy trades on a P/E of 14.2x, which screens as expensive next to both its own fair multiple estimate and sector peers, even though the last close sits at HK$42.56 with a sizeable discount to some intrinsic value models.
The P/E ratio compares the current share price to earnings per share. For a coal and power producer like China Shenhua Energy, it effectively shows how much investors are paying today for each unit of profit from a mature, cash-generative operation.
Management is being valued at a richer multiple than the Asian Oil and Gas industry average P/E of 10.8x and above the peer average of 8.2x. This suggests the market is paying a clear premium for 1088's earnings profile instead of a discount.
That premium also sits above an estimated fair P/E of 13.1x. This points to a level the valuation could gravitate toward if sentiment or expectations cool off.
Explore the SWS fair ratio for China Shenhua Energy.
Result: Price-to-Earnings of 14.2x (OVERVALUED)
Still, China Shenhua Energy faces real swing factors, from coal policy shifts to power pricing changes that could reset what investors are willing to pay.
Find out about the key risks to this China Shenhua Energy narrative.
Another View on China Shenhua Energy’s Value
There is a twist. While China Shenhua Energy screens as expensive on a 14.2x P/E ratio versus a fair ratio of 13.1x and cheaper peers, the SWS DCF model suggests the shares trade at a steep discount to an estimated HK$95.49 future cash flow value. Which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
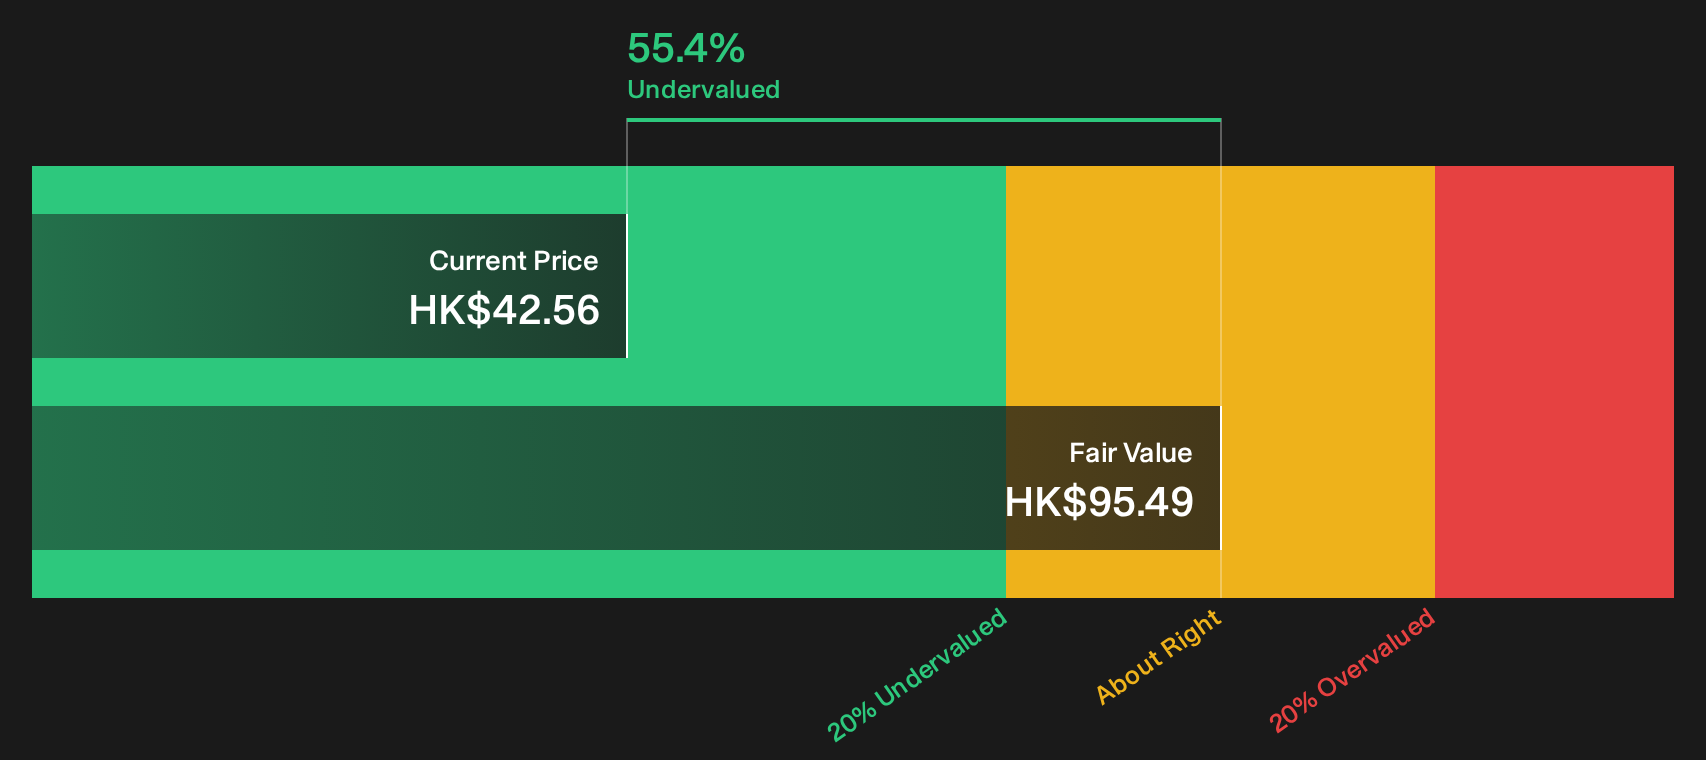
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Shenhua Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 204 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on China Shenhua Energy often create some of the most interesting entry points for fresh research. Move quickly and pressure test the numbers yourself. To balance the optimism around potential rewards with the caution around flagged risks, go through the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond China Shenhua Energy?
If you stop at China Shenhua Energy, you risk missing other opportunities that line up better with your risk tolerance, income needs, or value focus.
- Target stronger downside protection by scanning a 218 resilient stocks with low risk scores that filters for resilience when markets turn rough.
- Hunt for quality at a reasonable price by reviewing a 204 high quality undervalued stocks that screens for companies combining robust cash flows with solid balance sheets.
- Build a more reliable income stream by checking a 222 dividend fortresses built around companies offering higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com