


EN
Hilltop Holdings (HTH) Could Be 11% Undervalued On Mixed Q3 Results And Buybacks
Hilltop Holdings (HTH) just delivered a mixed third quarter update that combined higher net interest income, lower net income, rising net charge offs, and completion of a fresh US$20 million share repurchase tranche.
Recent price action suggests investors are still weighing that story. The share price is up 9.5% year to date with a 17.4% total shareholder return over twelve months. However, the 90 day share price return declined 6.6% as higher net charge offs, softer quarterly earnings and the latest US$0.22 dividend affirmation temper short term momentum for Hilltop Holdings at US$37.12.
Compare how Hilltop Holdings aligns with other banks facing similar credit costs and capital return decisions by reviewing our curated list of 29 resilient stocks with low risk scores.
Hilltop Holdings now trades at a price that sits between a modest discount to analyst targets and a much steeper gap to some intrinsic value estimates. Which reference point tells the truer story of fair value?
Most Popular Narrative: 10.9% Undervalued
On the most followed view, Hilltop Holdings screens as modestly undervalued with a fair value of $41.67 against the recent $37.12 close. This raises a clear question about what assumptions investors are already baking into that gap.
The current valuation implies that Hilltop Holdings’ share price already reflects a fair outcome where solid bank and broker dealer profitability and active capital returns are offset by mortgage losses, slow net interest income growth, and the risk of weaker efficiency and earnings.
See why 1 investors see Hilltop Holdings as 11% undervalued.
Result: Fair Value of $41.67 (UNDERVALUED)
Still, the Hilltop Holdings story could be knocked off course if mortgage losses linger at PrimeLending or if fresh credit issues push net charge offs higher again.
Find out about the key risks to this Hilltop Holdings narrative.
Another View: Hilltop Holdings Looks Expensive On Earnings
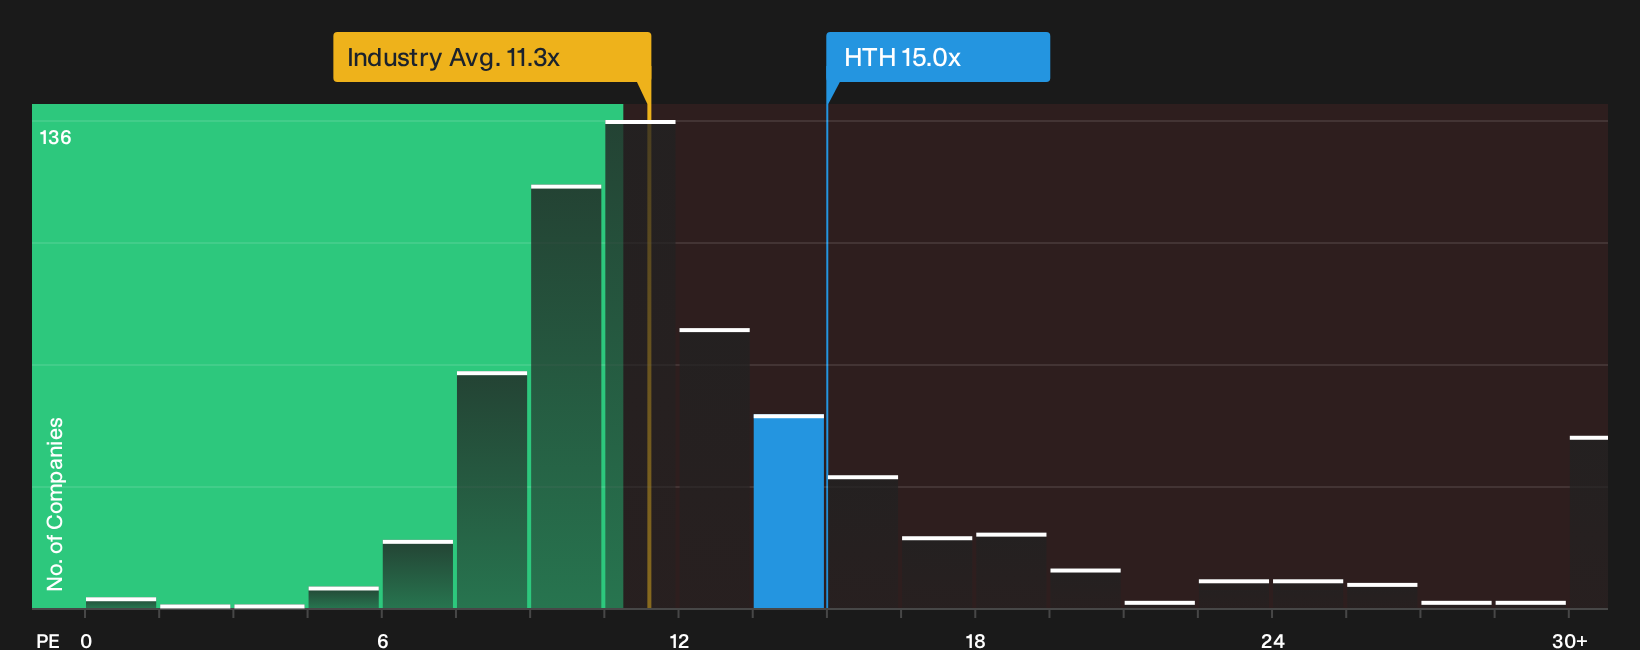
Through the lens of earnings multiples, Hilltop Holdings screens as expensive. The stock trades on a P/E of 15x compared with 11.4x for both the US Banks industry and direct peers, while the fair ratio is 9.7x. That gap raises a simple question: How comfortable are you paying a richer multiple when earnings growth is under pressure?
Before leaning too heavily on that comparison, it is worth seeing what a more detailed valuation breakdown suggests about the trade off between quality and price for Hilltop Holdings, starting with the See what the numbers say about this price — find out in our valuation breakdown.
Investors who want to visualise how that premium P/E stacks up against sector norms can also review the latest comparison in the
Next Steps
Mixed signals around Hilltop Holdings can pull investors in different directions. Move quickly past the headline takeaways and stress test the data yourself with the full picture of 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Hilltop Holdings?
If you want to pressure test your thinking after looking at Hilltop Holdings, the next smart step is lining it up against fresh opportunities.
- Target potential mispricing by scanning companies that combine quality fundamentals with appealing valuations through the 33 high quality undervalued stocks.
- Strengthen your defensive side by reviewing businesses with healthier finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for overlooked potential by checking companies with strong fundamentals that many investors may have missed inside the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com