


EN
How Investors Are Reacting To COPT Defense Properties (CDP) Raised Earnings Guidance
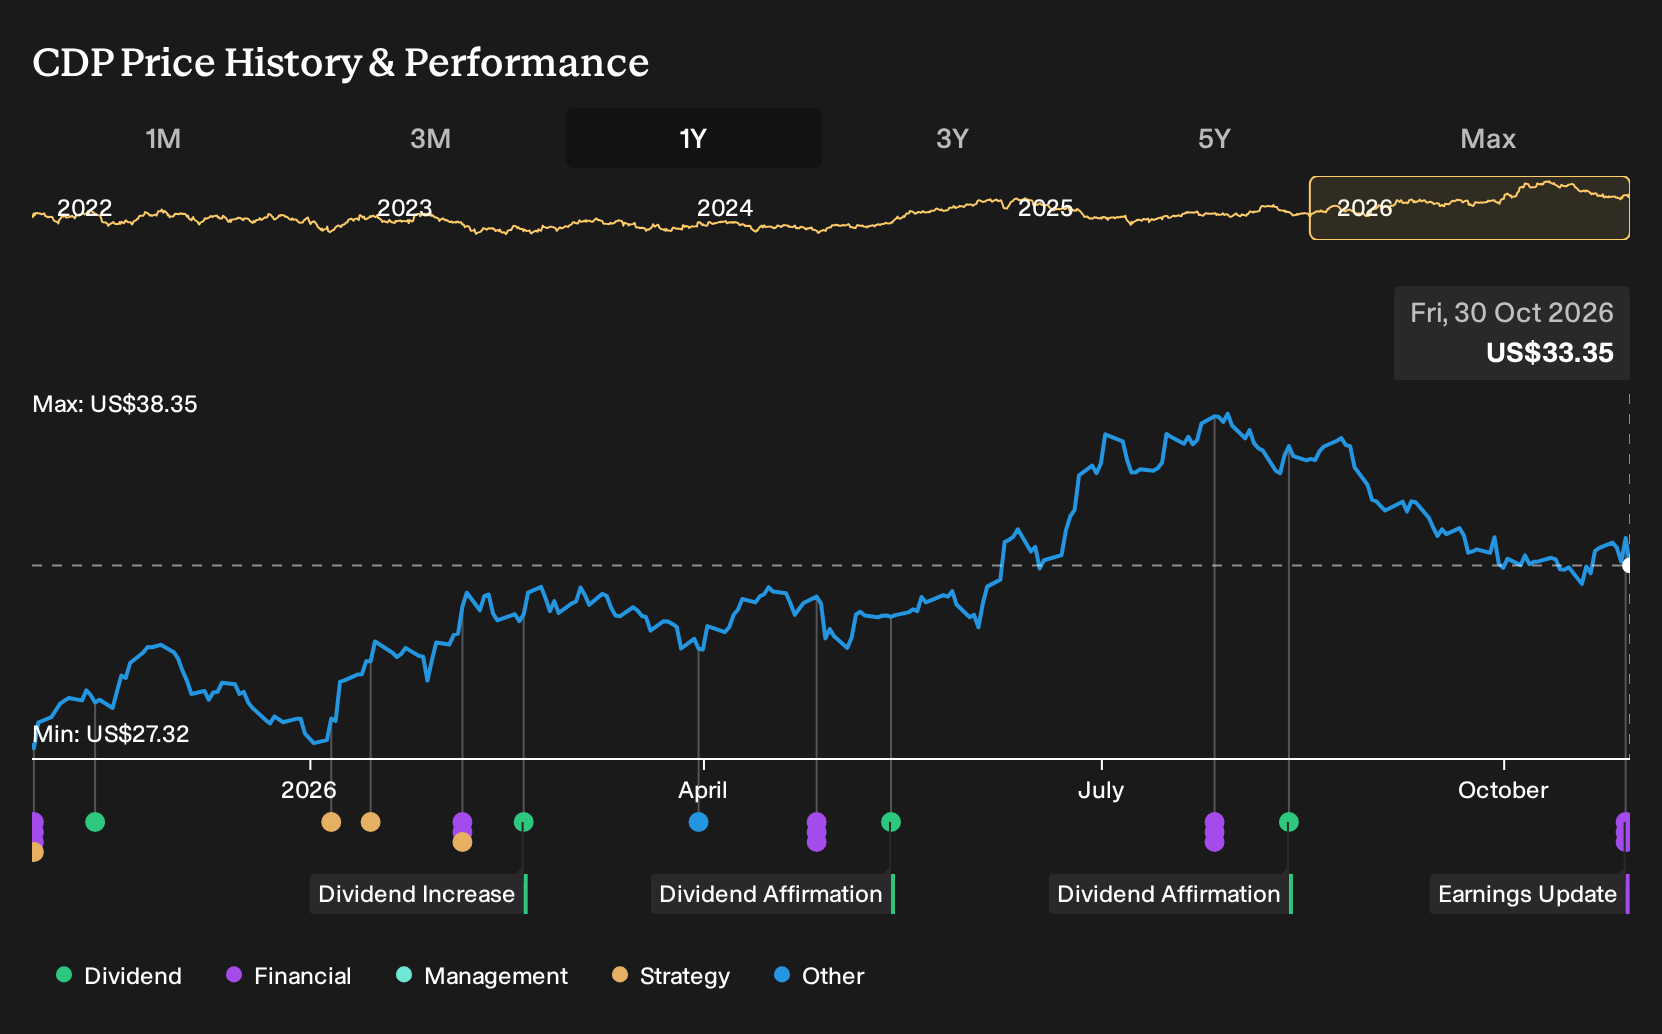
- COPT Defense Properties reported Q3 2026 results in late October with year over year increases in sales, revenue, net income and diluted EPS, alongside higher full year earnings guidance.
- Management pointed to strong leasing demand from defense focused tenants and higher capital commitments to new projects, indicating confidence in mission critical facility demand despite financing headwinds.
- We will now look at how COPT Defense Properties' raised full year EPS guidance affects the investment narrative around defense driven leasing demand.
Scan how COPT Defense Properties fits into the broader defense and infrastructure story by comparing it with 41 power grid technology and infrastructure stocks.
COPT Defense Properties Investment Narrative Recap
To own COPT Defense Properties, you need to believe that demand for secure defense focused facilities stays healthy enough for leasing and development to keep offsetting higher interest costs. The latest quarter supports that premise, with higher year over year sales, revenue, net income and EPS pointing to a business that is still converting its high occupancy portfolio into cash flow.
The near term swing factor is execution on leasing and development, as same property NOI growth is expected to moderate. The biggest risk remains interest expense. Management already flags refinancing and exchangeable notes as a drag on funds from operations growth, so more expensive debt could quickly weigh on earnings capacity.
The clearest operational signal in this update is the raised 2026 diluted EPS guidance, now with a midpoint between US$1.43 and US$1.45. Combined with the Q3 EPS of US$0.41 and nine month EPS of US$1.15, that tighter range gives you a more defined earnings path against which to judge whether leasing, development and interest costs are tracking as hoped.
For catalysts, that full year guide now underpins management’s decision to keep committing capital to new defense linked projects and a largely pre leased pipeline. The same guidance also frames the risk side. Interest payments are already flagged as less comfortably covered, so any further refinancing at similar or higher rates could pressure future funds from operations even if occupancy and development leasing stay solid.
COPT Defense Properties' current earnings are reported at US$163.5 million, with analysts forecasting consensus earnings of US$166.3 million by 2029. This implies an earnings increase of about US$2.8 million, alongside forecast revenue of US$877.7 million by that same year and an assumed 3.7% yearly revenue growth rate.
Uncover why COPT Defense Properties' fair value indicates a 19% potential upside to its current price that could narrow quickly.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your COPT Defense Properties research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for COPT Defense Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate COPT Defense Properties' overall financial health at a glance.
Looking for more investment ideas beyond COPT Defense Properties?
If you want to pressure test your view on COPT Defense Properties against other opportunities, use the Simply Wall St Screener to surface stocks that fit different risk and return profiles.
- For investors who want potential mispricing with quality behind it, start by scanning a curated set of 33 high quality undervalued stocks that may warrant a closer look.
- If resilience and balance sheet strength sit at the top of your checklist, filter for companies in the list of solid balance sheet and fundamentals (24 results) to see which ones match your risk tolerance.
- Those hunting for ideas in less crowded territory can comb through a focused pool of 19 high quality undiscovered gems that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com