


EN
Hong Kong And China Gas (SEHK:3) Draws Focus After Green Energy Summit As Valuation Looks Pricey
The recent “Empowering a Sustainable Future” Summit co-hosted by Hong Kong and China Gas (SEHK:3) has put the utility’s hydrogen pilot work and renewable energy efforts in sharper focus for investors.
Recent trading suggests that interest in Hong Kong and China Gas is edging higher, with a 30‑day share price return of 2.32% and a 90‑day gain of 3.41% from a recent close of HK$7.27. The 1‑year total shareholder return of 5.61% sits alongside a much stronger 3‑year total shareholder return and a weaker 5‑year record, which together indicate that momentum may be rebuilding after a tougher stretch.
Scan beyond Hong Kong and China Gas and compare its green energy push with 41 power grid technology and infrastructure stocks, which could also benefit from energy security and grid upgrade spending.
Bulls point to Hong Kong and China Gas’s green push and recent share gains, while bears flag the weaker 5 year record and valuation risk. As you weigh the stock’s pricing, which side do the current numbers appear to support?
Preferred P/E of 21.3x for Hong Kong and China Gas: Is it justified?
On valuation, the clearest signal for Hong Kong and China Gas is its P/E of 21.3x at a last close of HK$7.27, which suggests investors are paying a premium versus both local peers and the wider Asian gas utilities group.
The P/E ratio compares the current share price to earnings per share and, in simple terms, reflects how many dollars investors are willing to pay for each dollar of profit. For a regulated utility with relatively modest forecast revenue growth of 1.2% per year and earnings growth of 2.3% per year compared with the broader Hong Kong market, a high P/E usually implies the market is assigning extra value to stability, dividends, or future projects such as its renewable and hydrogen work.
Recent data shows earnings grew 12.9% over the past year, ahead of its 5 year earnings growth rate of 1.4% per year and stronger than the Gas Utilities industry, which declined 6% over the same period. That acceleration, combined with improved net profit margins of 11.3% versus 10.2% a year earlier and high quality earnings, helps explain why buyers might tolerate a richer multiple. At the same time, the current P/E of 21.3x is described as expensive versus both the peer average of 8.5x, the Asian Gas Utilities industry average of 13.1x, and an estimated fair P/E of 9.5x. This points to a level that the market could potentially move towards if sentiment cools.
The valuation gap is stark, with Hong Kong and China Gas trading at more than double the peer average P/E, well above the broader Asian Gas Utilities group, and also far ahead of the 9.5x fair ratio estimate that implies a materially lower earnings multiple could be more aligned with its fundamentals.
Explore the SWS fair ratio for Hong Kong and China Gas.
Result: Price-to-earnings of 21.3x (OVERVALUED)
Still, the weak 5 year total return and a P/E more than double peers leave Hong Kong and China Gas exposed if sentiment toward premium utilities cools.
Find out about the key risks to this Hong Kong and China Gas narrative.
Another view on Hong Kong and China Gas valuation
That rich P/E tells one story. A second lens is the SWS DCF model, which pegs Hong Kong and China Gas at an estimated future cash flow value of HK$6.58. With the stock at HK$7.27, this approach also points to an expensive valuation. Which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
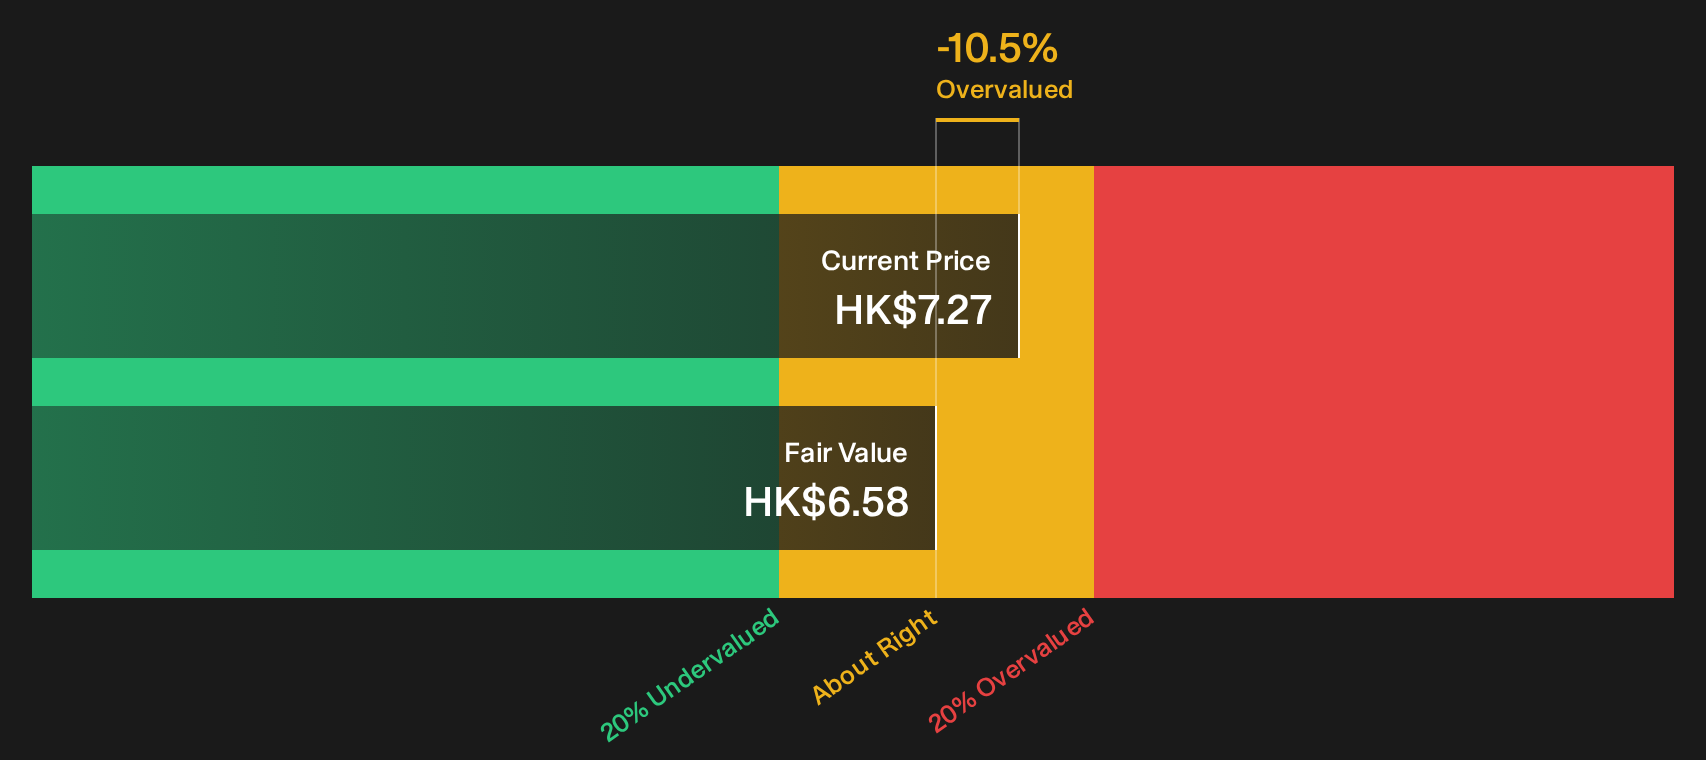
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hong Kong and China Gas for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 204 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or quiet opportunity? If Hong Kong and China Gas interests you, move quickly to review the full picture and weigh 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Hong Kong and China Gas?
If Hong Kong and China Gas has you thinking more broadly about your portfolio, do not stop here. The next opportunity could be sitting on a different watchlist.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (199 results), which filters for financial strength first.
- Hunt for potential mispriced opportunities by reviewing the 204 high quality undervalued stocks, which combines quality metrics with attractive valuations.
- Prioritise consistency and income focus by checking out the 218 resilient stocks with low risk scores, which highlights companies with more stable risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com