


EN
How Investors May Respond To Adobe (ADBE) CEO Change
- Adobe and the BWT Alpine Formula One Team announced a global premium partnership in October 2026, with Adobe named Official AI Fan Experience Partner and its CX Enterprise, GenStudio, Experience Platform and Express products set to power personalized, AI driven fan engagement from the 2027 season.
- The collaboration places Adobe software at the center of Alpine’s fan journey, connecting creative tools and data insights directly to customer experience operations and offering a real world showcase for Adobe’s AI and CX Enterprise capabilities.
- We will now look at how Adobe’s new role as Alpine’s AI Fan Experience Partner could influence the company’s broader investment narrative.
Adobe Investment Narrative Recap
To own Adobe, you need to believe its AI-first subscription engine keeps pulling more value from a huge user base while holding its pricing line against aggressive competitors. The biggest near-term swing factor is whether Firefly, agentic tools and AI-driven features inside Creative Cloud, Acrobat and CX Enterprise keep supporting annual recurring revenue despite net new ARR slowing.
The main risk is that this freemium-heavy funnel, already over 1 billion monthly active users, converts to paid plans more slowly than hoped, especially while new AI platforms undercut on price. The Alpine partnership is directionally helpful branding for AI and CX Enterprise but looks immaterial to that core ARR and monetization question.
The Trellist AI Transformation practice for Adobe Experience Cloud speaks directly to what matters more than a single sports sponsorship. It focuses on shrinking the long, manual campaign workflows inside Experience Manager, Target and Analytics, using AI agents and connectors so enterprise customers can run more experiments and campaigns through Adobe’s stack.
If that type of partner-driven execution scales, Experience Cloud usage and stickiness can deepen, which supports Adobe’s push into AI-powered customer experience as a key growth driver. The flip side is operational. If projects like this do not translate into broader deployments or measurable client value, the CX Enterprise and AI MarTech catalyst could soften while competition stays intense.
Adobe's current analyst narrative points to revenue of US$33.4b and earnings of US$9.5b by 2029, based on an assumed 8.7% yearly top line growth rate and an earnings increase of about US$2.2b from US$7.3b today.
Uncover why Adobe's fair value indicates a 10% potential upside to its current price before the discount appears less generous.
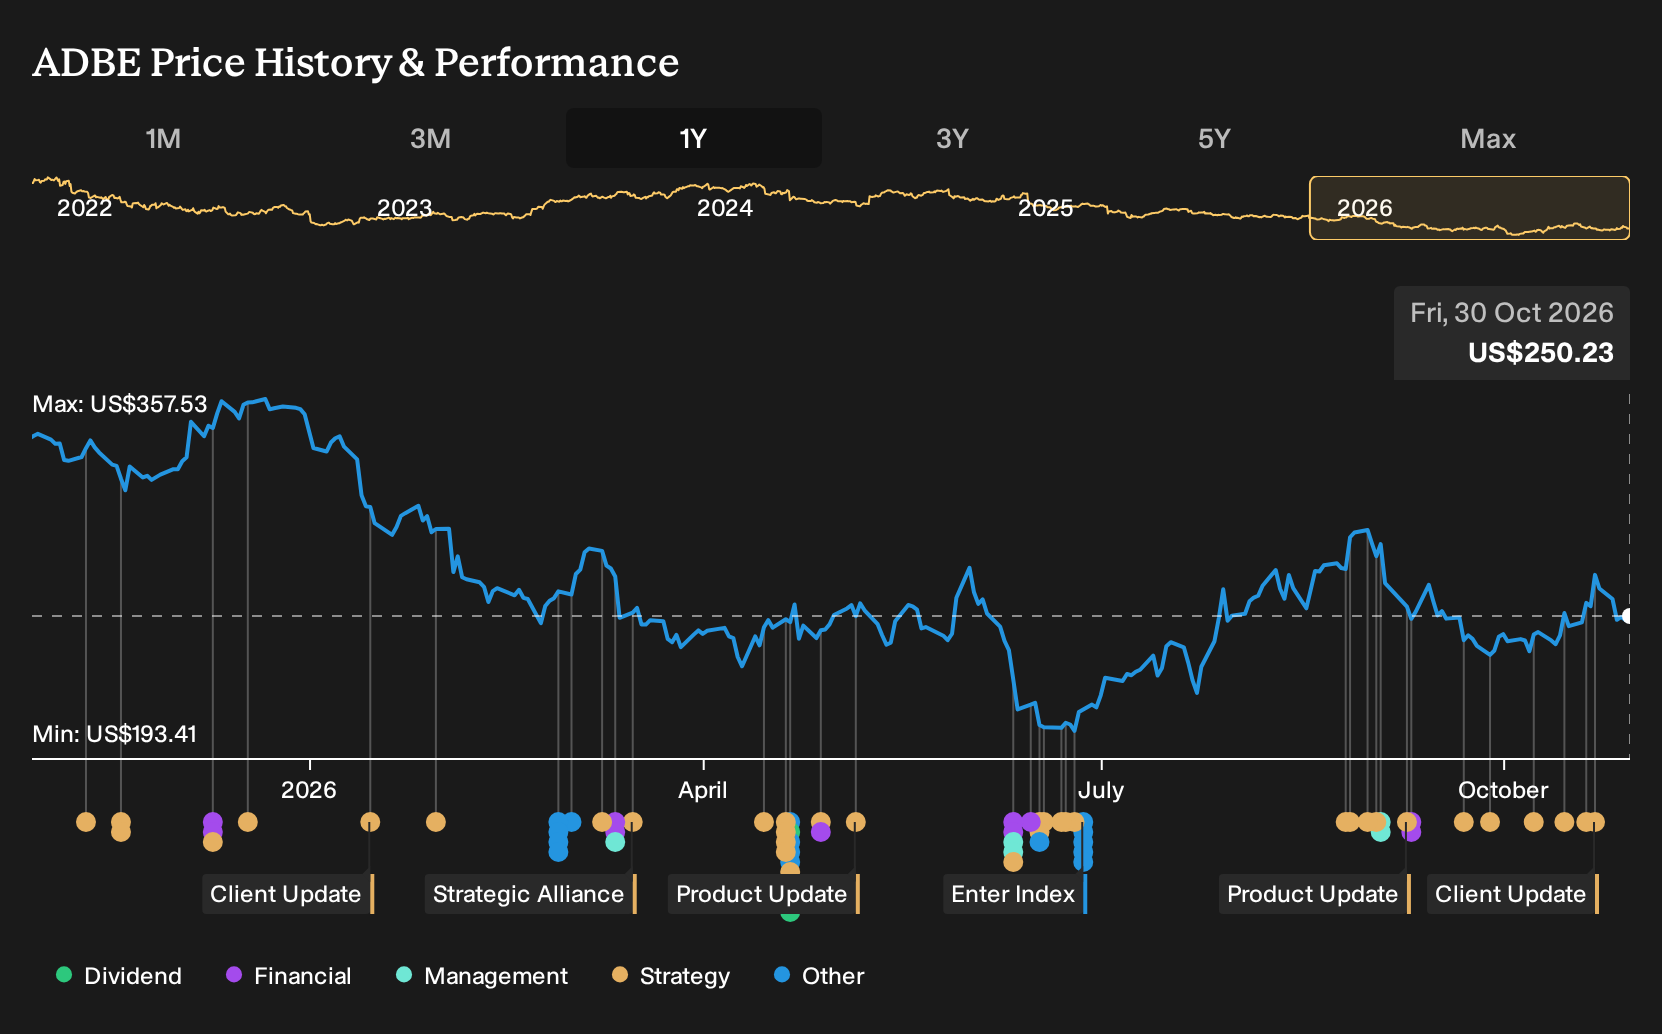
Exploring Other Perspectives
One alternate, more optimistic angle focuses on how aggressively Adobe could scale AI driven customer experiences off its freemium base. The most bullish analysts were already pencilling in revenue of US$35.5b and earnings of US$10.7b by 2029 before this Alpine news, so their story leans on AI partnerships like this to potentially reshape expectations. You do not need to agree with that view. However, it is worth exploring how far opinions can stretch before you decide where you sit.
Explore 37 other Adobe fair value estimates, including one that suggests up to 150% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Adobe research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Adobe. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Adobe's overall financial health at a glance.
Looking for more investment ideas beyond Adobe?
If Adobe's AI story has caught your attention, it can be useful to set it alongside other listed businesses with different strengths, income profiles and risk levels. Use the Simply Wall St Screener to scan the market through clear, rules based filters instead of scrolling tickers at random.
- For readers who want potential value combined with quality fundamentals, check out a 33 high quality undervalued stocks that share traits like strong cash generation and solid balance sheets.
- If capital preservation sits high on your priority list, you might prefer a 29 resilient stocks with low risk scores where balance sheet strength and risk scores do more of the heavy lifting.
- When you are hunting for less crowded opportunities with room for the story to spread, shortlist a 19 high quality undiscovered gems that already show healthy fundamentals but attract less attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com