


EN
Does Solid Q3 Earnings Change The Bull Case For Minerals Technologies Stock?
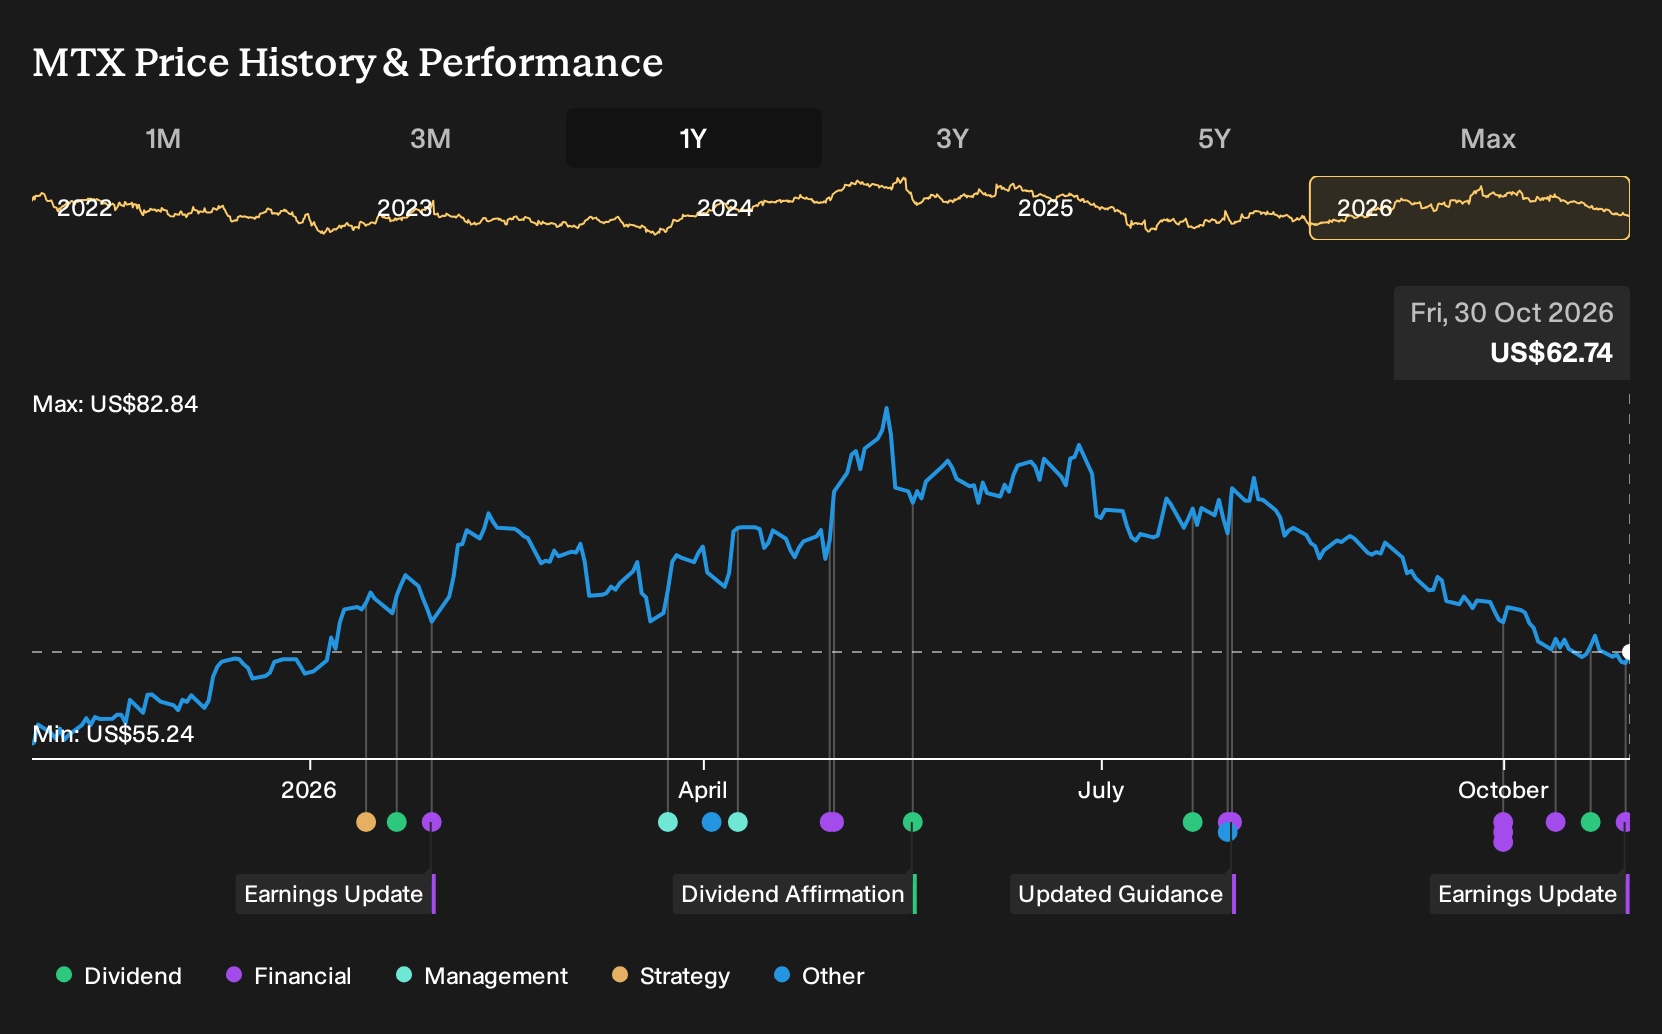
- Minerals Technologies reported third quarter 2026 sales of US$554.9 million and net income of US$42.7 million, with earnings per share from continuing operations of US$1.37. The company also outlined higher nine month sales but a loss tied to previously disclosed talc related charges.
- The board approved an 8% increase in the regular quarterly dividend to US$0.13 per share, signaling confidence in Minerals Technologies' cash generation. Management also pointed to a US$1.4 billion product pipeline and efforts to improve pricing discipline and margins.
- We will now look at how Minerals Technologies' investment narrative could be shaped by the resilient Q3 earnings and reaffirmed revenue outlook.
Minerals Technologies Investment Narrative Recap
To own Minerals Technologies, you need to be comfortable with a fairly simple belief. The core businesses in specialty minerals and Engineered Solutions can convert the reported US$1.4b product pipeline and sustainability oriented projects into steady cash generation while the talc related legal overhang and cost pressures remain contained. The latest quarter, with broadly flat earnings per share versus last year, largely supports that view rather than changing it.
The most immediate positive catalyst still sits in the operating story, namely execution in Engineered Solutions, quicker pricing resets and traction in PFAS remediation and renewable fuel products. The biggest near term risk remains pressure on margins from lingering energy and freight costs and any worsening of the talc liabilities that already contributed to the nine month net loss.
The recent dividend increase to US$0.13 per share per quarter is the announcement that ties most directly into this earnings update. A higher payout usually needs support from confidence in future cash flows. For Minerals Technologies, it intersects with the narrative that the business can fund both growth projects and shareholder returns while working through the talc related charges.
For catalysts, that dividend move matters because it raises the bar for consistent free cash flow. It puts more focus on execution in high temperature technologies, PFAS remediation projects and sustainability linked products where management has pointed to a strong opportunity set. Any sustained squeeze from input costs or weaker volumes in paper related PCC would make that cash flow commitment harder to maintain.
Minerals Technologies' current earnings are a loss of US$67.2 million. Analysts forecast earnings of US$600.8 million by 2029, which implies an earnings increase of about US$668 million. Consensus also points to yearly revenue growth of 4.3%, which would take sales to a projected US$2.4b in that same year.
Uncover why Minerals Technologies' fair value indicates a 45% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$60 to about US$182, so Minerals Technologies looks wildly different depending on which private investor you listen to. Consider that spread alongside talc related legal risks, PFAS, sustainability initiatives and metals projects, then assess how each viewpoint could shape future performance.
Explore 3 other Minerals Technologies fair value estimates, including one that suggests the potential for as much as 190% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Minerals Technologies research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Minerals Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Minerals Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Minerals Technologies?
Once you understand where Minerals Technologies fits in your portfolio, it helps to compare it with other businesses that share similar qualities or offer a very different risk and reward profile.
- If you want potential upside with tighter risk controls, start with a curated group of resilient businesses through the 29 resilient stocks with low risk scores.
- For investors who care most about balance sheet strength and staying power, filter for companies with robust finances using the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for promising opportunities that are not yet widely followed, broaden your watchlist by running the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com