


EN
Badger Meter (BMI) Could Be 9% Undervalued Following Q3 Earnings And Buyback Update
Badger Meter (BMI) delivered third quarter earnings on October 22, 2026, reporting steady sales of approximately US$236 million and slightly higher net income, along with an update on its recently completed share repurchase activity.
Badger Meter’s latest figures land after a choppy run for the shares, with a strong 30 day share price return of 16.13% contrasting with a year to date share price decline of 15.88% and a 1 year total shareholder return that is down 16.82%. Recent momentum is improving, even though longer term holders are still sitting on losses overall.
Scan how Badger Meter’s recent earnings reset compares with other industrial tech plays by reviewing a hand picked list of list of solid balance sheet and fundamentals (24 results).
After that sharp swing in Badger Meter’s share price, the question is where fair value really sits between the recent quote and the range of analyst and intrinsic estimates.
Most Popular Narrative: 9% Undervalued
Badger Meter’s most followed narrative pegs fair value at $163.78, above the recent close of $148.38. This frames the current debate around whether the long list of awarded projects and software ambitions are fully reflected in the share price.
The main factor that needs to go right is execution on the large cohort of awarded but not yet fully ramped AMI and sewer monitoring projects, including PRASA and the post UDlive sewer portfolio, so that the expected second half weighting in 2026 translates into sustained volume and software attachment over the next several years.
See why 13 investors see Badger Meter as 9% undervalued.
Result: Fair Value of $163.78 (UNDERVALUED)
Still, Badger Meter’s story can be knocked off course if the large AMI and sewer projects ramp more slowly than planned or if legal disputes escalate.
Find out about the key risks to this Badger Meter narrative.
Another Angle on Badger Meter’s Valuation
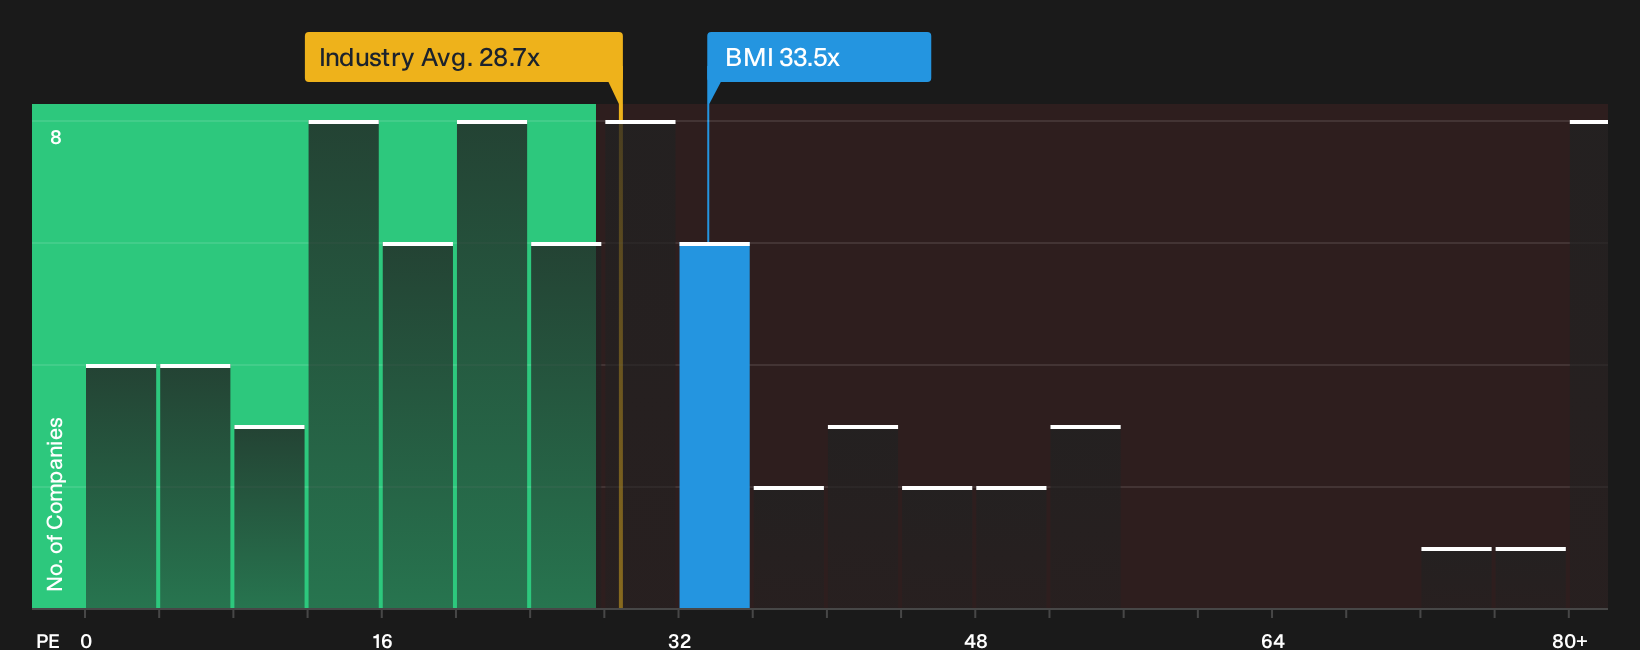
On simple P/E math, Badger Meter screens as expensive. The stock trades on 33.5x earnings, which is higher than both the US Electronic industry at 28.7x and a fair ratio of 22.9x that the regression work points to as a level the multiple could move toward over time. That gap suggests meaningful valuation risk if sentiment cools, so how comfortable are you paying a premium today for a business that analysts see growing earnings at 11% a year rather than at very high rates?
To see how that premium stacks up in detail, including the full peer comparison and the fair ratio workup, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this Badger Meter discussion leans cautious, so treat it as a starting point and move quickly to stress test the numbers yourself. To see which potential upside factor investors are focused on, review the 1 key reward
Looking for more Badger Meter sized ideas?
If Badger Meter has you rethinking your watchlist, do not stop here. Broaden your field of vision and pressure test your thesis across fresh ideas.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (24 results) that keeps financial strength front and center.
- Hunt for quality at a discount by reviewing a focused set of 33 high quality undervalued stocks that may offer more appealing entry points.
- Build a cash flow focused watchlist by zeroing in on income ideas from a group of 5 dividend fortresses that aim to pair yield with stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com