


EN
Is Macy's (M) Overvalued After Weaker EPS Expectations And More Store Closures?
Macy's (M) is back in focus after fresh headlines on weaker expected earnings and ongoing store closures raised new questions about the retailer's long term demand story and stock appeal.
Recent trading reflects that tension between concern and opportunity. Macy's share price has risen over the past month while the 90 day share price return has declined 7.1%. Yet the 1 year total shareholder return of 28.1% and 3 year total shareholder return of about 2x suggest investors who stayed through past volatility have still been rewarded, as new earnings worries and continuing store closures reset sentiment around future risk and demand expectations.
Scan how other retailers with cleaner demand trends or stronger balance sheets are setting up for the next move by reviewing our hand picked list of solid balance sheet and fundamentals (24 results) alongside Macy's.
Macy's recent rebound sits between two explanations. Is this a vote of confidence in a challenged retailer still earning US$750 million on US$22.8b of sales, or is it simply sentiment whiplash ahead of weaker EPS and more closures that could reset the multiple?
Most Popular Narrative: 3% Overvalued
With Macy's last closing at $24.11 against a widely followed fair value of $23.36, the shared narrative frames the stock as slightly ahead of its calculated worth, and pins that view on how higher end banners and AI driven efficiencies balance softer demand and execution risk.
The push toward higher AUR and a better best brand mix across Macy's, Bloomingdale's and Bluemercury, reflected in around 9% AUR growth in Q2 2026 and broader luxury growth, is intended to keep pricing power and merchandise margins intact. This can support gross margin and EPS even if unit volumes face pressure.
See why 20 investors see Macy's as 3% overvalued.
Result: Fair Value of $23.36 (OVERVALUED)
Still, if e commerce pressure erodes store traffic or luxury banners lose momentum, the current Macy's narrative on margins and earnings quality could unravel.
Find out about the key risks to this Macy's narrative.
Another View On Macy's Valuation
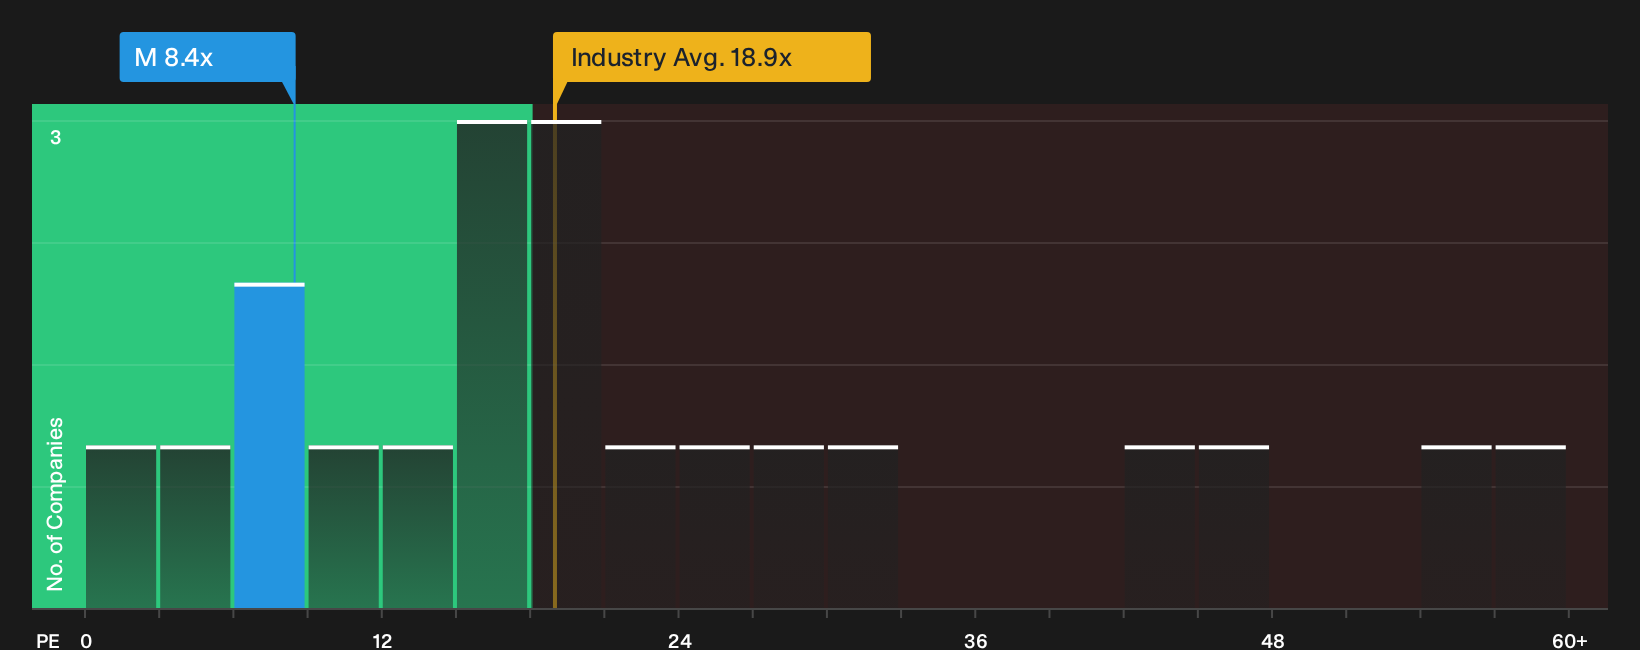
The analyst narrative frames Macy's as about 3% over its fair value at $23.36. A different lens tells another story. On a simple P/E, the stock trades at 8.4x compared with a fair ratio of 11.5x, and against roughly 18.9x for the global multiline retail group and 14.8x for peers.
That gap suggests investors are pricing in meaningful risk around earnings quality and future demand rather than paying up for recent 51.6% profit growth. The question for you is whether that discount reflects justified caution or a potential mispricing that could narrow if sentiment shifts.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Macy's can make it hard to sit still, so move quickly, review the numbers yourself, and weigh both the upside and the downside using our breakdown of 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Macy's?
If you only focus on Macy's, you risk missing other opportunities that fit your risk, income, and value style when markets move faster than headlines.
- Target dependable income by scanning for companies in the 5 dividend fortresses that might suit a yield focused portfolio.
- Hunt for quality at a discount by reviewing the 33 high quality undervalued stocks that pair solid fundamentals with pricing that still looks reasonable.
- Guard your downside by filtering for the 29 resilient stocks with low risk scores that can help steady returns when sentiment turns choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com