


EN
Could Higher Nine Month Profit Alter The Investment Case For Redeia Corporación (BME:RED)?
- Redeia Corporación reported nine month 2026 sales of €1,312.9 million and net income of €410.3 million, both higher than a year earlier.
- The combination of stronger sales and higher profit indicates that Redeia Corporación is currently converting its regulated infrastructure footprint into solid earnings.
- This context provides a basis for examining how Redeia Corporación's higher nine month net income could shape the investment narrative that investors focus on.
Redeia Corporación Investment Narrative Recap
To be a shareholder in Redeia Corporación, you need to be comfortable with a regulated grid operator that leans on long term visibility rather than rapid expansion. The thesis rests on steady transmission capex in Spain, a largely regulated earnings mix and tight execution under the 2026 to 2031 framework. The latest nine month numbers show sales of €1,312.9 million and net income of €410.3 million, which supports that steady profile rather than changing it.
The most important short term swing factor remains the regulatory and funding balance. Appeals around remuneration and inflation indexation, along with a capex heavy period funded by debt and hybrids, still look like the key near term drivers for sentiment and for Redeia Corporación’s flexibility. This earnings update does not materially change those risks, but it offers some reassurance that core operations are holding up while that plays out.
The earnings announcement for the nine months to September 30, 2026 is the clearest reference point for those drivers. Sales of €1,312.9 million compared with €1,218.1 million a year earlier and net income of €410.3 million compared with €389.8 million show Redeia Corporación running its regulated grid and related activities with a relatively stable profit profile while the capex plan ramps.
For catalysts, that update helps you judge whether ongoing Spanish transmission investment and the planned 2026 to 2029 program are being supported by current cash generation. It also sits against the backdrop of risks flagged around debt coverage and dividend funding. Investors tracking Redeia Corporación will likely use these reported figures as a checkpoint on execution, especially as the balance sheet absorbs heavier investment and relies more on external financing.
Analysts currently frame Redeia Corporación around a path to €2.0b of revenue and €559.6 million of earnings by 2029. Their view is built on 4.8% yearly top line growth and an earnings increase of about €76.8 million from €482.8 million today.
Uncover why Redeia Corporación's fair value indicates a 7% potential upside to its current price that may not last much longer.
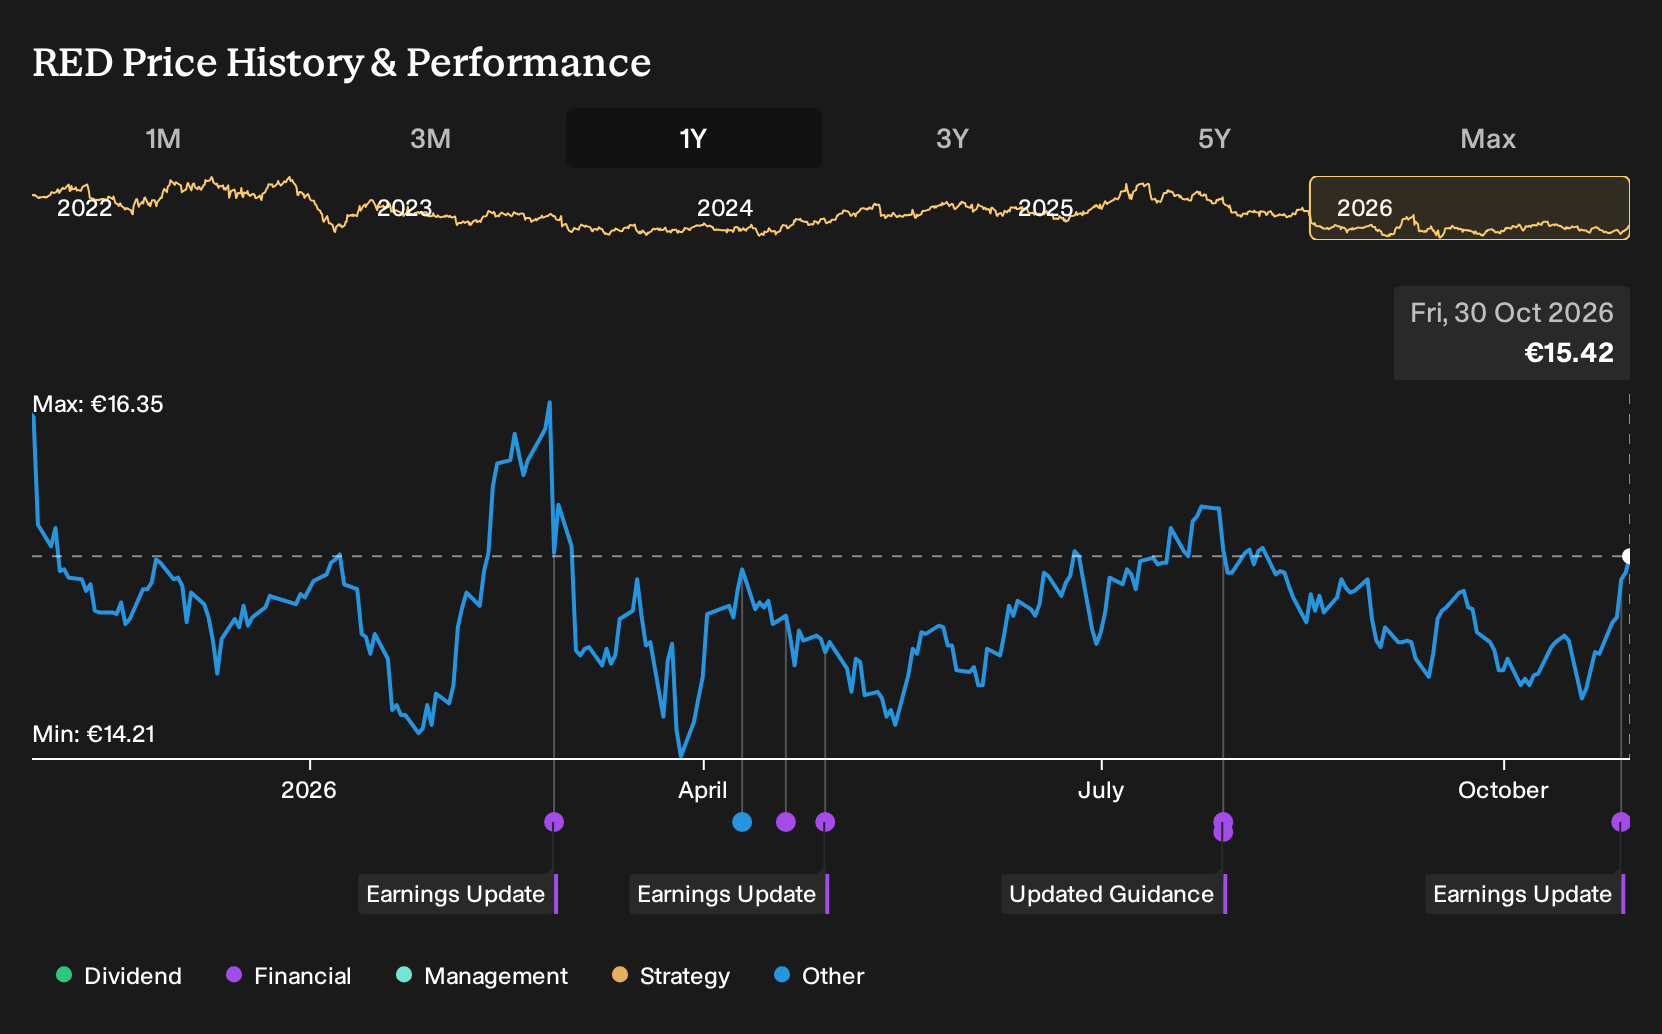
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between €12.84 and €16.56 per share, so you are seeing a tight band rather than outliers. Those views sit alongside meaningful regulatory and funding risks around Redeia Corporación. Use that contrast to test your own stance and compare several competing viewpoints.
Explore 3 other Redeia Corporación fair value estimates, including one that suggests as much as 17% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Redeia Corporación research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Redeia Corporación. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Redeia Corporación's overall financial health at a glance.
Looking For More Investment Ideas Beyond Redeia Corporación?
If you want to stress test your view on Redeia Corporación, it helps to line it up against other listed businesses with very different income profiles. Use the Simply Wall St Screener to scan for alternatives that fit your risk tolerance, income needs and balance sheet preferences.
- Prefer resilient earnings and fewer financial shocks over excitement. Screen for 218 resilient stocks with low risk scores that score well on stability and risk controls.
- Interested in steady income streams that might complement Redeia Corporación. Filter for 222 dividend fortresses and compare yields, payout ratios and histories.
- Want to get in early on quieter stories with decent fundamentals. Sort through 614 high quality undiscovered gems and see which ones merit a place on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com