


EN
NCR Voyix (VYX) Stock Looks Expensive Following Its 69% Five Year Fall
NCR Voyix has climbed recently, yet the longer record for the stock is weak. This puts the focus squarely on whether today's valuation makes sense when set against its earnings power. With that backdrop, the key question for investors is how the current price reflects what the business is actually generating in profit.
- Over the past 5 years the share price has fallen 68.6%, which raises the issue of how much of the earlier optimism about the company’s earnings is still embedded in today’s US$8.48 level.
- The new agreement to roll out NCR Voyix’s Aloha Next point of sale and kitchen software across Bruster’s Real Ice Cream locations may support expectations for more durable transaction based revenue and potentially steadier earnings over time.
- Your read on NCR Voyix is one view; the desks covering it have another. See what analysts think NCR Voyix's shares could be worth.
The stock's next move may depend on whether NCR Voyix's current share price is well supported by the earnings that the business is producing today.
If you want a wider hunting ground while you assess whether NCR Voyix's earnings justify its recent move, a focused screen of 33 high quality undervalued stocks is a useful next step.
Has NCR Voyix Run Too Far on Earnings?
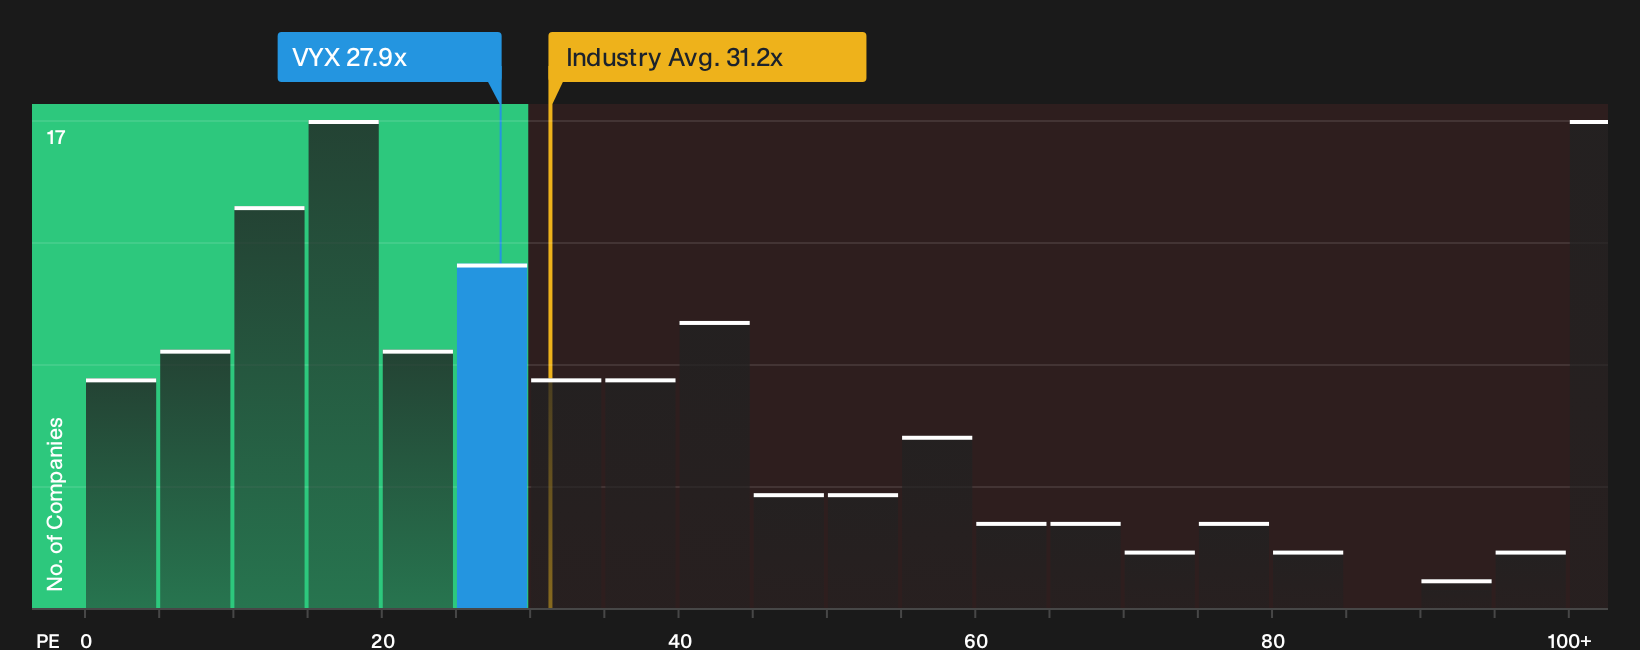
The P/E ratio fits NCR Voyix because investors are focused on what the business is currently earning per share. On that yardstick, the stock trades on about 27.9x earnings, which is below both the broader software industry average of roughly 31.2x and the closer peer group near 42.0x.
Because the recent Bruster’s rollout has sharpened attention on the Aloha Next platform, the current multiple suggests the market is still applying a valuation premium to NCR Voyix compared with what a more tailored benchmark would imply, so the shares screen overvalued on this framework. That fair benchmark reflects a blend of the group’s growth profile, profitability, market size and risk, so the gap points to investors paying up today for the earnings that are already visible. Explore the numbers behind NCR Voyix's P/E valuation.
The NCR Voyix Narrative: What Would Justify Today's Price?
NCR Voyix's valuation puzzle only really comes into focus when the assumptions behind it are laid out in plain view. Simply Wall St Narratives aim to do exactly that by spelling out what would need to happen to NCR Voyix's future growth, margins, and earnings for the stock to be worth materially more or less than it is today. Rather than relying on a single ratio or model output, each narrative sets out its own underlying assumptions so you can compare those with actual results as they are reported on the Community page.
One of the top community narratives on NCR Voyix: 43% undervalued
"Further expansion of Voyix Connect and attachment of Voyix Pay and fleet card integrations on top of an existing roughly US$800b domestic volume base..."
Discover why this Narrative puts NCR Voyix at 43% undervalued.
One more NCR Voyix check that belongs beside the price tag
Before you treat NCR Voyix's current valuation as the whole story, it is worth seeing what the broader checks are flagging about potential pressure points inside the business. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com