


EN
Diageo (LSE:DGE) Could Be 12% Undervalued On Its Premium Product Push
Diageo’s latest product launches and why they matter for the stock
Diageo (LSE:DGE) has put collectors and cocktail fans in the spotlight with two fresh releases, and those launches now frame how the market is reassessing the shares.
Orphan Barrel’s Latverian Cask, inspired by Marvel Studios' Avengers: Doomsday, is a once only American Light Whiskey release that leans heavily into scarcity and storytelling. The CÎROC Martini Machini, an interactive martini mixer, pushes Diageo’s brands into more experiential drinking occasions at home.
These launches land as Diageo’s share price has started to recover some ground, with a 1 month share price return of 9.71% and a year to date share price return of 9.30%, even though the 5 year total shareholder return is still down 46.57%.
Capitalize on Diageo’s premium push by scanning a curated set of spirits and beverage stocks that also lean into high-end demand through the 5 high quality undiscovered gems.Recent price gains hint at either a quiet repair in Diageo’s underlying business or a sharp mood swing in how the market feels about the shares. Which story does the current valuation tell?
Most Popular Narrative: 12% Undervalued
Diageo’s most followed narrative pegs fair value at £20.08, versus a last close of £17.57. That gap frames how investors weigh the recent product launches against the long running restructuring story.
The main thing that has to go right is that Diageo executes the multi year restructuring and North America turnaround without major disruption. In that case, the targeted overhead reductions, route to market changes and category strategies in key regions would translate into sustained operating profit and free cash flow delivery.
The current valuation implies the share price already reflects cautious assumptions on near term net sales growth and North America pressure. If Diageo delivers on its plan for mid single digit operating profit growth, material recurring savings and multi year capex behind Guinness, the stock appears undervalued on this narrative.
See why 156 investors see Diageo as 12% undervalued.
Result: Fair Value of £20.08 (UNDERVALUED)
Still, the Diageo story can break if alcohol moderation accelerates and if execution stumbles in higher risk regions such as Africa and Latin America.
Find out about the key risks to this Diageo narrative.
Another View: What Diageo’s P/E Is Really Saying
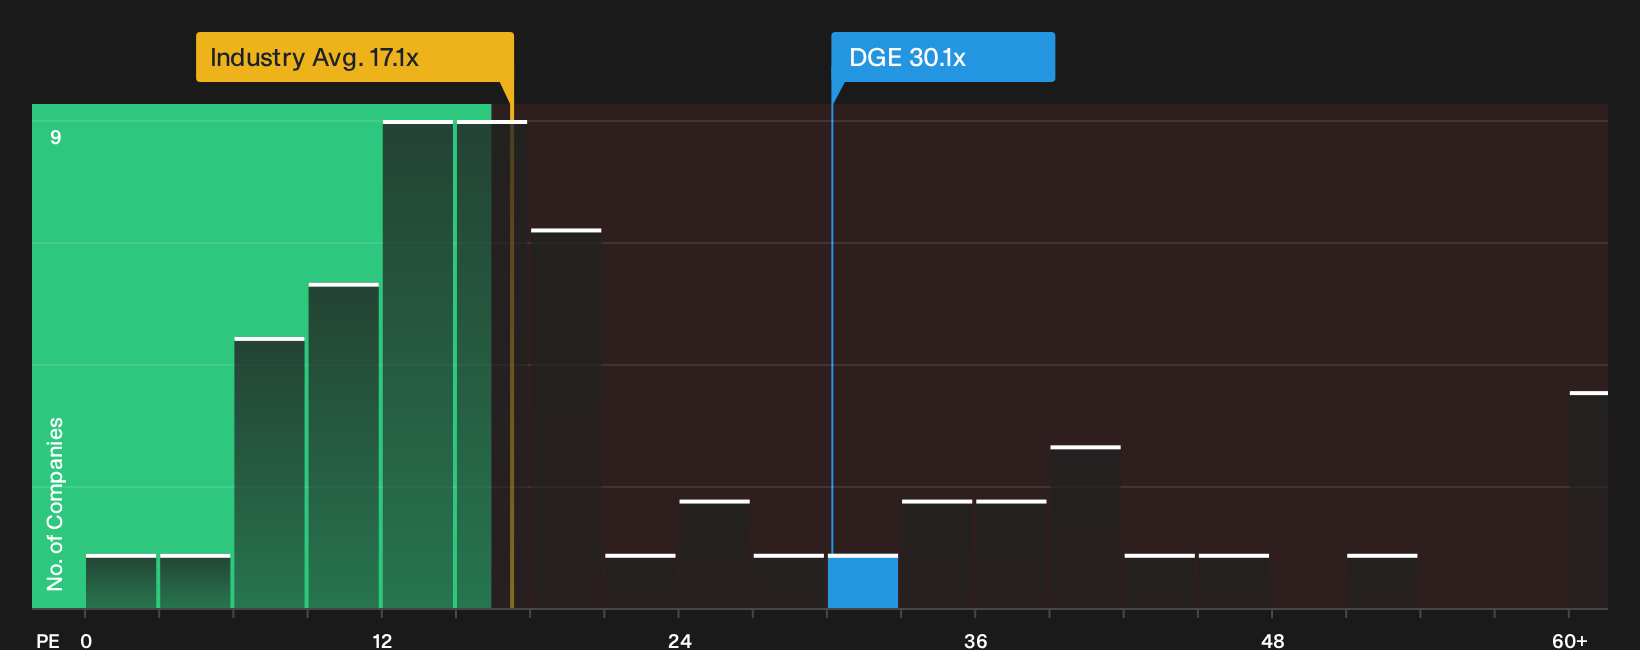
On the flip side of that £20.08 fair value story, Diageo trades on a P/E of 30.1x. That is richer than both its peer average of 24.2x and the European Beverage sector on 17.1x, and even above a fair ratio of 28.3x. This hints at valuation risk if expectations slip. If the premium multiple narrows toward that fair ratio, how comfortable are you with the margin of safety built into your own thesis?
Before leaning too hard on any single metric, it is worth stress testing your assumptions against a fuller valuation breakdown. That includes how Diageo stacks up on earnings quality, debt and cash generation, and where that could leave the multiple if sentiment cools, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Diageo so far. Consider assessing the situation while sentiment is still forming and test the bullish and cautious arguments against the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Diageo?
Do not stop your research at Diageo. Fresh ideas often sit one step away, and skipping them can mean missing the opportunity that fits you better.
- Target steadier compounding potential by scanning companies that combine healthier balance sheets with resilient fundamentals through the list of solid balance sheet and fundamentals (10 results).
- Hunt for mispriced opportunities where quality and valuation still line up by reviewing the 14 high quality undervalued stocks.
- Prioritise resilience and aim for greater peace of mind by focusing on businesses flagged for lower overall risk through the 5 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com