


EN
Marvell Technology (MRVL) Dropped, So What Is Driving Attention Now?
Marvell Technology (MRVL) has been pulled into focus after reports it is in advanced talks to acquire data center optics specialist Lumentum in a potential US$83 billion all-stock transaction focused on AI infrastructure.
The share price reaction has been sharp, with Marvell Technology down about 10% on the day of the latest report and roughly 28% over the past month. Even so, the stock still shows a 90 day share price return of 1.35% and a year to date share price return of 119.71%. Total shareholder returns of 109.87% over one year and very large gains over three and five years point to long term momentum that recent deal concerns and a broader AI hardware selloff have only partially interrupted.
Seize this pullback in Marvell Technology to reassess your AI infrastructure exposure against our hand picked 54 AI infrastructure stocks in the same theme.After a 28% slide and fresh deal headlines hanging over Marvell Technology, the question is simple: Does it make more sense to lean into this reset now or wait for the valuation to cool further before adding exposure?
Most Popular Narrative: 42% Undervalued
On the latest numbers, Marvell Technology closed at $196.40 while the most followed narrative framework points to a fair value of $339.36, using an 11.33% discount rate to assess future cash flows and earnings power.
The expanded commercial agreement with a major hyperscaler, which includes a warrant tied to up to US$120b of cumulative revenue over 6.5 years for TPU attached custom silicon, supports the case that Marvell has visibility on sizeable multi year orders that can underpin future revenue and cash flow.
See why 347 investors see Marvell Technology as 42% undervalued.
Result: Fair Value of $339.36 (UNDERVALUED)
Still, the narrative can unravel quickly if hyperscaler AI spending slows, or if lower-margin custom programs weigh on earnings more than analysts currently expect.
Find out about the key risks to this Marvell Technology narrative.
Another View: Multiples Paint a Hotter Picture
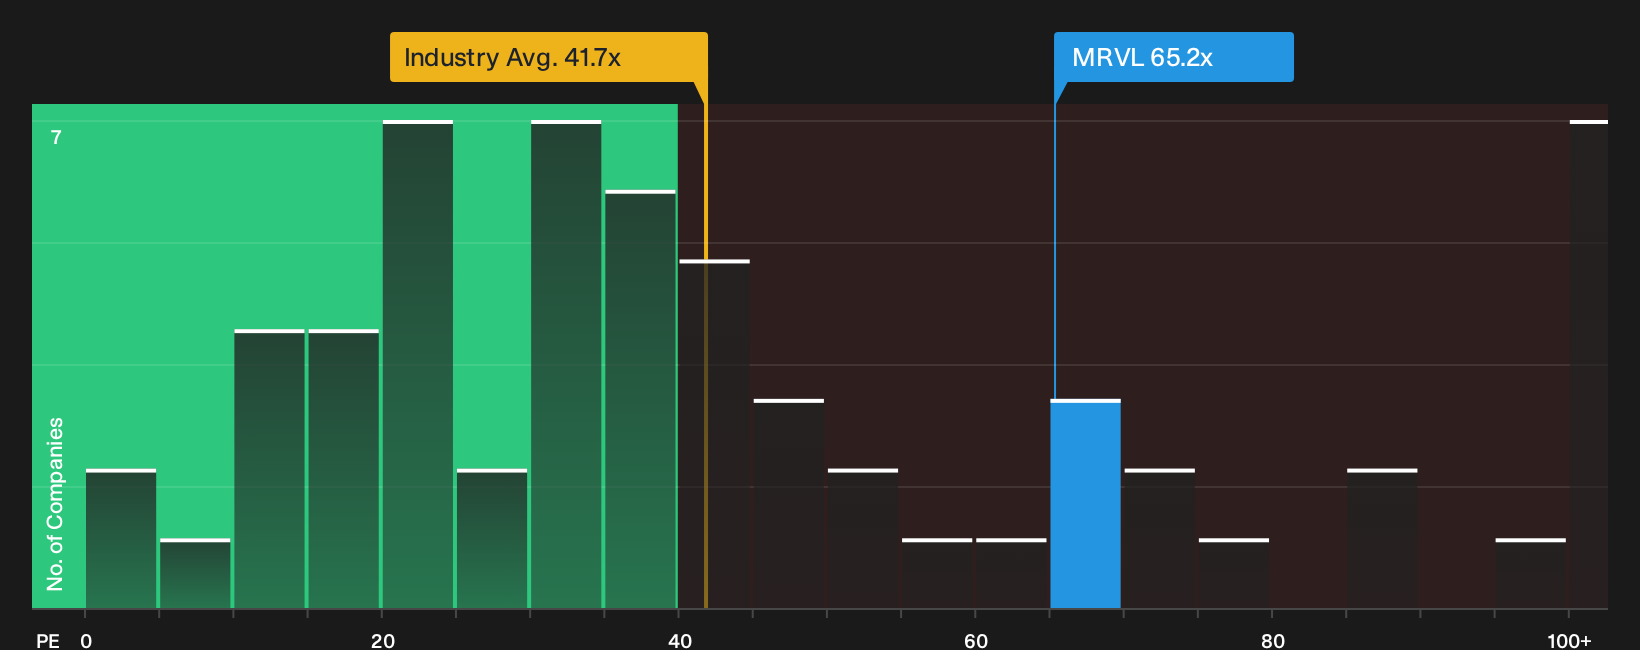
The discounted cash flow work around Marvell Technology points to upside, yet the market is already pricing in a rich earnings multiple. MRVL trades on a P/E of 65.2x, which is well above the US Semiconductor industry at 41.7x, the peer average of 43.2x, and its own fair ratio of 59.5x.
That gap suggests investors are paying a premium for the current AI story. This can magnify downside if expectations ease rather than expand from here. The key question is whether you are comfortable underwriting that extra multiple risk alongside the broader growth case.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism around Marvell Technology sits next to some real concerns. For a clear view, consider both sides using 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Marvell Technology?
If you are reassessing Marvell Technology today, it makes sense to broaden your watchlist with a few focused themes that could complement your AI exposure.
- Target resilient balance sheets by scanning our list of solid balance sheet and fundamentals (24 results) that pair cleaner finances with underlying fundamentals investors often overlook.
- Hunt for mispriced quality and use the 33 high quality undervalued stocks to spot companies where current prices sit below underlying business metrics.
- Pinpoint potential income pillars through the 5 dividend fortresses and find payouts that may help steady overall portfolio returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com