


EN
Why China Literature Fell Even As Sales Rose
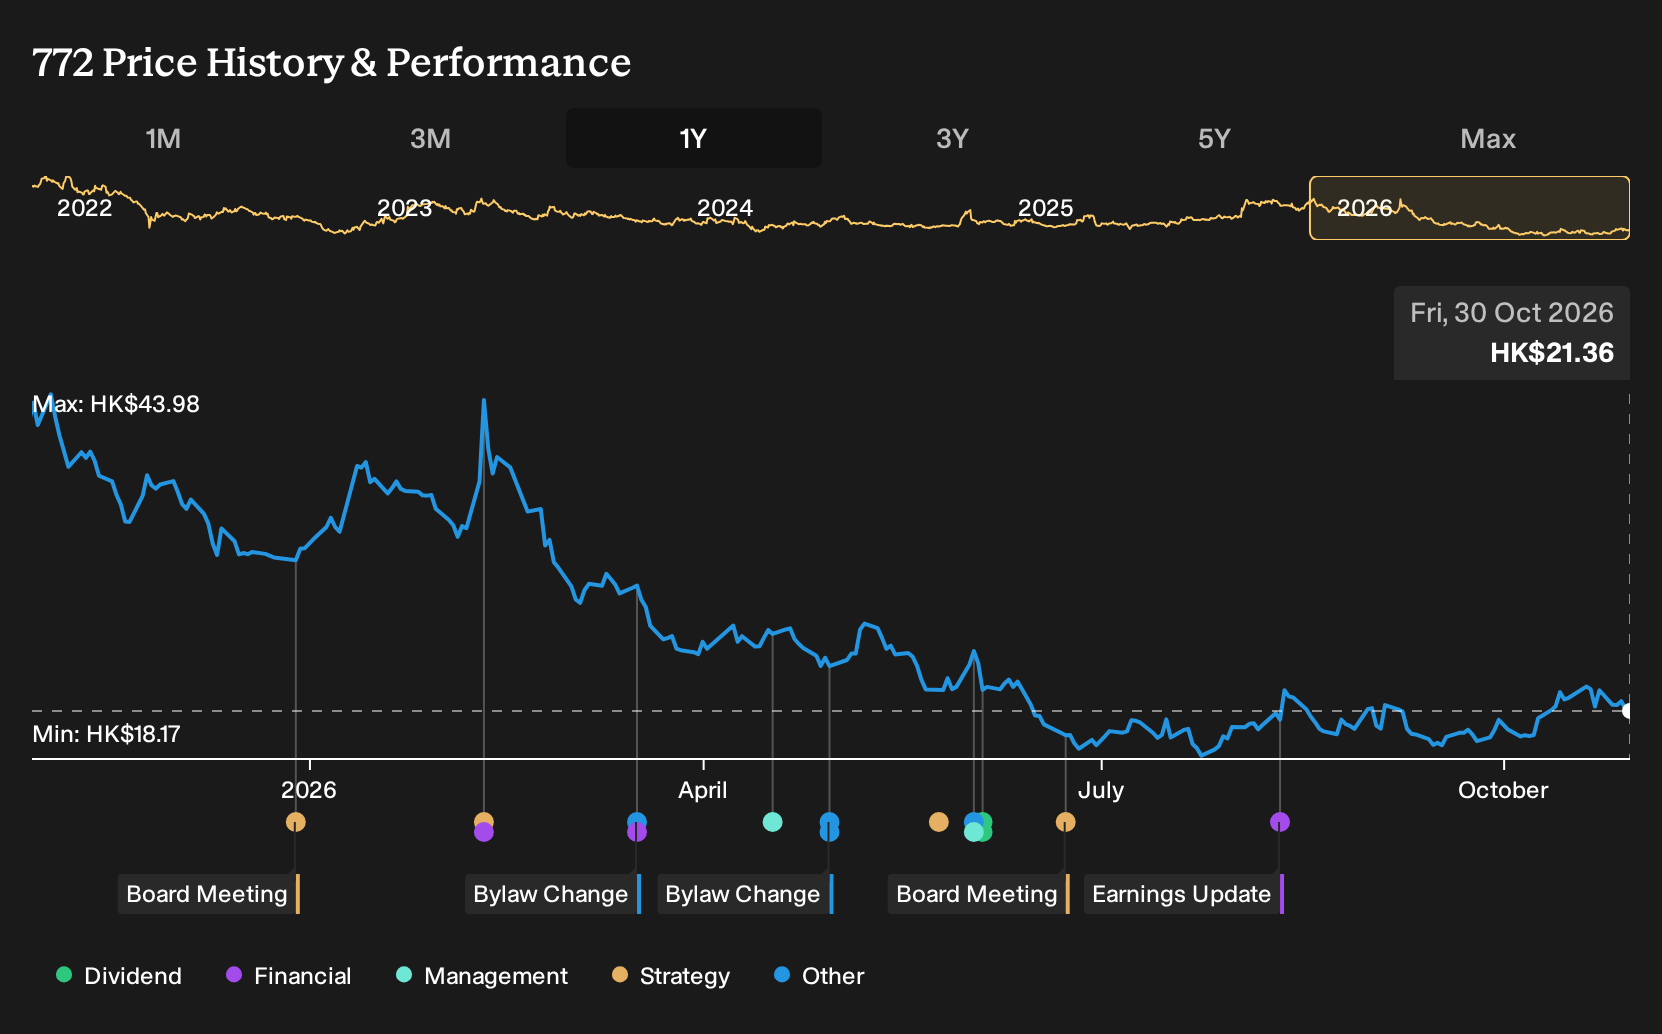
If you had seen bullish and bearish analysts arguing over China Literature in late October 2025 and decided to sit it out, the past year might now look like trouble avoided. Investors who held China Literature over the past year are down 48.9%, including dividends. That drop now sits alongside fresh 2026 interim results that combined higher revenue with a sharply thinner net margin. What assumption in those 2025 forecasts would you interrogate first?
The easy part of this move is behind China Literature. Zero in on 204 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On China Literature
The shares cost HK$43.38 at the start of the period, and China Literature sat between two very different stories about where its online fiction empire could go next.
On the optimistic side, the bullish narrative saw a Fair Value of HK$48.35, a price those assumptions implied rather than a hard fact, built on revenue growing 11.7% a year and profit margins eventually reaching 21.1%.
The bearish view pointed to a Fair Value of HK$26.08, again just the price its story implied, anchored in slower 4.5% revenue growth and concerns over user decline and overreliance on a handful of blockbuster IPs.
What The Results Changed For The China Literature Debate
China Literature’s 2026 interim report showed revenue of C¥3,531.4m for H1 2026 compared with C¥3,190.6m a year earlier, which backed the bulls’ focus on monetising intellectual property like short dramas and merchandise. Net income excluding extra items moved from C¥849.8m to C¥135.4m and the net margin slipped from 26.6% to 3.8%, so the profitability uplift both sides expected remained unproven. Overall, the evidence cut both ways.
The hinge assumption here was margin expansion. If you apply this elsewhere, track whether rising sales are matched by stable or improving net margin, rather than focusing only on eye-catching new products or revenue stories.
What You Would Be Paying For In China Literature Today
China Literature trades at HK$21.36, and the selected Narrative’s Fair Value sits above that level based on its own assumptions rather than hard fact.
The current bull case leans on IP operations, short dramas, AI tools and games taking over from softer online reading. For the fall to look like opportunity rather than warning, a buyer would need confidence that new IP formats can reliably offset pressure on the legacy reading business.
"Management’s decision to tilt traffic toward visual formats, even as online reading MAUs and MPUs soften, indicates an intentional shift of user attention that can deepen monetization of short dramas, AI-animated content and related IP merchandise. This would support a mix shift toward higher IP operations margins."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 32% below our estimate - turns identified fundraising pipelines in tax-efficient products into recurring advisory revenue streams.
- Company 2 - 17% below our estimate - expands clinics and wellness centers to capture demand for preventive and lifestyle care.
- Company 3 - 18% below our estimate - uses cash from a single high margin mine to support phased development of nearby resources.
Three companies from the same screener. Open all 199 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com