


EN
Will Stronger Quarterly Earnings Change Eni Stock's Narrative
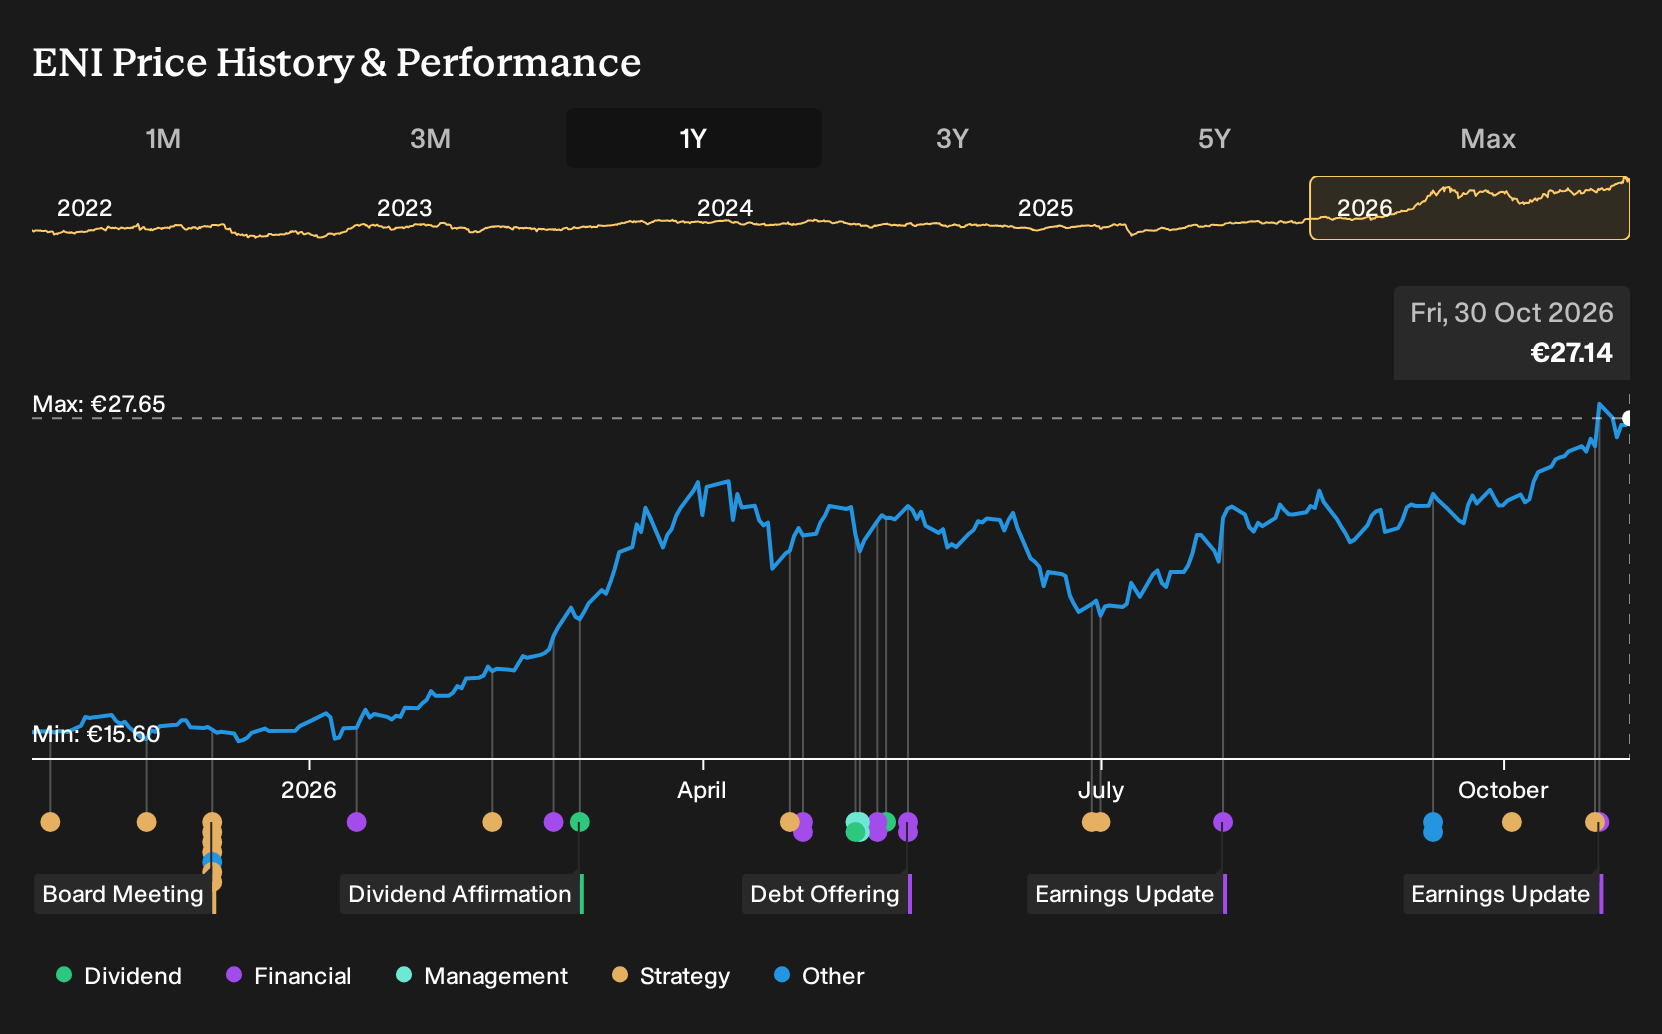
- Eni reported third quarter 2026 revenue of €26,035 million and net income of €3,205 million, with basic earnings per share of €1.09 for the period.
- The group also completed a €1,950 million repurchase of 85,000,000 shares, which reduces the share count and lifts reported earnings per share for investors who remain.
- Investors may now monitor how this change in quarterly net income influences Eni's broader investment narrative for long term holders.
Eni Investment Narrative Recap
To own Eni, you need to be comfortable with a business still anchored in oil and gas while gradually building out LNG, biofuels, renewables and CCS. The big near term swing factor remains execution on large upstream and LNG projects without cost or timing setbacks that could strain the existing €29b 2026 to 2030 CapEx plan.
The latest quarterly numbers show strong profitability and cash generation, which supports that investment story but do not resolve longer term questions around Plenitude funding needs or the loss making Versalis unit. For now, the earnings beat looks helpful, while the structural risk around cash conversion and financing costs is unchanged.
The most relevant update for this earnings print is the completion of the €1,950 million repurchase of 85,000,000 shares. That program directly affects per share metrics, so the jump in basic EPS to €1.09 for the quarter and €2.53 for nine months partly reflects the smaller share count as well as higher net income.
For a holder of Eni stock, this matters because capital allocation is one of the clearer near term factors. If operating cash flow stays close to recent levels, buybacks and dividends can remain an important piece of the equity story. However, any hit to profitability or higher funding costs would quickly limit how much can be returned.
Eni's current earnings are €6.9b, with analysts expecting profits to reach €5.6b by 2029. This implies an earnings decline of €1.3b, alongside forecast revenues of €84.5b in the same year and an assumed 4.6% yearly decrease in revenue.
Uncover why Eni's fair value indicates that earnings expectations are in line with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Eni’s exploration success as the big swing factor. Before this earnings and buyback update, the bullish camp was sketching out revenue near €99.4b and earnings around €8.2b by 2029, compared with the consensus €84.5b and €5.6b. These views were formed before the latest results, so you now get to judge whether today’s profit jump and completed €1,950m repurchase strengthen that upbeat story or push you toward more cautious scenarios.
Explore 3 other Eni fair value estimates, including one that suggests up to 9% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Eni research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Eni. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eni's overall financial health at a glance.
Looking For More Ideas Beyond Eni?
Once you have a view on Eni, it can help to broaden your watchlist with other businesses that fit clear, simple criteria instead of chasing every headline.
- If you care most about balance sheet strength and durability through different cycles, start with our curated list of solid balance sheet and fundamentals (199 results) and focus on companies that keep financial risk contained.
- For investors who want a stronger income focus, use the hand picked 222 dividend fortresses to hunt for payout profiles that might complement Eni in a diversified portfolio.
- When you want to widen the search to opportunities with cleaner fundamentals that markets may be overlooking, run through our targeted 614 high quality undiscovered gems and see which businesses deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com