


EN
AtriCure (ATRC) Stock Looks Overvalued Based On Its Sales
AtriCure has delivered a sharp share price run, and the question now is whether the current US$61.25 level is adequately explained by the revenue it is generating. After that kind of move, investors often want to know if they are paying a sensible price for each dollar of sales.
- The stock has returned 77.3% over the past year, which puts a lot of weight on the idea that its sales profile can support this higher valuation base.
- The business focuses on cardiac surgical devices that depend on procedure volumes and adoption in hospitals, so expectations for future revenue growth and operating leverage matter directly for how much investors might be prepared to pay for its sales today.
- Your read on AtriCure is one view; the desks covering it have another. See what analysts think AtriCure's shares could be worth.
The issue now is whether AtriCure's recent share price performance is appropriately reflected in the value investors are assigning to its sales.
If you are comparing AtriCure with other options for generating revenue today, it can be useful to evaluate it alongside a broader group of 33 high quality undervalued stocks.
Is AtriCure Getting Expensive on Sales?
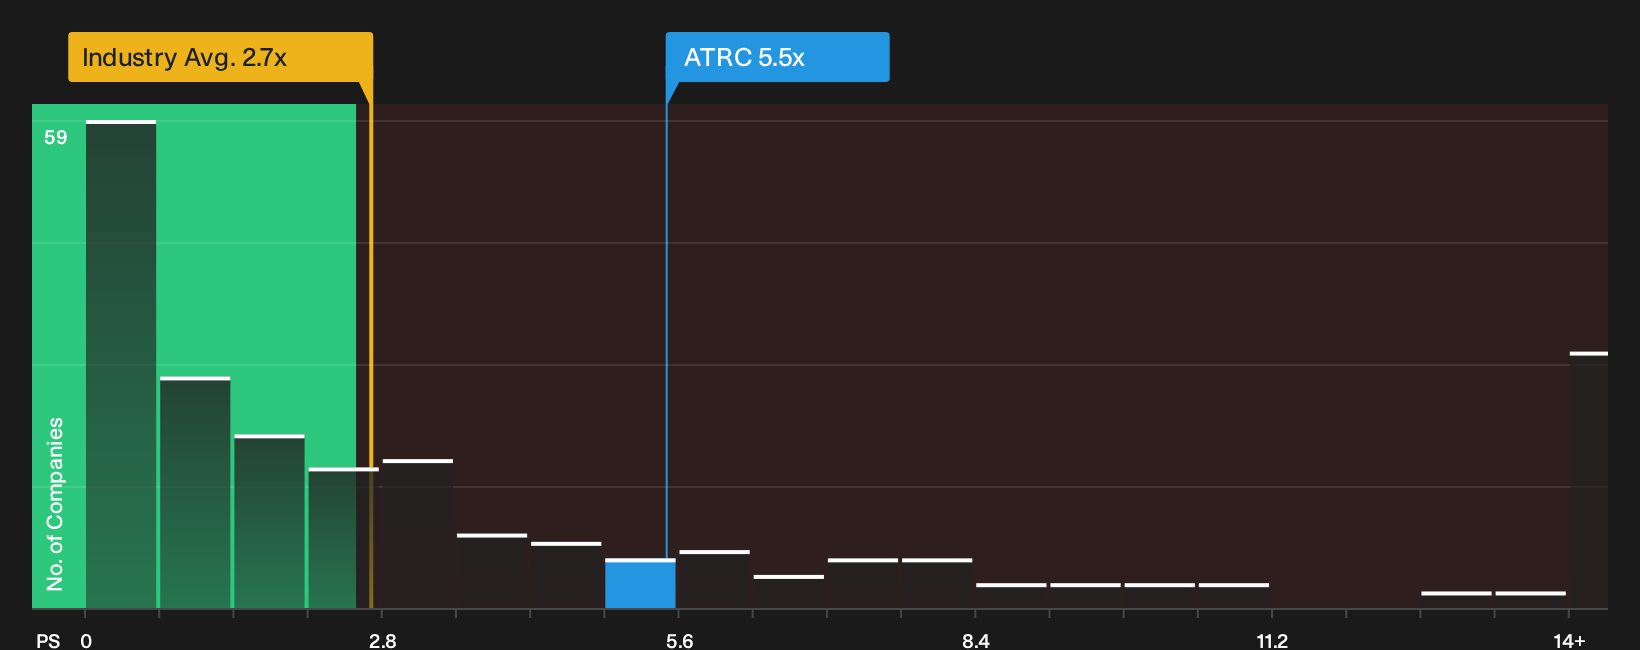
P/S fits AtriCure because investors are essentially paying for the revenue footprint of its cardiac surgery franchise rather than current profits. The stock trades on a P/S ratio of 5.5x, compared with about 2.7x for the broader Medical Equipment industry. That places a clear premium on each dollar of sales the business generates.
Relative to closer peers, the picture is similar. The peer group averages roughly 5.1x P/S, while AtriCure still changes hands at a higher level. On a tailored fair value lens that blends factors such as revenue quality, profitability profile, size and risk, the current P/S sits above where that framework would typically place AtriCure. This points to the shares screening as overvalued on this metric. For anyone tracking whether this gap is justified by the company’s own fundamentals, the detailed model output is a useful next step. Explore the numbers behind AtriCure's P/S valuation.
The AtriCure Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for AtriCure pick up where this valuation puzzle leaves off by spelling out which revenue, margin and earnings paths would need to play out for the stock to be worth materially more or materially less than today’s price. Each one focuses on the assumptions behind its view of fair value so you can line those up against AtriCure's reported results over time on the Community page.
Community views on AtriCure split between those who see under‑appreciated pipeline upside and those who think expectations already run hot.
Bull case: 10% undervalued
"The early placement of the cryoXT probe in about two dozen U.S. amputation accounts with minimal current revenue contribution creates room for a second wave of pain management adoption..."
Discover why this Narrative puts AtriCure at 10% undervalued.
Bear case: 6% overvalued
"The accelerating adoption of minimally invasive PFA (pulsed field ablation) catheter technologies is putting sustained pressure on AtriCure's minimally invasive ablation franchise in the U.S..."
Explore why this Narrative puts AtriCure at 6% overvalued.
AtriCure’s valuation still hinges on one unanswered issue
Price to sales only tells part of the story for AtriCure, because our broader review has picked up specific risk checks that investors may want to weigh before leaning on the valuation alone. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com