


EN
DMG Mori (TSE:6141) Q3 Earnings Put Margin Durability In Focus
DMG Mori just released its Q3 2026 scorecard, and the focus is on earnings power rather than hype. Basic earnings per share came in at ¥36.32, with net income of ¥5,446 million on revenue of ¥145,977 million. That represents a solid profit outcome for a machine tool maker that trades on a relatively high P/E and has reported a trailing net margin of 1.6% over the last year.
The stock closed today at ¥2,736. In the context of that quarterly profit level, any sharp one day move appears less like a reaction to new information and more like a sentiment verdict on whether this margin rebuild is sustainable.
Like the earnings power at DMG Mori but uneasy about a high P/E sitting on a thin 1.6% trailing net margin? Compare this setup with our list of solid balance sheet and fundamentals stocks (21 results) to see businesses where profitability and balance sheet strength line up more cleanly.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): ¥145,977 million vs. ¥111,390 million (up roughly 31% year on year)
- Net Income (Q3 2026 vs. Q3 2025): ¥5,446 million vs. ¥1,892 million (up roughly 188% year on year)
- Basic EPS (Q3 2026 vs. Q3 2025): ¥36.32 per share vs. ¥13.35 per share (up roughly 172% year on year)
- Trailing Net Margin (Last 12 Months vs. Prior Year): 1.6% vs. 1.9% (margin compressed by about 0.3 percentage points)
Earnings only tell part of DMG Mori's story, because cash flows show what money actually comes through the door and supports the business over time. Looking at DMG Mori's cash flows alone, the stock could be a dramatic 48% undervalued.
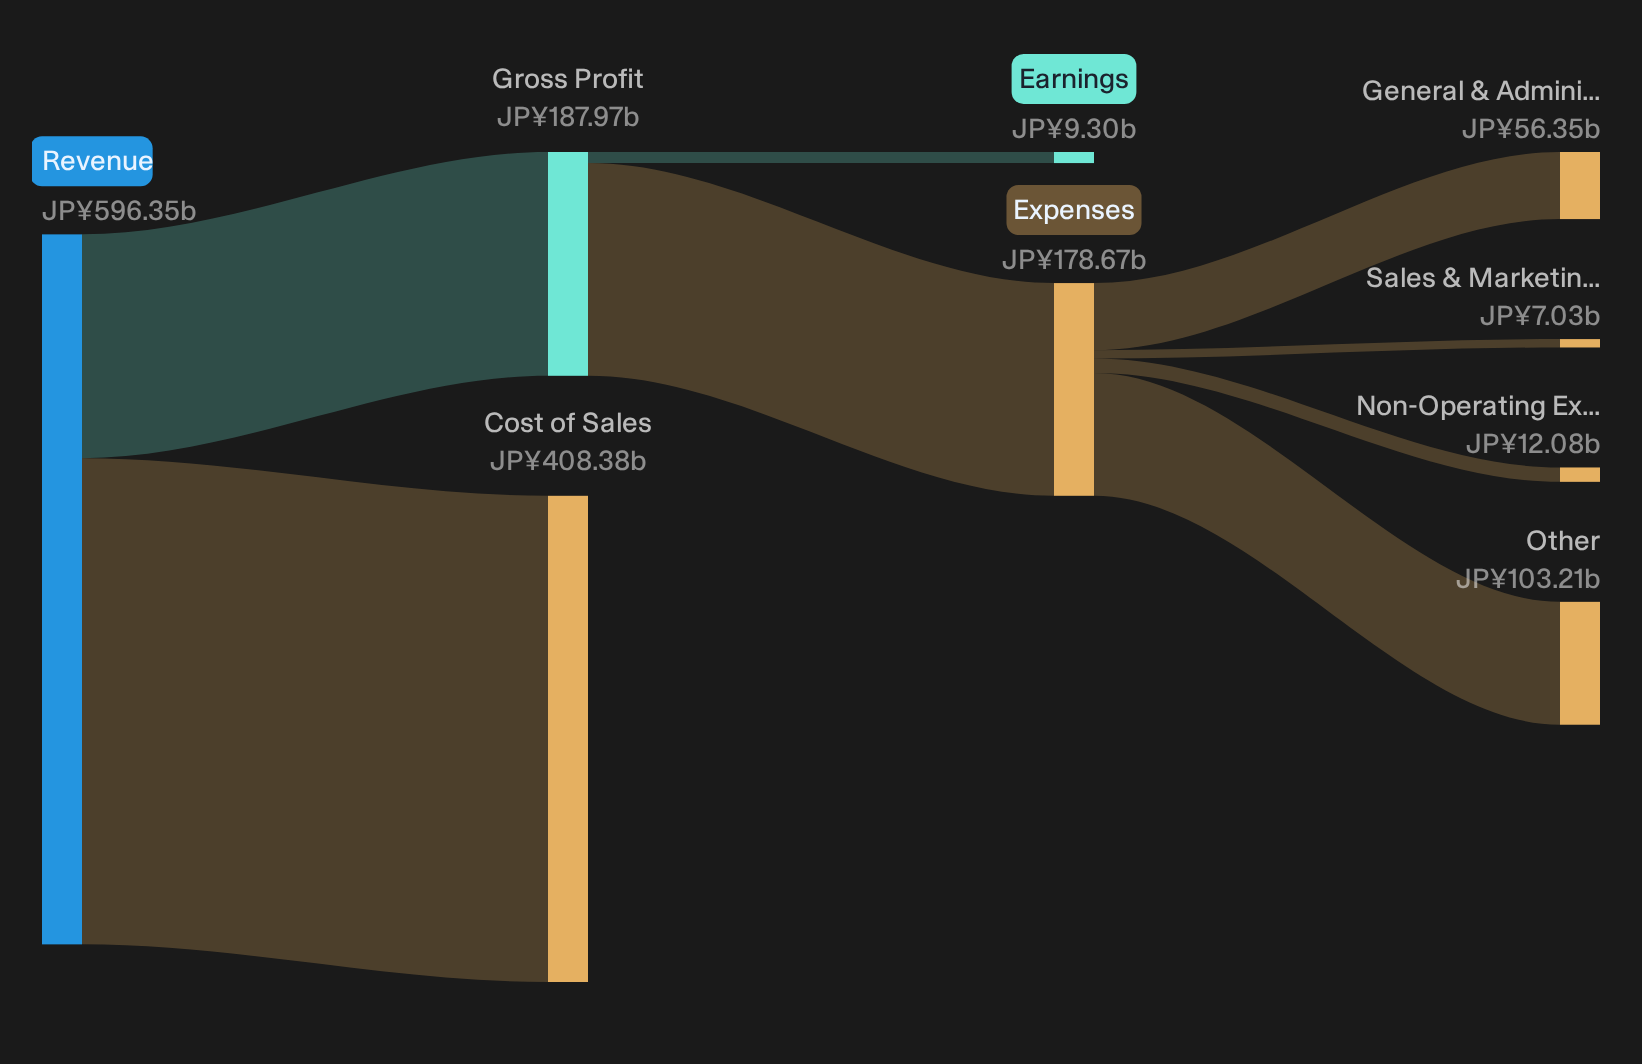
DMG Mori earnings, testing the bullish story
For anyone leaning positive on DMG Mori as an automation driven industrial backbone, the Q3 scorecard gives some support. Revenue of ¥145,977 million and net income of ¥5,446 million point to meaningful earnings power compared with the recent 1.6% trailing net margin. That kind of profitability, alongside higher basic EPS of ¥36.32, lines up with a narrative of a business that can still convert advanced machine tool demand into real cash generation.
DMG Mori risks, thin margins keep pressure on
The cautionary side has not gone away. A 1.6% trailing net margin keeps DMG Mori exposed if the cycle softens or pricing power weakens. Longer term share performance also reflects that tension, with the stock down about 4% over 30 days and about 27% over 90 days. Those moves suggest investors remain unsure that this margin rebuild can stick, so the earnings progress sits alongside ongoing concern about how resilient the model is through industrial swings.
Are analysts convinced DMG Mori can turn this earnings power into a sturdier long term story, or still fading the thin margin risk? Check the consensus price target analysis for DMG Mori.Hunt Quiet Cash Generators Now
DMG Mori just reminded investors how quickly sentiment can shift around a rebuilding margin story. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 37% below our estimate - designs and upgrades air and water systems for retrofitting energy hungry buildings and data centers.
- Company 2 - 33% below our estimate - supplies precision photomasks chip designers use when migrating to new packaging formats and lines.
- Company 3 - 24% below our estimate - sells data and document tools enterprises adopt as manual reporting and form handling strain workflows.
Three companies from the same screener. Open every one of the 16 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com