


EN
Great Portland Estates (LSE:GPE) Soho Square Plan Puts Fair Value Back In Focus
Great Portland Estates redevelopment: what the Soho Square project could mean for investors
Great Portland Estates (LSE:GPE) has set out plans to redevelop its Soho Square Estate in central London, adding around 90,000 sq ft of new office and retail space near Oxford Street.
Recent trading suggests momentum is rebuilding for Great Portland Estates, with a 1-month share price return of 11.07% and a year-to-date share price gain of 8.43%. However, the 5-year total shareholder return is still down 38.15%, which hints that investors remain cautious about the longer-term story.
See how Great Portland Estates compares with other central London focused property players by reviewing our hand picked list of solid balance sheet and fundamentals (10 results) positioned for the next leg of demand in high quality space.
Recent gains hint at renewed faith in Great Portland Estates or a short burst of optimism around the Soho plan. To judge which factor is driving the move, the valuation now needs a closer look.
Price-to-earnings of 8.9x for Great Portland Estates: is it justified?
On a simple yardstick, Great Portland Estates trades on a P/E of 8.9x, which is paired with a last close of £3.41 and a 1-year total return of 5.16%. That combination suggests investors are not paying a premium for recent earnings progress, even with the share price sitting below the average analyst target of £3.86.
The P/E ratio compares the current share price with earnings per share. For a London focused landlord like Great Portland Estates, this metric gives a quick read on how much the market is paying for each pound of profit. A lower figure can reflect either low expectations for future income or simply a cheaper entry point relative to other listed property groups.
Context helps. Management has reported earnings growth of 33.2% over the past year and revenue growth of 4.5% annually. However, the latest 12-month numbers include a one off gain of £122.9m that flatters reported profit. Even allowing for that, the stock is flagged as good value versus peers and the wider Global Office REITs industry, where the average P/E sits at 16.7x. The ratio also screens as attractive against an estimated fair P/E of 12.4x, a level the market could move towards if sentiment on the story improves.
Explore the SWS fair ratio for Great Portland Estates.
Result: Price-to-earnings of 8.9x (UNDERVALUED)
Still, the Soho Square plan relies heavily on central London demand and financing conditions, so weaker occupier appetite or tighter credit could quickly challenge the Great Portland Estates thesis.
Find out about the key risks to this Great Portland Estates narrative.
Another view on Great Portland Estates valuation
The picture shifts once the SWS DCF model is brought into the frame. On that approach, Great Portland Estates at £3.41 is trading well above an estimated future cash flow value of £0.87. Rather than a bargain signal, this points to a stock where a lot already seems priced in. The key question is: what are you really paying for?
Look into how the SWS DCF model arrives at its fair value.
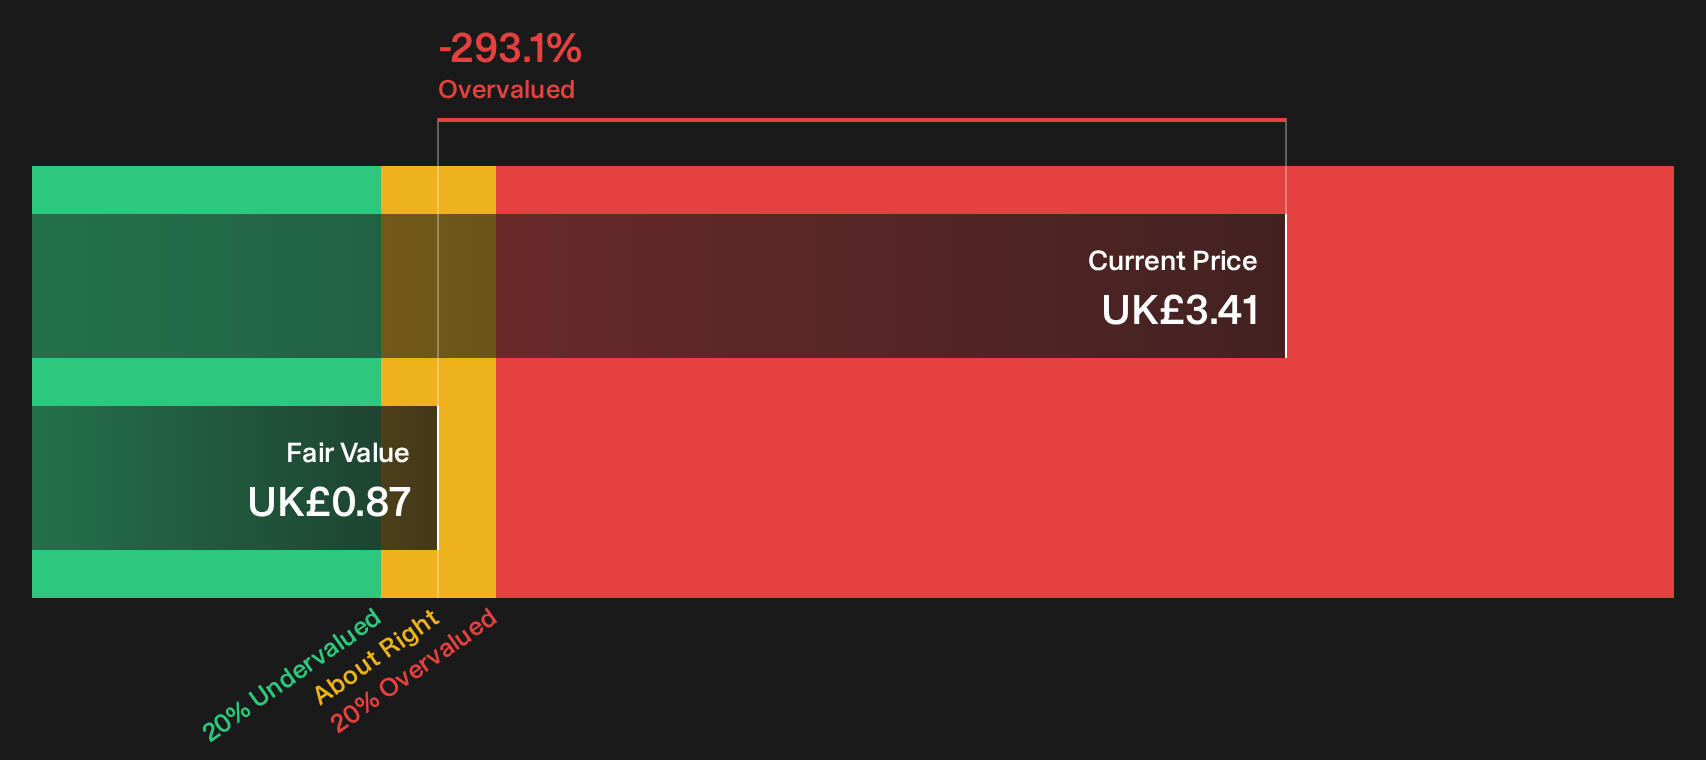
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Great Portland Estates for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Great Portland Estates so far. If you want to move fast and build your own view from the ground up, start with the balance of 4 key rewards and 2 important warning signs
Looking for more Great Portland Estates style investment ideas?
If Great Portland Estates has sharpened your focus on quality and price, do not stop here. Broaden your watchlist now so strong setups do not slip past you.
- Target resilient balance sheets by reviewing a curated list of solid balance sheet and fundamentals (10 results) that filters for companies with financial strength front and center.
- Hunt for quality at a discount through a focused 14 high quality undervalued stocks that highlights opportunities where fundamentals and price appear out of sync.
- Build a cash flow focused watchlist with a 5 dividend fortresses that concentrates on companies offering higher yields with an income tilt.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com