


EN
Markel Group (MKL) Just Raised A Bigger Question
Why Markel Group’s Latest Quarter Caught Investors’ Attention
Markel Group (MKL) surprised the market with better than expected third quarter results, driven by disciplined underwriting, growth in non insurance operations, and a large legacy reserve transfer that reshaped its risk profile.
Markel Group’s share price has climbed 7.6% over the past month, even though the year-to-date share price return is down 12.2%. The 3-year total shareholder return of 39.9% and 5-year total shareholder return of 42.4% point to longer term compounding that investors are weighing against recent earnings volatility and the legacy reserve transfer.
Scan how Markel Group’s mix of underwriting discipline, non insurance earnings and capital moves compares with a hand picked set of 29 resilient stocks with low risk scores.
After a 7.6% jump in a month but a 12.2% decline year to date, Markel Group now asks something simple of you: Does the current valuation still compensate for the legacy risk reshuffle and earnings swings, or has the easy upside already gone?
Most Popular Narrative: 4% Undervalued
The most followed narrative pegs Markel Group’s fair value at $1,956, modestly above the last close of $1,869.82. This leaves a small valuation gap that hinges on how convincingly management executes its reshaped model.
The restructuring and re segmentation of Markel Group’s insurance operations into three divisions and 14 business units, each with a clearly identified P&L leader and tighter expense accountability, continues to be rolled out and is expected to support more disciplined underwriting decisions and leaner cost structures, which should help net margins and adjusted operating income per share over time.
See why 20 investors see Markel Group as 4% undervalued.
Result: Fair Value of $1,956 (UNDERVALUED)
Still, the bullish Markel Group story frays quickly if legacy reserves drag on earnings or if the broad reorganization and AI rollout introduce fresh execution missteps.
Find out about the key risks to this Markel Group narrative.
Another View: What Markel Group’s P/E Is Really Saying
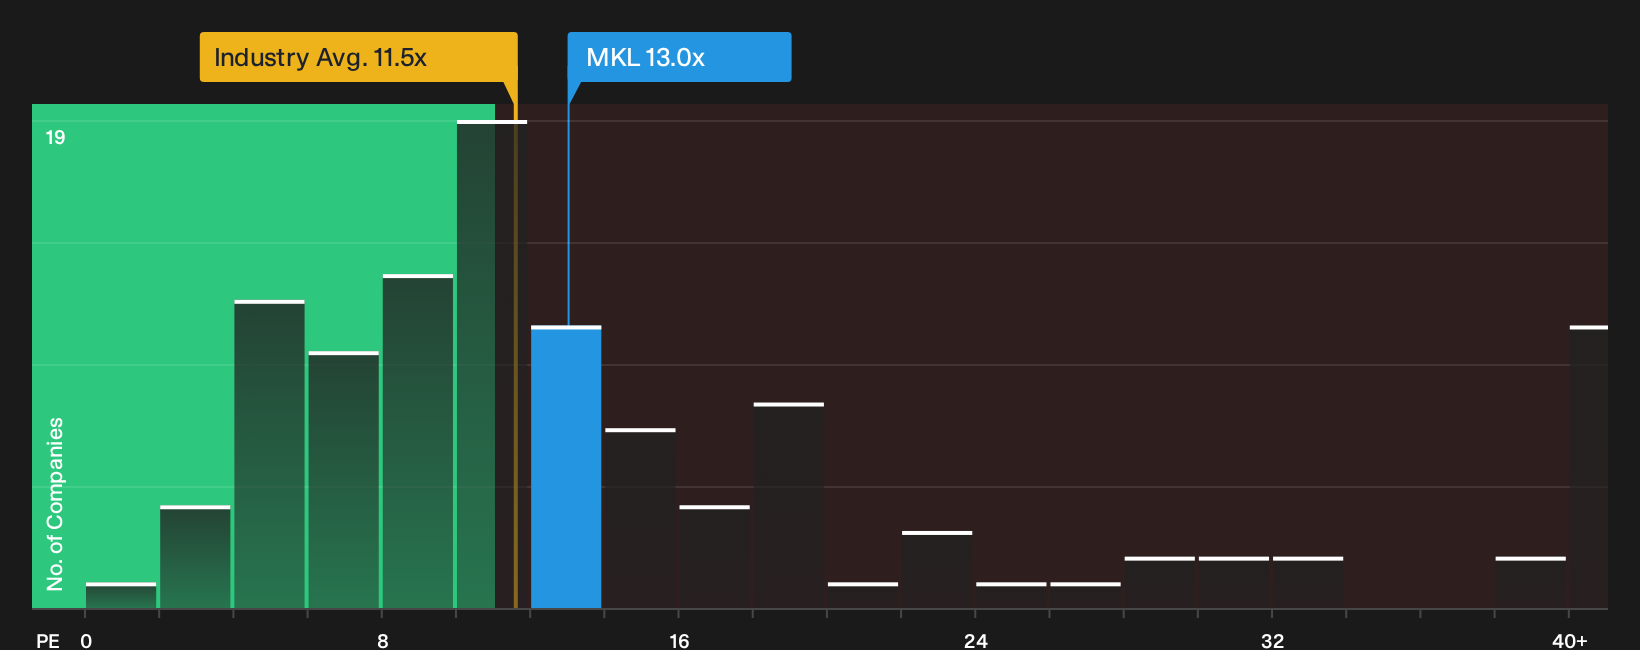
Anchoring only on that $1,956 fair value for Markel Group leaves out an awkward detail. The stock trades on a P/E of 13x, which is richer than both the US Insurance sector at 11.5x and its peer group at 11.9x, and even above a fair ratio of 10x that the market could move toward.
That richer tag can work out if earnings power holds up, but if profit growth stays modest and sector sentiment cools, the gap between 13x and a 10x fair ratio becomes valuation risk rather than a cushion.
To pressure test whether this earnings multiple still makes sense next to industry peers and the fair ratio, take a closer look at the valuation breakdown: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Markel Group still feels unresolved, move fast and stress test the upside drivers that others are watching. To see what those potential upsides look like in one place, start with 1 key reward.
Looking for more investment ideas beyond Markel Group?
If Markel Group has sharpened your focus on quality and valuation, do not stop here. Broaden your watchlist with targeted ideas built from clear criteria.
- Hunt for quality at a discount by scanning a curated pool of 30 high quality undervalued stocks that pair solid fundamentals with pricing that still looks reasonable.
- Build a sturdier core to your portfolio by focusing on balance sheet strength using a focused list of solid balance sheet and fundamentals (24 results).
- Spot overlooked opportunities early by running through a 19 high quality undiscovered gems that highlights companies with substance before wider attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com