


EN
Should Dividend Doubling Require Action From Tsakos Energy Navigation (TEN) Investors?
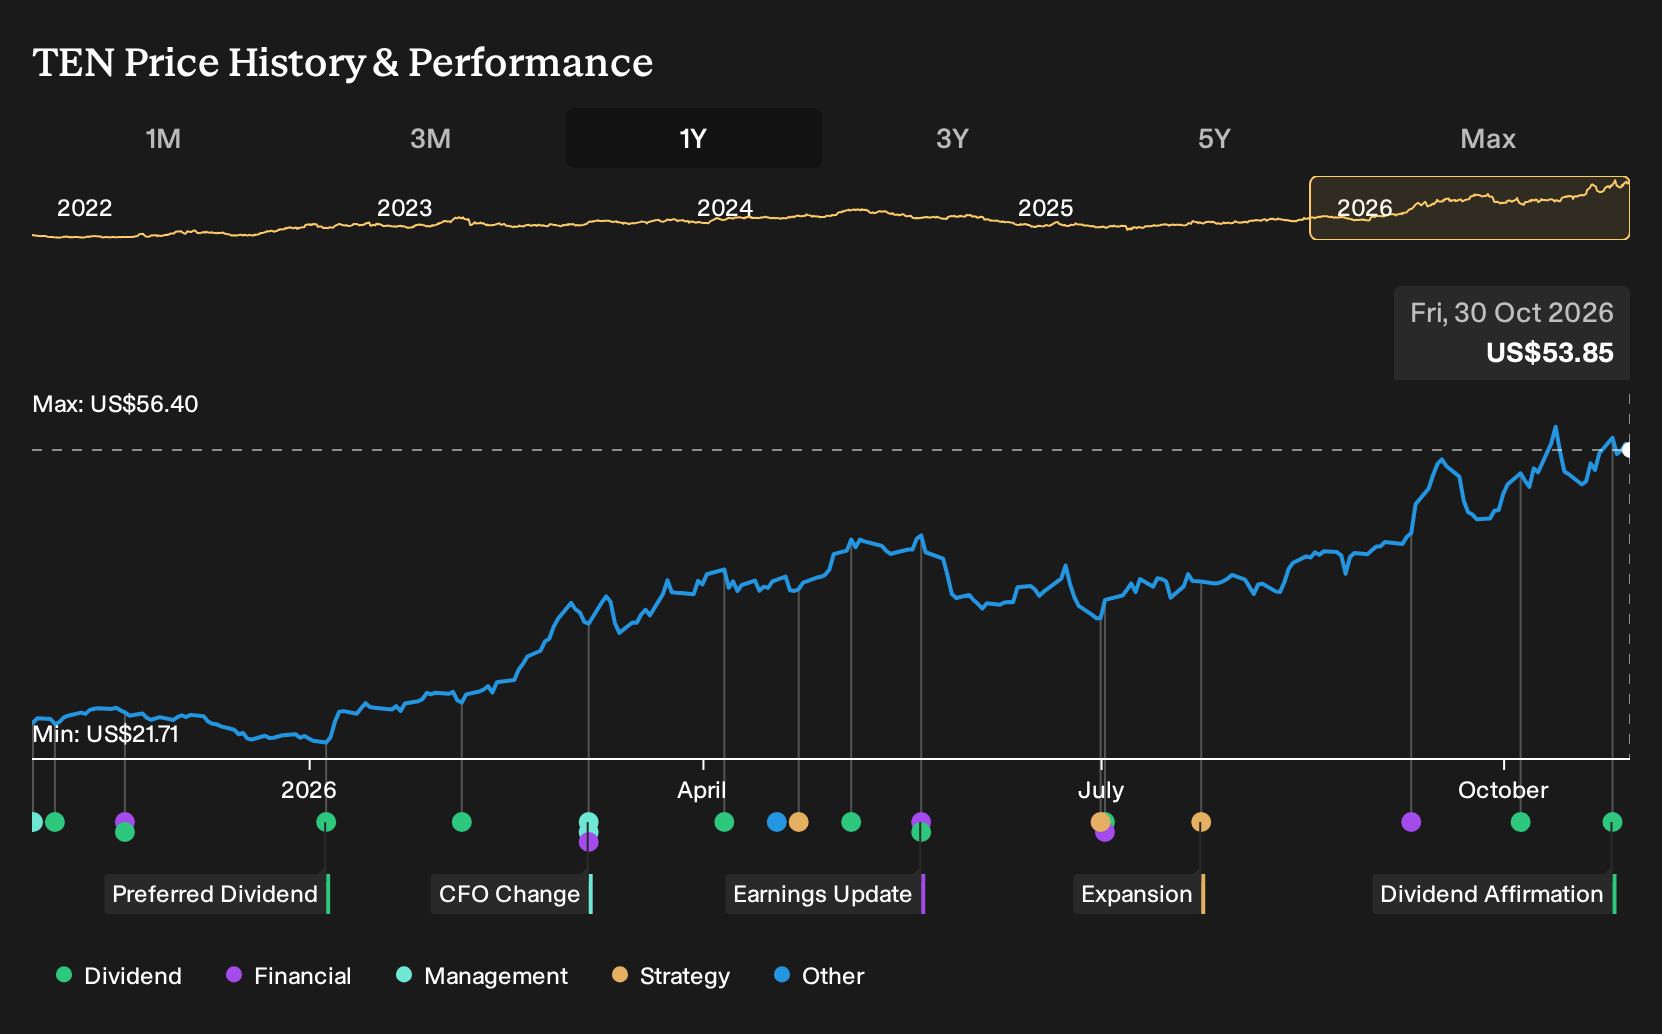
- Tsakos Energy Navigation announced after its recent strategy meeting that it plans to pay a semi-annual dividend of US$1.00 per share in January 2027, with the payout described as a 100% increase versus the first semi-annual dividend for 2026.
- The move signals that Tsakos Energy Navigation is willing to return more cash to common shareholders, even as it commits billions of dollars to a large tanker newbuilding and fleet renewal program.
- We will now assess how Tsakos Energy Navigation's investment narrative is affected by this 100% uplift in the planned semi-annual dividend.
Tsakos Energy Navigation Investment Narrative Recap
To own Tsakos Energy Navigation, you need to be comfortable with a tanker operator that is leaning into a large US$3.1 to 3.2b fleet renewal plan while still being heavily tied to crude and petroleum transport. The thesis hinges on recycling older ships into younger, larger vessels and keeping the mixed charter model working in less supportive freight markets.
The recent decision to lift the first semi annual dividend for 2027 to US$1.00 per share looks more like a capital allocation signal than a change in the near term story. The key swing factor still sits with freight rate conditions versus those sizeable vessel commitments. The main risk remains earnings and revenue forecasts that point to declines over the next three years.
The dividend uplift lines up with earlier commentary that Tsakos Energy Navigation intended to raise the common payout to US$1.60 per share for 2026. Income focused holders now see a clearer bridge between that 2026 goal and the higher semi annual distribution flagged for January 2027, even as free cash flow coverage has been flagged as tight.
That earlier dividend plan was tied to a balance sheet that carries about US$2.0b of debt against an estimated US$4.9b fleet value and US$466 million of cash, along with a revenue backlog of roughly US$3.5 to 3.6b. The higher 2027 payment increases the spotlight on execution of vessel sales, chartering discipline and any decision to redeem high coupon preferred shares.
Tsakos Energy Navigation's current analyst blueprint points to revenue of US$793.0 million and earnings of US$179.9 million by 2029, with that top line expected to decline by 6.2% a year and profits falling by about US$115.4 million from US$295.3 million today.
Uncover why Tsakos Energy Navigation's fair value indicates a 16% potential upside to its current price, a discount that could narrow as sentiment changes.
Exploring Other Perspectives
The most optimistic analysts focus on one big swing factor for Tsakos Energy Navigation. They lean on that bullish view of profit margins almost doubling to 59.8% and earnings reaching about US$585.8 million by 2029, compared with the consensus US$179.9 million. Those expectations predate this 100% dividend uplift, so you should expect opinions to shift and should explore how that reshapes both sets of forecasts.
Explore 3 other Tsakos Energy Navigation fair value estimates, including one that suggests a potential upside of as much as 16% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tsakos Energy Navigation research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Tsakos Energy Navigation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tsakos Energy Navigation's overall financial health at a glance.
Looking for more investment ideas beyond Tsakos Energy Navigation?
If Tsakos Energy Navigation has sharpened your focus on dividends, balance sheets and potential returns, you can broaden your watchlist using the Simply Wall St Screener to compare this story with other listed businesses that fit your income or quality filters.
- For investors who want yield with financial resilience, scan companies that feature list of solid balance sheet and fundamentals (24 results) and see which ones line up with your risk tolerance.
- If value is your priority, look for businesses trading at prices that may be attractive relative to their fundamentals by reviewing the 31 high quality undervalued stocks that might deserve a closer look.
- For readers who like to get in early on underfollowed opportunities, widen your search with a 19 high quality undiscovered gems that could complement or contrast with the Tsakos Energy Navigation thesis.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com