


EN
How Investors Are Reacting To Kimco Realty (KIM) Raised Guidance And Dividend
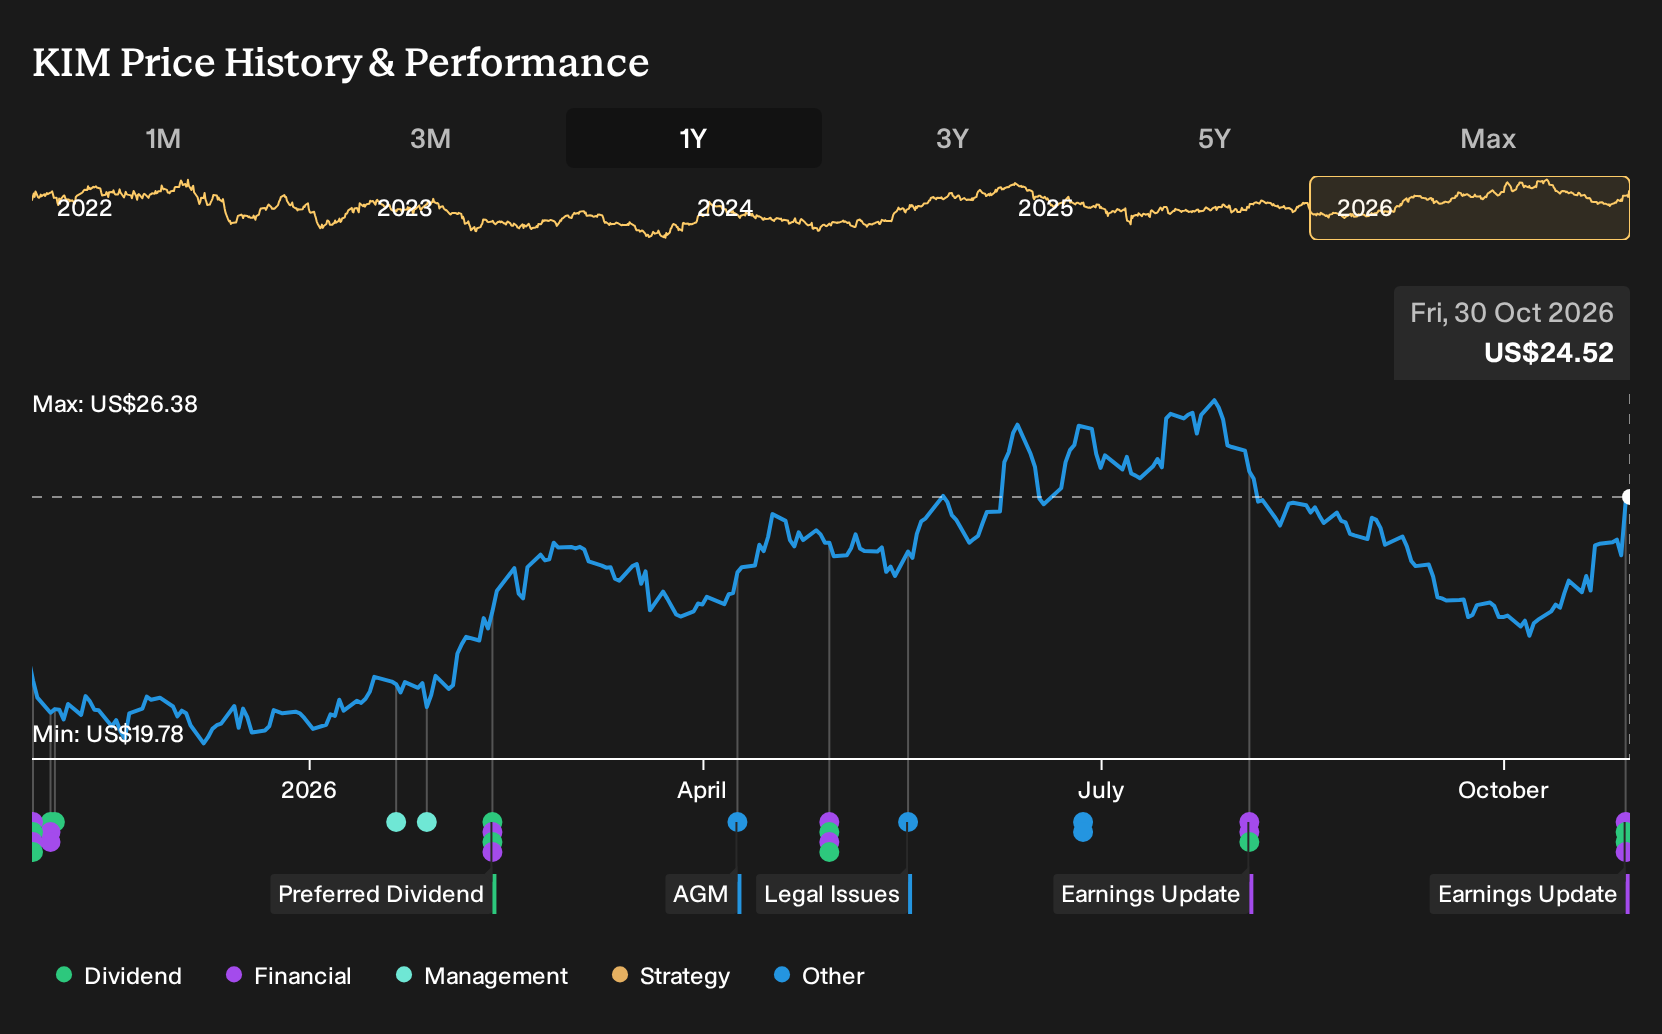
- Kimco Realty reported third quarter 2026 revenue of US$546.15 million and net income of US$279.07 million, raised full year earnings guidance, and approved higher common and preferred dividends, including a US$0.28 per share common payout scheduled for December 18, 2026.
- Beyond headline earnings, Kimco Realty pointed to record occupancy, strong leasing spreads, higher funds from operations and active capital recycling into grocery anchored centers, which all reinforce a focus on necessity retail and balance sheet discipline.
- We will look at how Kimco Realty's raised full year guidance reshapes the investment narrative built around its grocery anchored portfolio.
Kimco Realty Investment Narrative Recap
To own Kimco Realty, you need to buy into a simple idea. Grocery anchored, necessity focused centers can keep drawing consistent tenant demand. That supports occupancy, rents and funds from operations even when sentiment swings. The raised earnings guidance and strong third quarter metrics reinforce that story and keep the signed but not open pipeline central as a short term driver.
The biggest near term worry still sits on the financing and legal side. Higher refinancing costs on 2026 debt and the Target redevelopment lawsuit both threaten margins and tenant relationships more than this quarter helps them. The latest results do not remove those risks. They show the underlying operations holding up.
The common dividend increase to US$0.28 per share, a 7.7% lift from the prior year quarter, is the clearest announcement for income focused holders to consider. It aligns with record occupancy, solid leasing spreads and higher funds from operations, so for many investors it reads less like a surprise and more like a reflection of where the business currently stands.
For catalysts, that higher payout and the reaffirmed preferred dividends matter because they tie directly into how comfortably Kimco Realty can cover cash distributions while refinancing about US$800 million of low coupon debt. If interest costs rise further or the lawsuit escalates, dividend flexibility quickly becomes part of the risk checklist, even with today’s operating strength.
Kimco Realty’s analyst narrative points to forecast revenue of US$2.4b and expected earnings of US$643.9 million by 2029, based on projected yearly revenue growth of 3.3% and an earnings increase of about US$70.1 million from the current US$573.8 million level.
Uncover why Kimco Realty's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster between about US$26.18 and US$33.49 per share, which leaves plenty of room for disagreement on where Kimco Realty should trade. When you set those against refinancing and legal risks on one side, and new grocery anchored projects on the other, you get a wide debate you should explore.
Explore another Kimco Realty fair value estimate, including one that suggests it could be worth just $26.18.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent analysis.
- A great starting point for your Kimco Realty research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Kimco Realty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Kimco Realty's overall financial health at a glance.
Looking for more investment ideas beyond Kimco Realty?
Once you have a view on Kimco Realty, it can help to line it up against other opportunities with different income, risk and valuation profiles by using the Simply Wall St Screener.
- If you want income with fewer surprises, compare Kimco Realty against companies screened for resilience and stability through the 29 resilient stocks with low risk scores.
- If value is your focus, set Kimco Realty beside opportunities in our curated set of 31 high quality undervalued stocks to see how its pricing stacks up.
- If you are hunting for lesser known ideas, widen the search beyond Kimco Realty with a hand picked group of 19 high quality undiscovered gems that combine quality with relatively low visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com