


EN
Why Huntington Bancshares (HBAN) Is Getting Attention Today
Huntington Bancshares (HBAN) just packed several decisions into one date. Third quarter earnings, fresh details on its ongoing share repurchase program, and dividend declarations all hit on October 22, 2026.
Huntington Bancshares shares closed at US$15.78, with a 30 day share price return of 2.94% and a 90 day share price decline of 9.10%, indicating that recent earnings, buybacks and steady dividends are drawing interest even as earlier momentum has cooled.
Scan Huntington Bancshares alongside a hand picked 29 resilient stocks with low risk scores that balance capital returns with resilient financial profiles.
Huntington Bancshares now trades at a discount to both intrinsic estimates and analyst targets after a modest rebound. Is that a pricing error, or is the market applying a fair caution premium to this bank's earnings mix and buybacks?
Most Popular Narrative: 16% Undervalued
At a last close of $15.78 versus a narrative fair value of $18.87, Huntington Bancshares is framed as materially discounted, with that gap tied closely to how well management turns margin pressure into durable fee driven earnings.
The main thing that has to go right is Huntington Bancshares successfully executing its shift toward larger, recurring fee income streams and partnership-driven cost and revenue synergies, while managing ongoing net interest margin pressure.
The current valuation implies that Huntington Bancshares’ lowered 2027 earnings and return targets, along with planned share buybacks and dividend, are being discounted as if the company’s partnership playbook and fee growth may not fully translate into sustained share price upside.
See why 50 investors see Huntington Bancshares as 16% undervalued.
Result: Fair Value of $18.87 (UNDERVALUED)
Still, that undervaluation story can crack if Huntington Bancshares faces more persistent funding costs or if integration complexity blunts the expected fee and cost synergies.
Find out about the key risks to this Huntington Bancshares narrative.
Another View: Huntington Bancshares On Earnings Multiples
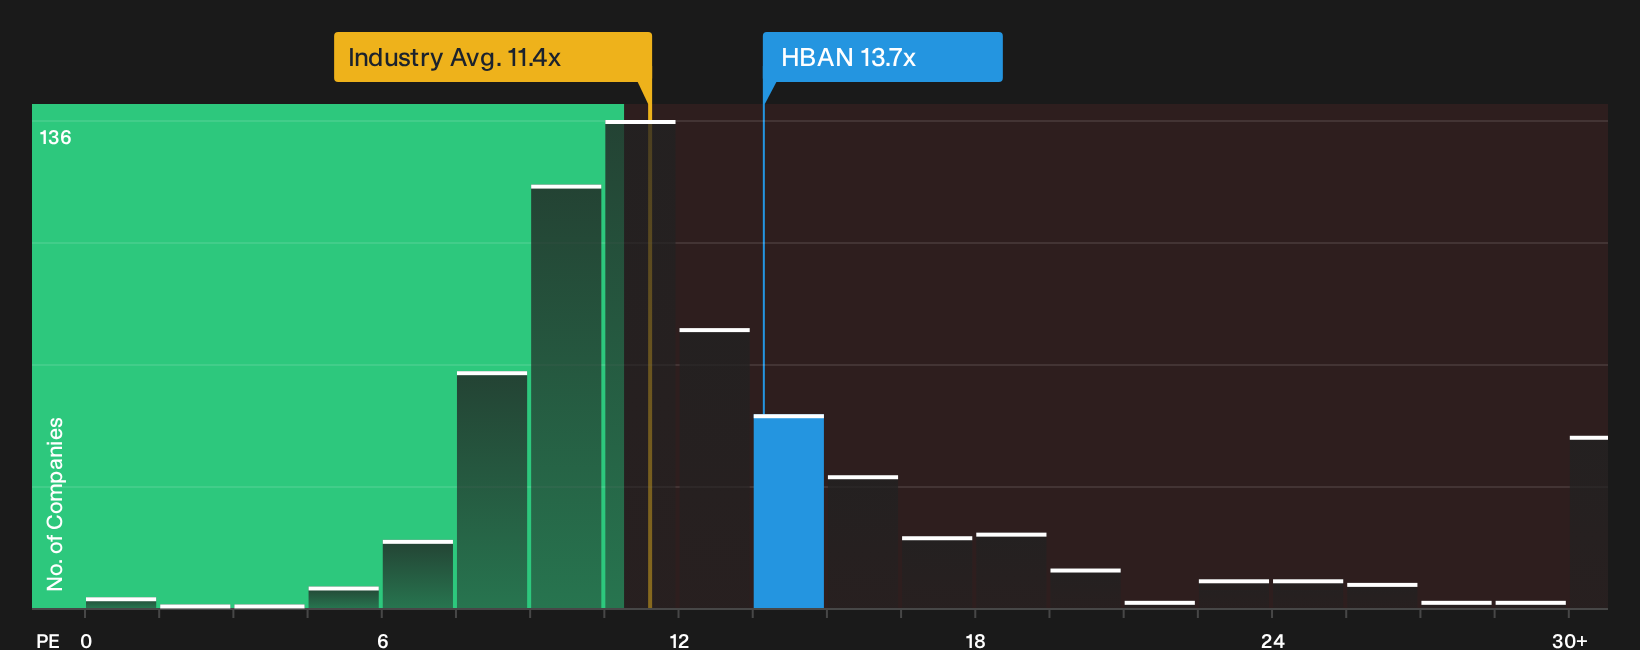
The story looks very different once the spotlight moves from the SWS DCF model to a simple P/E cross check. Huntington Bancshares trades on 13.7x earnings, above both the US Banks industry at 11.3x and its peer average of 11.7x, yet below a fair ratio of 16.5x that the regression points to as a level the multiple could gravitate toward over time. That mix of premium pricing versus sector and discount versus fair ratio leaves investors weighing whether they are paying up for quality or taking on valuation risk for only limited upside.
To see what the numbers say about whether this price gap is worth leaning into, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of caution and optimism around Huntington Bancshares feels finely balanced, treat it as your prompt to move quickly and check the underlying drivers yourself. Weigh both sides of the ledger and stress test your thesis against the 4 key rewards and 1 important warning sign
Looking for more Huntington Bancshares sized investment ideas?
If Huntington Bancshares has sharpened your focus, do not stop here. Use the Simply Wall Street Screener to pressure test fresh ideas before the crowd moves.
- Target resilient cash generators by scanning a curated 30 high quality undervalued stocks that pair quality fundamentals with prices below intrinsic estimates.
- Strengthen your income stream by reviewing a focused 5 dividend fortresses built around higher yield payouts that still clear key financial health checks.
- Protect your capital first by filtering opportunities through a list of solid balance sheet and fundamentals (24 results) that highlights companies with robust finances and room to handle shocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com