


EN
Should Raised Earnings Guidance Require Action From EPR Properties (EPR) Investors?
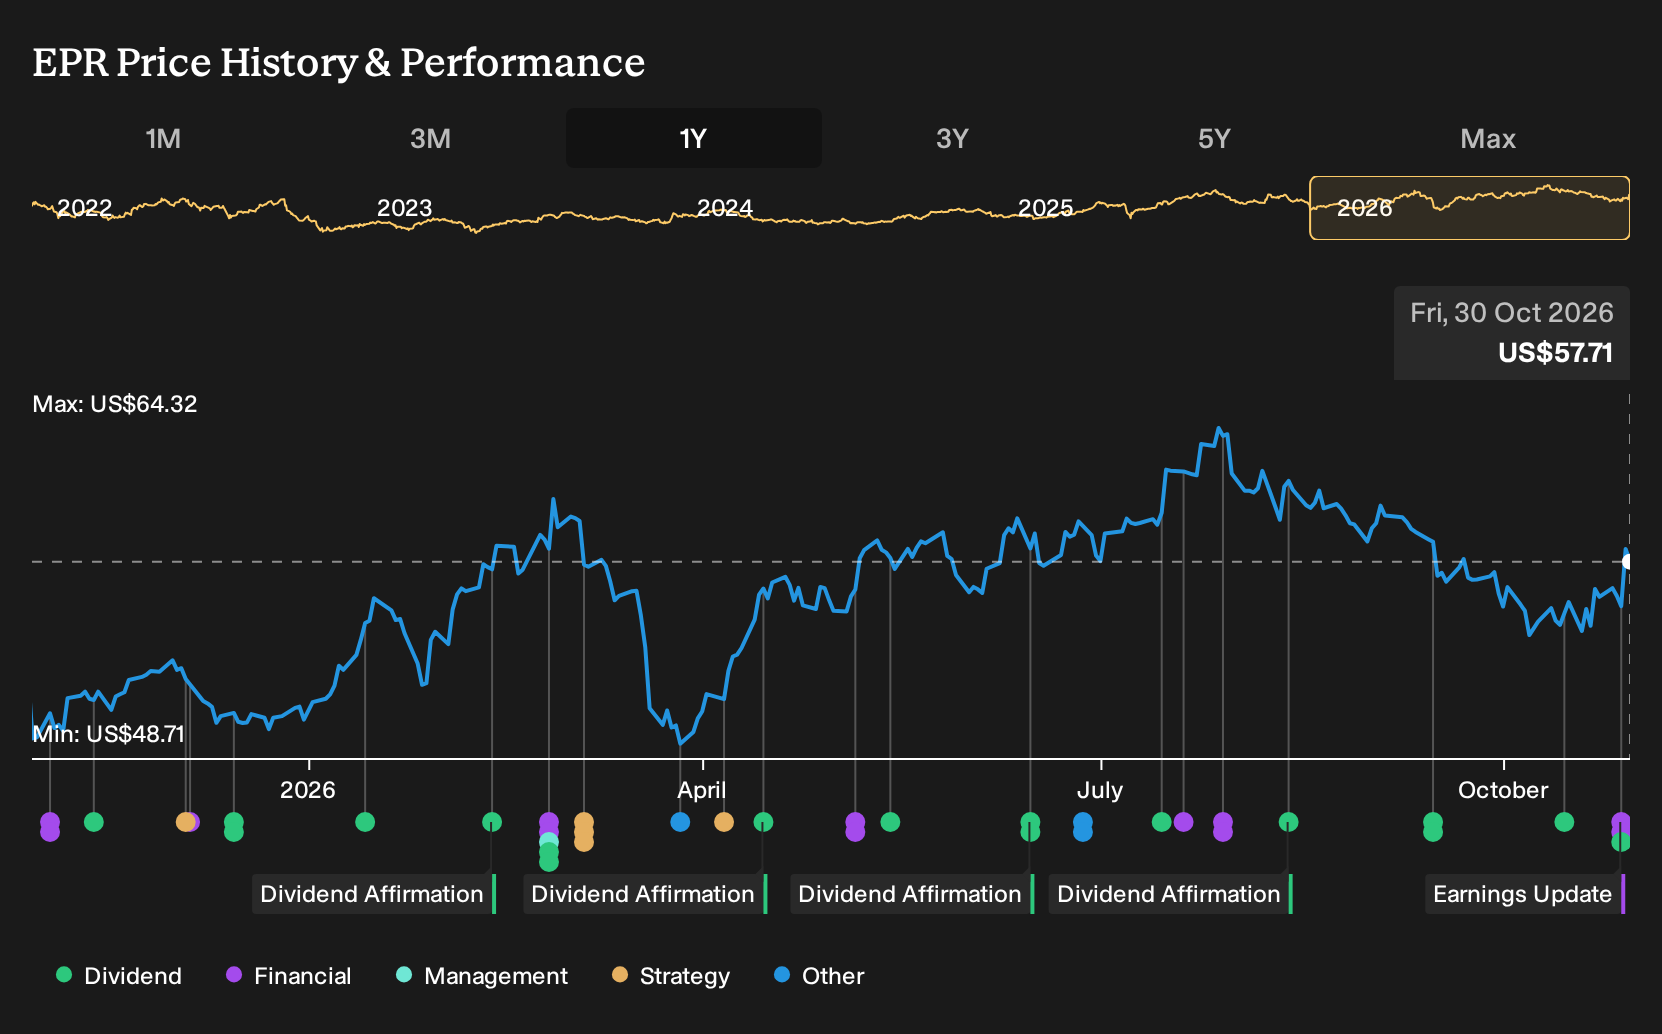
- EPR Properties reported third quarter 2026 results with revenue of US$204.1 million and net income of US$100.12 million, alongside higher full year earnings guidance and a 5.1% increase in the annualized common dividend, all announced in late October 2026.
- The REIT is leaning further into its experiential model, with adjusted FFO growth, a higher 2026 investment range and an expanded mix that now includes live performance venues and fitness properties.
- This article reviews how EPR Properties' raised full year earnings guidance may influence the existing investment narrative around experiential real estate.
EPR Properties Investment Narrative Recap
EPR Properties still asks you to believe that out of home experiences keep earning a healthy share of consumer wallets and that tenants in theaters, attractions and fitness can cover rising occupancy costs. The raised full year earnings guidance and strong third quarter numbers support that thesis in the near term. The most important short term catalyst remains execution on recycling capital into higher quality experiential assets while keeping rent coverage solid.
The biggest risk has not changed. A shift in discretionary spending toward at home options or a weaker economy could pressure cinema and entertainment tenants, undercutting rent collections and net income. Interest coverage also needs watching, given that earnings still have to support debt costs alongside a higher dividend and elevated investment plans.
The raised net income guidance to US$3.41 to US$3.49 per diluted share for 2026 is the announcement that directly ties the latest quarter to the ongoing thesis. It connects stronger current earnings to management’s confidence in cash generation. For you as a shareholder, that guidance frames how much headroom EPR Properties sees for both reinvestment and distributions.
That higher range also interacts with the 2026 investment budget of US$675m to US$725m and the new mix that includes live performance and fitness properties. Execution risk grows as capital deployment scales, since underwriting needs to keep rent coverage healthy across more experiential categories. The uplift in guidance does not remove exposure to an economic downturn or shifting entertainment habits. It does give you fresher data on how the business is tracking against those catalysts and risks right now.
EPR Properties' current narrative points to forecast revenue of US$902.3 million and projected earnings of US$277.7 million by 2029. This assumes yearly revenue growth of 6.9% and an earnings increase of about US$38.6 million from US$239.1 million today, based on current consensus estimates.
Uncover why EPR Properties' fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community stretch from about US$64.68 to US$125.43, a huge gap that shows how differently people can view EPR Properties. Stronger earnings, higher guidance and a bigger dividend pull some toward optimism, while theater exposure and recession risk keep others cautious. Explore those viewpoints directly.
Explore another EPR Properties fair value estimate, including one that suggests as much as 117% potential upside relative to the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and instincts.
- A great starting point for your EPR Properties research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for EPR Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review EPR Properties' overall financial position at a glance.
Looking For More Ideas Beyond EPR Properties?
If the EPR Properties story has you thinking about how to balance income, quality and risk across your portfolio, the Simply Wall St Screener can help you quickly surface other REITs and equities that fit your preferences.
- For investors who want a combination of resilience and lower volatility, take a look at 29 resilient stocks with low risk scores that may help steady your portfolio through different market conditions.
- If high quality businesses with room to rerate appeal to you, consider using the screener built around 30 high quality undervalued stocks that match solid fundamentals with attractive pricing.
- When capital preservation and financial strength sit at the top of your checklist, filter for companies in the list of solid balance sheet and fundamentals (24 results) to see which ones pass a tougher balance sheet test.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com