


EN
Did Earnings Beat Just Shift OceanFirst Financial's (OCFC) Investment Narrative?
- OceanFirst Financial reported third quarter 2026 results that included US$172.12 million of net interest income and US$16.46 million of net income, alongside US$1.46 million of net loan charge offs.
- The company paired higher reported net loan charge offs with adjusted earnings and revenue that were above analyst expectations, supported by cost savings and scale benefits from the Flushing integration.
- We will examine how OceanFirst Financial's investment narrative is affected by the adjusted earnings beat related to the Flushing integration.
Scan how OceanFirst Financial stacks up on credit quality and earnings power beside other regional lenders by reviewing the hand picked 29 resilient stocks with low risk scores now shaping the sector conversation.
OceanFirst Financial Investment Narrative Recap
For OceanFirst Financial, the big picture centers on whether the enlarged franchise from Flushing, the C&I build out, and balance sheet reshaping can produce higher quality earnings even as reported profit looks messy. The recent quarter fits that story, with stronger adjusted performance alongside weaker GAAP metrics and a heavier one off impact.
The key short term catalyst remains clean execution on Flushing integration and cost savings while holding credit steady. Net loan charge offs of US$1.46 million and lower reported earnings keep credit trends and margin pressure in focus as the main risk, particularly with expectations of strong future earnings growth already embedded in the narrative.
The most relevant update tied to this story is the third quarter 2026 earnings release. Net interest income of US$172.12 million and net income of US$16.46 million, together with US$1.46 million of net loan charge offs, provide a current snapshot of how OceanFirst Financial is absorbing Flushing and the earlier balance sheet actions.
Those figures sit against a nine month picture where net income of US$33.94 million is lower than the prior period and profit margins are described as weaker than last year. For an investor watching catalysts, that mix points to an execution race, with integration benefits and C&I growth on one side and margin compression, dilution and credit costs on the other.
OceanFirst Financial's current narrative centers on analysts expecting revenue of US$988.3 million and earnings of US$385.5 million by 2029. This outlook is built on a 32.2% yearly revenue growth rate and an increase in earnings of about US$337.6 million from US$47.9 million today.
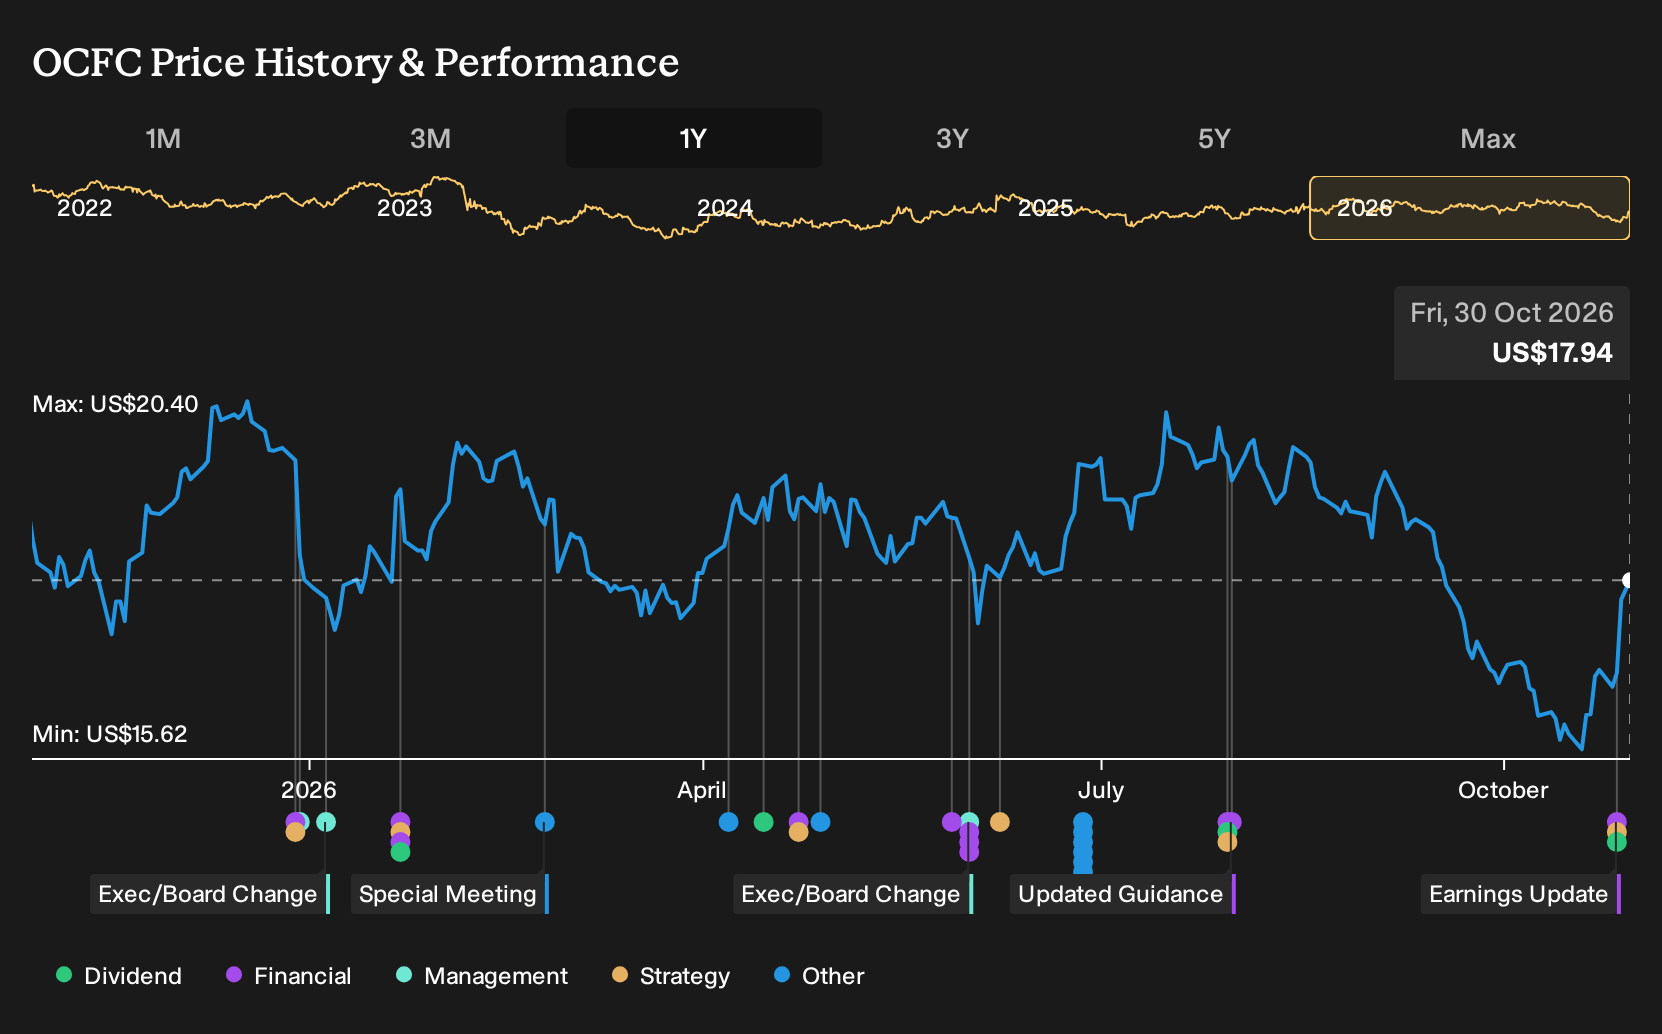
Uncover why OceanFirst Financial's fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster in a tight band between about US$21.42 and US$23.65, which shows how even a small group of retail views on OceanFirst Financial can diverge. When you set those pre news opinions against rising net charge offs and softer reported earnings, you can see why it pays to weigh multiple viewpoints before deciding how this bank fits your portfolio.
Explore 2 other OceanFirst Financial fair value estimates, including one that suggests up to 32% potential upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your OceanFirst Financial research is our analysis highlighting 2 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for OceanFirst Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OceanFirst Financial's overall financial health at a glance.
Looking for more OceanFirst Financial sized investment ideas?
If the OceanFirst Financial story has you rethinking where you want bank exposure, broaden the search and pressure test your thesis against a wider field of listed companies using the Simply Wall St Screener.
- If capital preservation is high on your list, start with a shortlist of companies that currently carry lower risk scores by reviewing the 29 resilient stocks with low risk scores.
- For readers who care most about balance sheet strength and fundamentals, scan a list of solid balance sheet and fundamentals (24 results) that may better match your comfort level with leverage and liquidity.
- If you are hunting for potential mispricings backed by solid business quality, sift through a 30 high quality undervalued stocks that could offer a different risk reward profile to regional lenders.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com