


EN
Missed Eurofins Scientific's Rally? Here's What Holders Saw
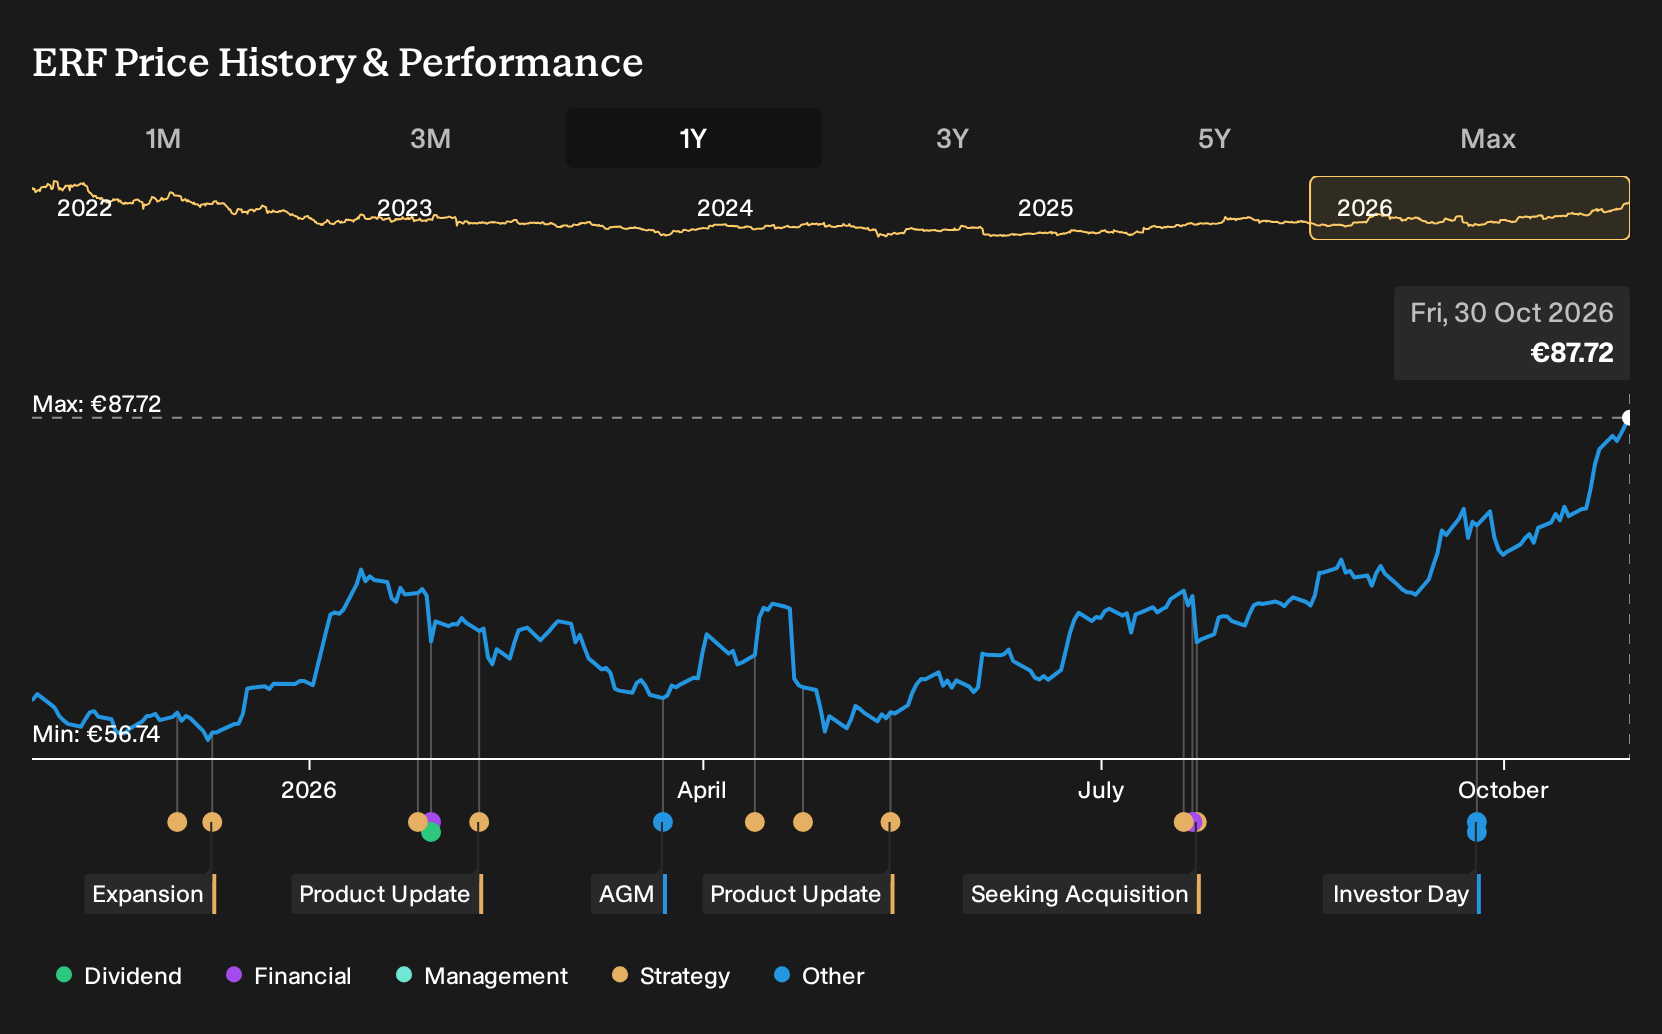
If Eurofins Scientific sat on a watchlist instead of in a portfolio over the past year, the missed gain may feel uncomfortable. For Eurofins Scientific shareholders, the return over the past year was 45.2%, including dividends. That outcome now sits alongside fresh headlines about stronger margins, active buybacks and more deals in life sciences testing, but what could have helped you see potential earlier, based only on the 2025 bet that heavy digitalization and automation spending would actually pay off in routine lab work?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Eurofins Scientific has already moved. Pinpoint other ways to investigate the theme among 125 healthcare AI stocks.
The Two Eurofins Scientific Stories Investors Had To Hold In Their Heads
The shares cost €60.62 at the start of the period, so anyone looking at Eurofins Scientific then had to decide which future felt more plausible.
The bullish Narrative put Fair Value at €63.93, about 5% above the start price, and leaned on heavy spending on automation, digitalization and the hub and spoke lab network, with the expectation that these projects would lift efficiency and margins over time.
The bearish view pointed to Fair Value of €46 and focused on the risk that automation, insourcing and tighter regulation would pressure traditional lab work, weaken pricing, and leave recently acquired assets and new infrastructure earning less than hoped.
What The Results Changed For The Eurofins Scientific Thesis
Eurofins Scientific’s H1 2026 report showed revenue at €3,701.4m and net income at €272.8m, with net margin moving from 6.1% to 7.4%. That margin improvement lined up with the bullish view that heavy digitalization and lab infrastructure spend could lift profitability. Slower organic expansion and soft biopharma conditions, flagged in later 2026 updates, kept the cautious story alive. Overall, the evidence cut both ways.
The key assumption here was that automation and the hub and spoke network would show up in wider margins. When you look at another lab or services stock, track whether reported net margin and cash conversion actually move after big capex programs, not just whether revenue grows.
What Eurofins Scientific’s Price Already Asks You To Believe
Eurofins Scientific now trades at €87.72. The selected Narrative’s Fair Value sits below that level and argues that the current quote leans heavily on already high profitability, strong free cash flow and sizeable buybacks.
To pay today’s price, you would need to assume that organic expansion re accelerates and that margin gains stick. The Narrative then asks how sub 3% organic growth and integration drag in areas like SYNLAB Spain affect that assumption.
"Although Eurofins Scientific is reporting high EBITDA margins and strong EPS and free cash flow, organic revenue growth remained below 3% in both Q1 and H1 2026. If biopharma and some diagnostics and genomics activities continue to weigh on volumes, the current profitability profile may rest on a stagnant top line that limits long term earnings expansion."
The price and this Narrative do not agree. → Uncover what this Narrative says Eurofins Scientific is actually worth
Another Way To Read Eurofins
Watching Eurofins, you kept circling one idea. Chronic disease quietly shapes demand for lab work.
Elsewhere in healthcare, a different business leans into that same pressure. It develops medicines for diabetes, obesity and related conditions.
Those treatments can alter how often patients see doctors and which tests matter. They do not replace lab work, they reconfigure the choices around it.
If drug pipelines redirect some chronic disease burden, attention turns to that treatment chain. Where might shifting routines leave this anonymous lab specialist most exposed?
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 16% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com