


EN
Learn Why The Bull Case For OSI Systems (OSIS) Could Change Following Record First Quarter Results
- OSI Systems reported first quarter fiscal 2027 revenue of US$403.47 million and net income of US$24.57 million, with basic EPS from continuing operations of US$1.55 and diluted EPS of US$1.51, and management reaffirmed a focus on organic investment, selective acquisitions and balance sheet strength.
- Management framed acquisitions as optional rather than essential, emphasizing that any deal must extend OSI Systems' momentum by deepening market penetration or adding complementary sectors, while the existing US$2.1b backlog and multi year U.S. government contracts support the current operating plan.
- We will now look at how OSI Systems' record first quarter and raised non GAAP EPS guidance could reshape the existing investment narrative.
OSI Systems Investment Narrative Recap
To own OSI Systems, you need to believe the business can convert its record US$2.1b backlog and multi year contracts into steadier revenue and cash flow, while lifting the mix of higher margin services. The record first quarter and higher non GAAP EPS guidance support that thesis, but margin compression keeps execution in focus.
Right now, the key short term swing factor is how efficiently OSI Systems delivers large security and RF projects without further squeeze on profitability. The biggest risk remains contract mix and geographic disruption, since any fresh delays or weaker Security demand could slow backlog conversion. The latest quarter does not remove that risk.
The clearest announcement to watch is the raised fiscal 2027 non GAAP EPS guidance that accompanied the Q1 print. Management kept revenue guidance unchanged and still expects free cash flow to exceed net income. This keeps attention on operating discipline, service intensity and working capital rather than pure top line momentum.
For catalysts, those higher earnings expectations sit on top of the roughly US$2.1b order book, including the homeland defense radar work and the two U.S. Customs and Border Protection IDIQ contracts. Any acceleration in converting those awards into revenue and recurring service streams could support the updated EPS range, while execution slipups would work against it.
OSI Systems' narrative projects US$2.2b revenue and US$229.2 million earnings by 2029. This assumes 6.9% yearly revenue growth and an earnings increase of about US$74.5 million from US$154.7 million today.
Uncover why OSI Systems' fair value indicates a 40% potential upside to its current price that could narrow quickly.
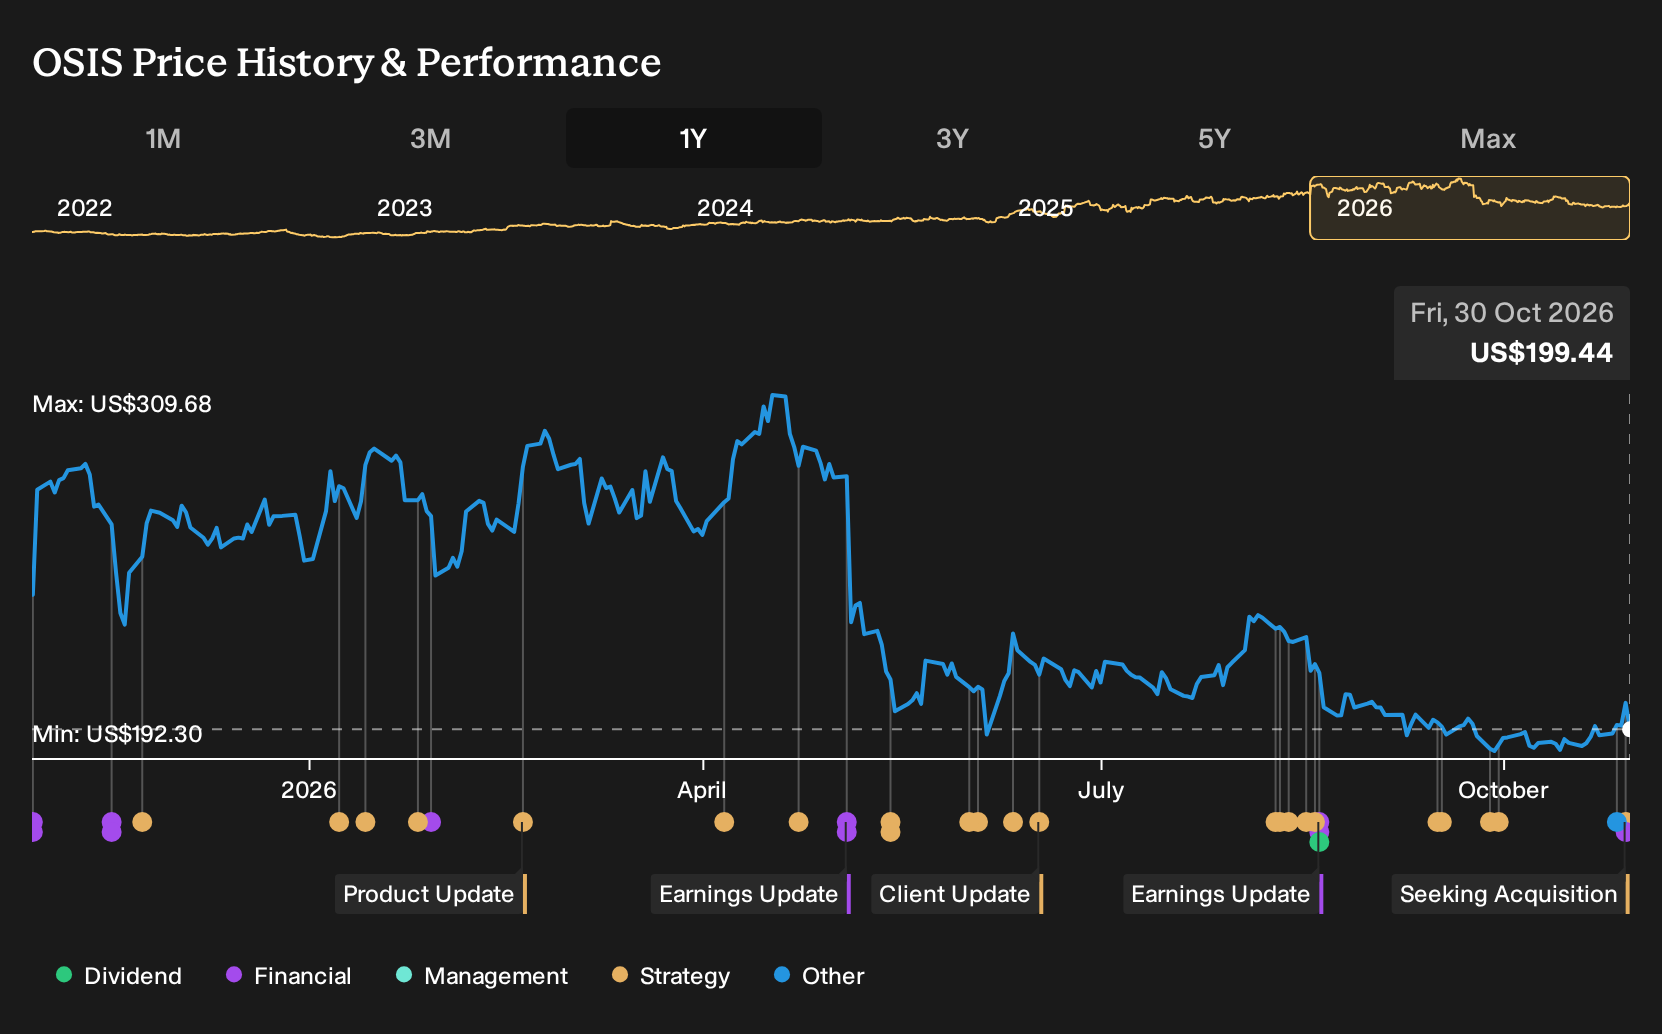
Exploring Other Perspectives
Fair value estimates for OSI Systems from three members of the Simply Wall St Community stretch from about US$82 per share to roughly US$278, which shows how far apart individual views can be. Those opinions do not reflect the latest Q1 record results, backlog trends or acquisition plans, so treat them as starting points and explore several contrasting viewpoints before deciding how this story fits your portfolio.
Explore 2 other OSI Systems fair value estimates, including one that suggests as much as 59% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker: dig into the data and build a conviction that's truly your own.
- A great starting point for your OSI Systems research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for OSI Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OSI Systems' overall financial health at a glance.
Looking for more investment ideas beyond OSI Systems?
Once you have formed a view on OSI Systems, it can help to compare that thesis with other opportunities that share similar qualities or speak to very different goals in your portfolio. The Simply Wall St Screener offers several focused ways to do that without getting lost in a huge list of tickers.
- If capital preservation and steadier profiles matter most to you, consider filtering for 29 resilient stocks with low risk scores that could help anchor your portfolio through different market moods.
- Income focused investors may want to concentrate on dependable cash returns, which is where 5 dividend fortresses can highlight potential options throwing off meaningful yields.
- For those hunting for underappreciated stories with strong fundamentals, the 19 high quality undiscovered gems can surface lesser known candidates that might complement or contrast your OSI Systems thesis.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com