


EN
Raised Guidance Could Change The Case For Investing In Frost Bank Shares
- Cullen/Frost Bankers reported third quarter 2026 net income of about US$180 million with higher earnings per share, raised full year 2026 net interest income growth guidance to a range of 5% to 5.5%, continued share repurchases, and affirmed both common and preferred dividends already scheduled for payment in December 2026.
- The combination of upgraded net interest income guidance and ongoing capital returns through buybacks and dividends provides insight into how Cullen/Frost Bankers is balancing growth investment in Texas branch expansion with shareholder payouts funded by its current earnings profile.
- Next, the focus will be on how Cullen/Frost Bankers' upgraded net interest income guidance could influence the broader investment narrative.
Cullen/Frost Bankers Investment Narrative Recap
To own Cullen/Frost Bankers, you need to be comfortable with a Texas-centric, branch-heavy growth model that depends on steady loan and deposit activity. The raised 2026 net interest income growth guidance to 5% to 5.5% keeps the near-term story anchored in core banking earnings, not one-off items or market moves.
The key short-term swing factor is whether loan demand and deposit mix can support that higher income range while credit costs stay manageable. Rising net charge-offs and pockets of pressure in Texas real estate and energy remain the biggest watchpoint, though this update does not materially change that risk profile.
The most relevant fresh data point is the upgraded 2026 net interest income outlook, alongside reiterated net interest margin improvement of about 10 to 13 basis points over 2025. This guidance sits on top of third-quarter net income of about US$180 million and higher earnings per share from continuing operations.
For you as an investor, that combination ties directly into the existing catalyst of Texas branch expansion and new relationship growth. Execution now hinges on Cullen/Frost Bankers converting its record loan pipeline and new commercial relationships into profitable balances while keeping funding costs, branch spending and credit losses from eroding the benefit of higher guided interest income.
Cullen/Frost Bankers' current analyst narrative points to revenues of about US$2.6b and earnings of roughly US$716.4 million by 2029, built on assumed yearly revenue growth of 5.1%. That outlook starts from earnings today of around US$669.4 million and implies an earnings increase of about US$47 million by the 2029 forecast year.
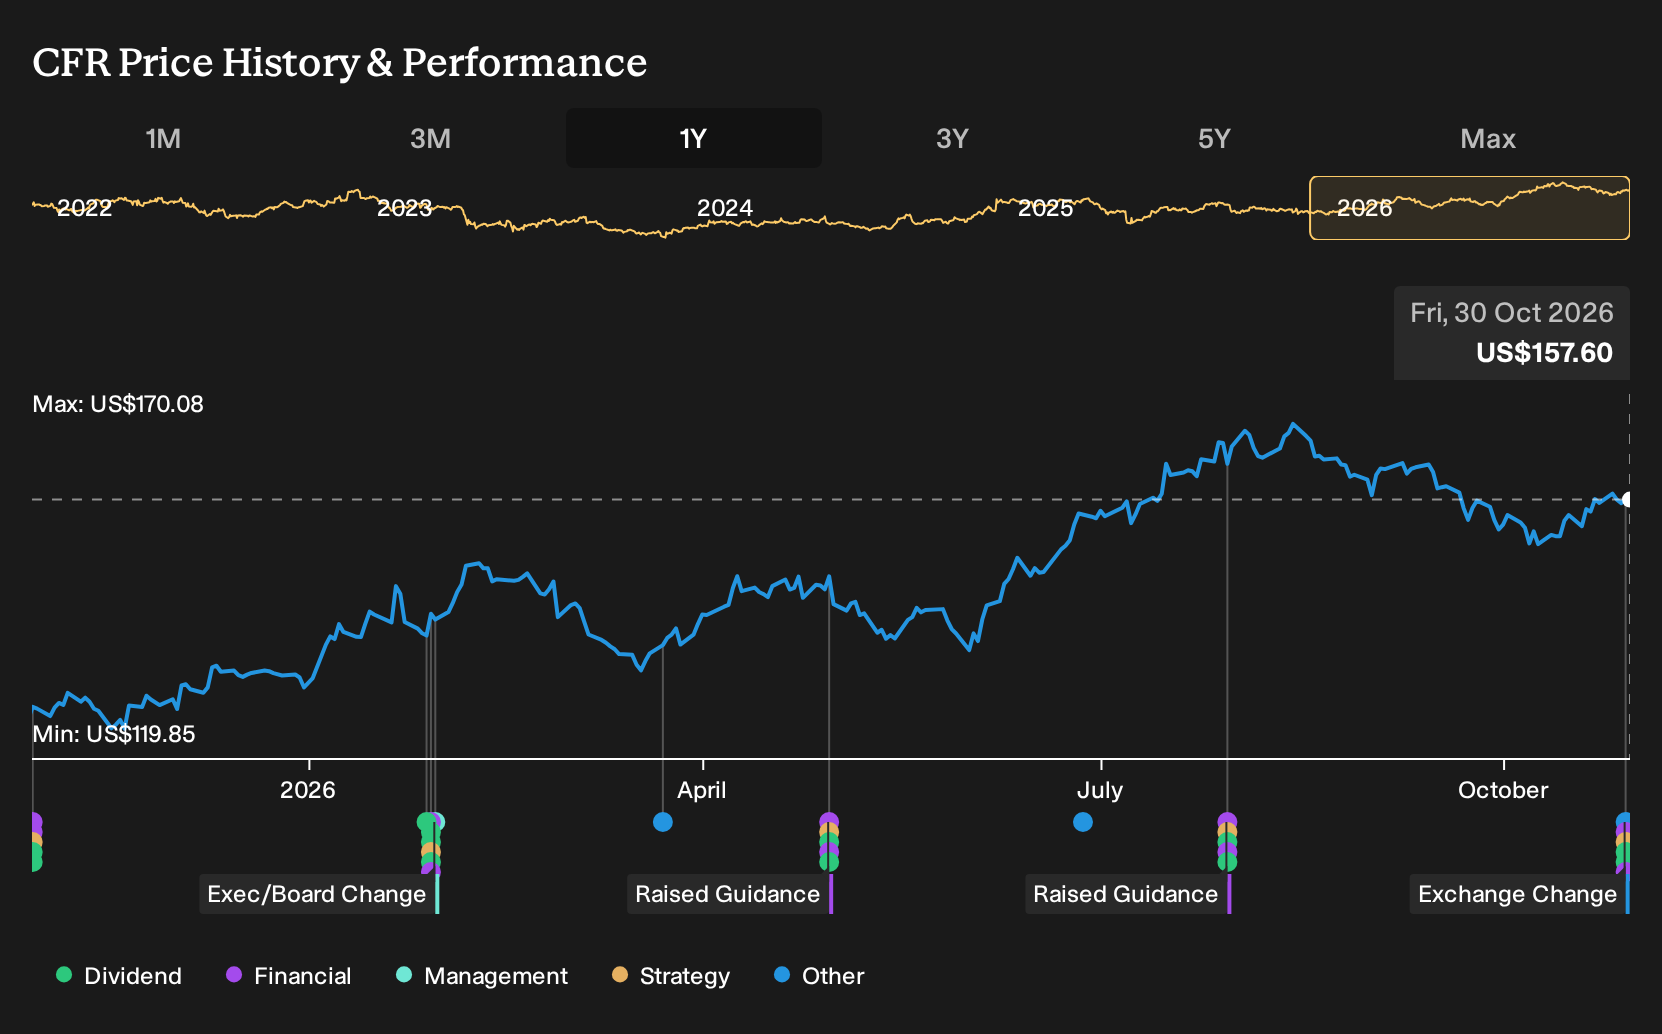
Uncover how Cullen/Frost Bankers' fair value points to an 11% potential upside to its current price that could narrow quickly if sentiment catches up.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$175 to US$253, which already shows how far opinions on Cullen/Frost Bankers can stretch. Those retail views pre date the higher 2026 guidance, continued buybacks, rising net charge offs and the planned Texas Stock Exchange move. Use them as starting points and compare several viewpoints before deciding what matters most to you.
Explore another Cullen/Frost Bankers fair value estimate, including one that suggests it could be worth just $174.86.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cullen/Frost Bankers research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cullen/Frost Bankers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cullen/Frost Bankers' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cullen/Frost Bankers?
If you want to apply the same disciplined lens used on Cullen/Frost Bankers to a wider watchlist, the Simply Wall St Screener can help you quickly surface stocks that match your income goals, risk tolerance and balance sheet preferences.
- For income seekers who care about resilience first and yield second, start with companies we consider 5 dividend fortresses that keep cash returns front and centre.
- If capital preservation sits high on your list, narrow the field to 29 resilient stocks with low risk scores that score well on fundamentals and balance sheet strength.
- When you want potential upside with financial quality as a filter, look through 19 high quality undiscovered gems that pair solid metrics with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com