


EN
Insperity Stock Gains Focus After Margin Recovery Progress】【。
- Insperity reported third quarter 2026 sales of US$1,651 million and a net loss of US$1 million, while nine month sales reached US$5,232 million with net income of US$36 million and higher diluted EPS from continuing operations than a year earlier.
- The business showed progress on its margin recovery plan, with management pointing to improved adjusted EBITDA, higher gross profit per worksite employee and AI powered HR tools as key supports for earnings quality.
- We will look at how Insperity's investment narrative intersects with this margin focused progress, especially the improvement in profitability metrics.
Scan margin focused HR and AI plays that echo Insperity's Q3 reset by moving through our hand picked 40 profitable AI stocks that aren't just burning cash while this theme is back in the spotlight.
Insperity Investment Narrative Recap
To own Insperity, you need to believe the margin recovery story can keep moving forward while the HR platform and AI projects gradually carry more weight. The latest quarter fits that script, with higher adjusted EBITDA and better profit per worksite employee, even as the headline result still showed a small loss. The key near term swing factor is whether pricing, benefit redesign and client mix continue to offset healthcare costs.
The biggest operational risk remains benefit inflation and weak hiring at small and mid sized clients, which could cap earnings if worksite employee counts stay soft. Recent guidance that frames Q4 net income between a US$6 million loss and a US$8 million profit indicates that management still sees some volatility in that balance.
The most relevant new datapoint is Insperity's updated outlook for 2026 net income of US$32 million to US$45 million and diluted EPS of US$0.81 to US$1.16. That range ties directly to the margin story investors are focused on, because it leans heavily on gross profit per worksite employee rather than unit growth.
For shareholders, that guidance frames both the near term catalyst and the key risk. Progress toward the upper half of the range would signal that repricing, HRScale, the Workday rollout and AI tools are all translating into better profitability, while results near the low end would point to ongoing pressure from healthcare costs or slower than hoped adoption of the newer HR offerings.
What The Analyst Forecasts Assume For Insperity
Analysts are effectively treating Insperity as a margin repair story with a long runway. Revenue is modeled to rise by 3.7% a year over the next few years, while profit margins are expected to move from a small loss position today to 1.9% by 2029. On those projections, the group would be generating US$7.7b of revenue and US$145.3 million of earnings in that year, compared with a current loss of US$16.0 million.
That profit swing is substantial. Moving from a loss of US$16.0 million to earnings of US$145.3 million implies roughly a US$161 million change in the bottom line. The consensus assumes this shift happens without explosive unit growth. This puts the spotlight squarely on pricing power, healthcare cost management and the contribution from HRScale and the broader AI toolkit that Insperity is rolling out across its HR platforms.
Insperity's narrative projects US$7.7b revenue and US$145.3 million earnings by 2029. This requires 3.7% yearly revenue growth and roughly a US$161 million earnings increase from a current loss of US$16.0 million.
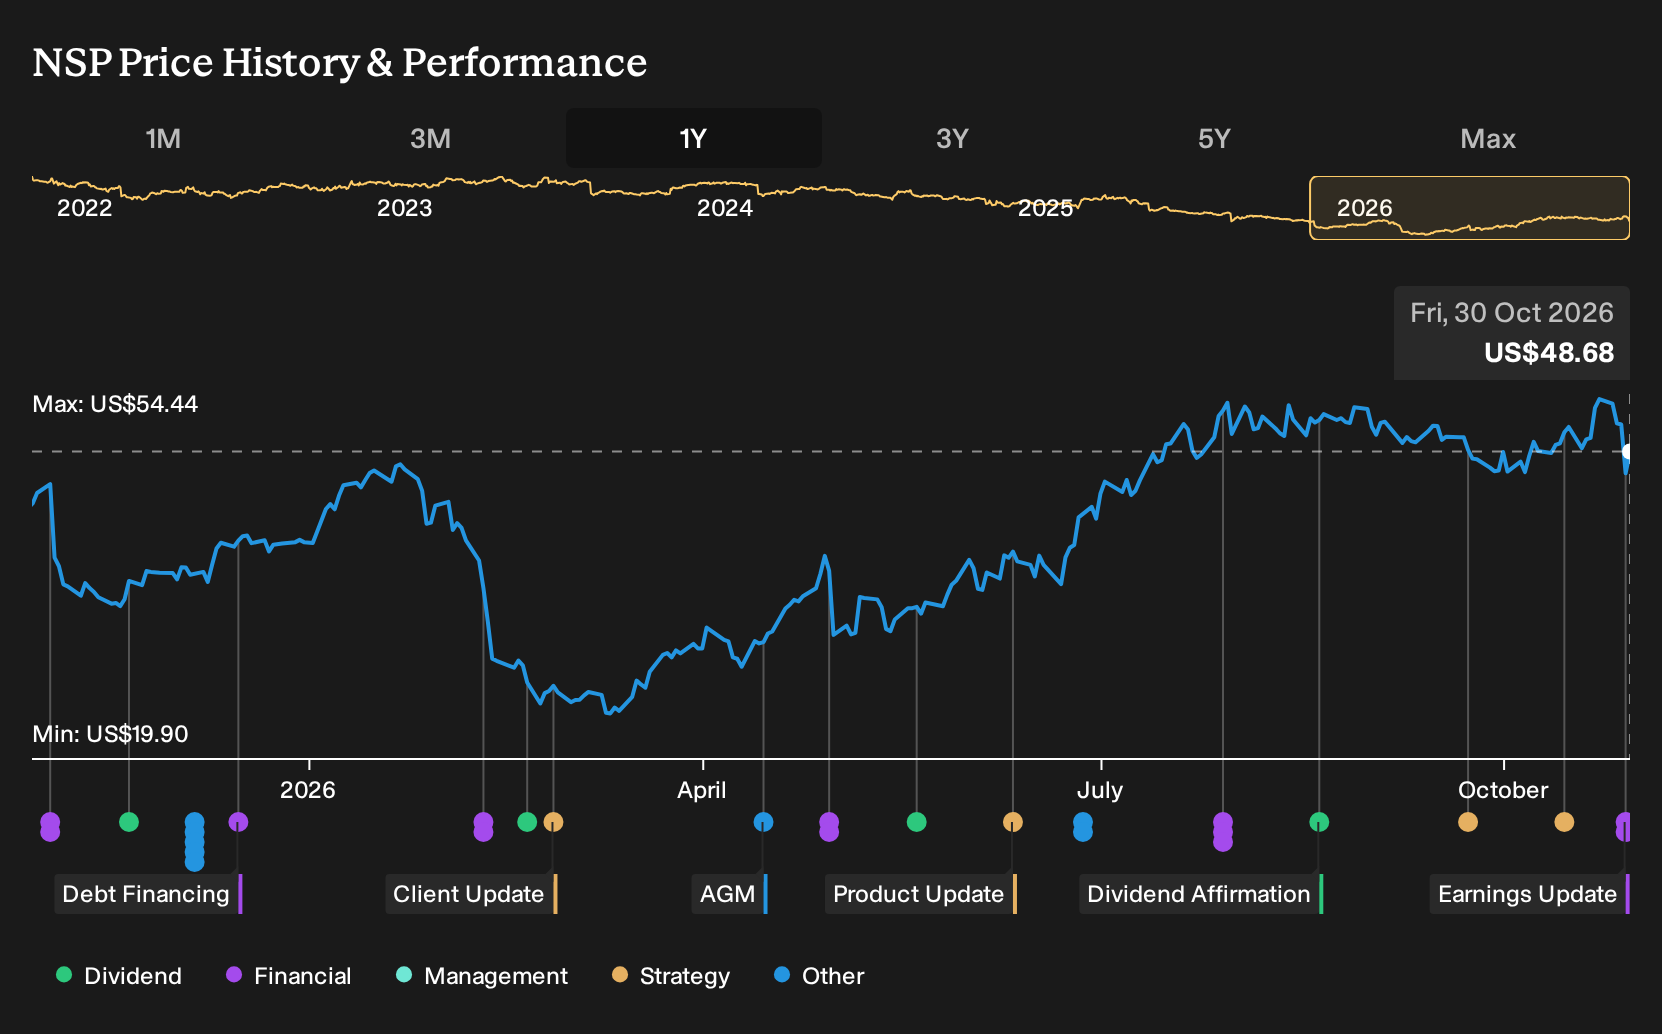
Uncover why Insperity's fair value signals a 6% potential upside to its current price, which could narrow quickly if Insperity continues to deliver on margin repair.
Exploring Other Perspectives
One bullish twist on Insperity leans hard into HRScale as a potential earnings engine. Before this Q3 update, the most optimistic analysts were penciling in revenue of about US$7.8b and earnings of roughly US$147.8 million by 2029. That indicates a stronger path than the baseline and highlights how far opinions can diverge. Use this Q3 margin reset to compare those upbeat assumptions with your own view on HRScale, AI tools and healthcare costs. These forecasts were set before the latest numbers and could change as new information emerges.
Explore 3 other Insperity fair value estimates, including one that suggests as much as 260% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own judgment.
- A great starting point for your Insperity research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Insperity. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insperity's overall financial health at a glance.
Looking For More Investment Ideas Beyond Insperity?
If the Insperity story has sharpened your focus on quality, margins and resilience, use that lens across the wider market with the Simply Wall St Screener to surface stocks that fit your own risk and return preferences.
- For investors who want potential mispricing on their side, scan companies that currently look out of favour but financially robust through our 30 high quality undervalued stocks.
- If capital preservation sits high on your list, narrow in on steadier businesses by moving through a 29 resilient stocks with low risk scores that aims to keep downside surprises in check.
- When you want to get ahead of the crowd, hunt for under-followed opportunities by working through a 19 high quality undiscovered gems that surfaces lesser known stocks with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com