


EN
Methanex (TSX:MX) Following Strong Q3 And Buyback Plans, Is The Rally Already Priced In
What Methanex’s latest quarter changed for investors
Methanex (TSX:MX) just combined a strong third quarter earnings release with fresh production guidance for 2026, a new share buyback plan, and a clear push to reduce debt.
The catalyst was a jump in sales and net income for the quarter, supported by tight methanol supply linked to Middle East conflict disruptions. Management paired that with guidance of 9.0 million tonnes of methanol and 0.3 million tonnes of ammonia for 2026, plus approval to repurchase up to 5% of outstanding shares.
Methanex’s strong third quarter has landed on top of an already powerful run in the share price, with a 1-day share price return of 13.76% after the release helping push the 30-day share price return to 19.78%. That short term surge builds on a 90-day share price return of 28.16% and a year-to-date share price return of 78.40%, while total shareholder return over five years is 84.89% as investors respond to higher methanol pricing, debt reduction plans, and the newly approved buyback.
Scan how Methanex’s move fits into the broader rally in materials by comparing it with our hand picked 4 high quality undervalued stocks, which combine strong cash flows with solid balance sheets.
After a 78.40% year to date surge on the back of Methanex’s latest quarter, the tension is simple: Is the valuation still playing catch up or already priced for peak conditions?
Most Popular Narrative: 10% Overvalued
Against a last close of CA$99.85, the most followed narrative for Methanex pegs fair value at CA$91.07, implying the recent rally now sits above that framework.
Methanex's strategic production and efficiency improvements position it to benefit from growing methanol demand, potentially boosting revenues and margins. The OCI acquisition expands capacity and market reach, improving earnings and operational efficiency while deleveraging strengthens financial stability.
See why 15 investors see Methanex as 10% overvalued.
Result: Fair Value of CA$91.07 (OVERVALUED)
Still, the whole story can shift quickly if contracted gas supplies tighten in regions like Chile or if the OCI acquisition delivers weaker synergies than expected.
Find out about the key risks to this Methanex narrative.
Another view on Methanex’s value
While the crowd narrative pegs Methanex at CA$91.07 on earnings assumptions, the SWS DCF model points to a future cash flow value of CA$142.56. At a last close of CA$99.85, that frame treats the stock as trading about 30% below its estimated fair value. Which story feels closer to how you see the next cycle playing out?
Look into how the SWS DCF model arrives at its fair value.
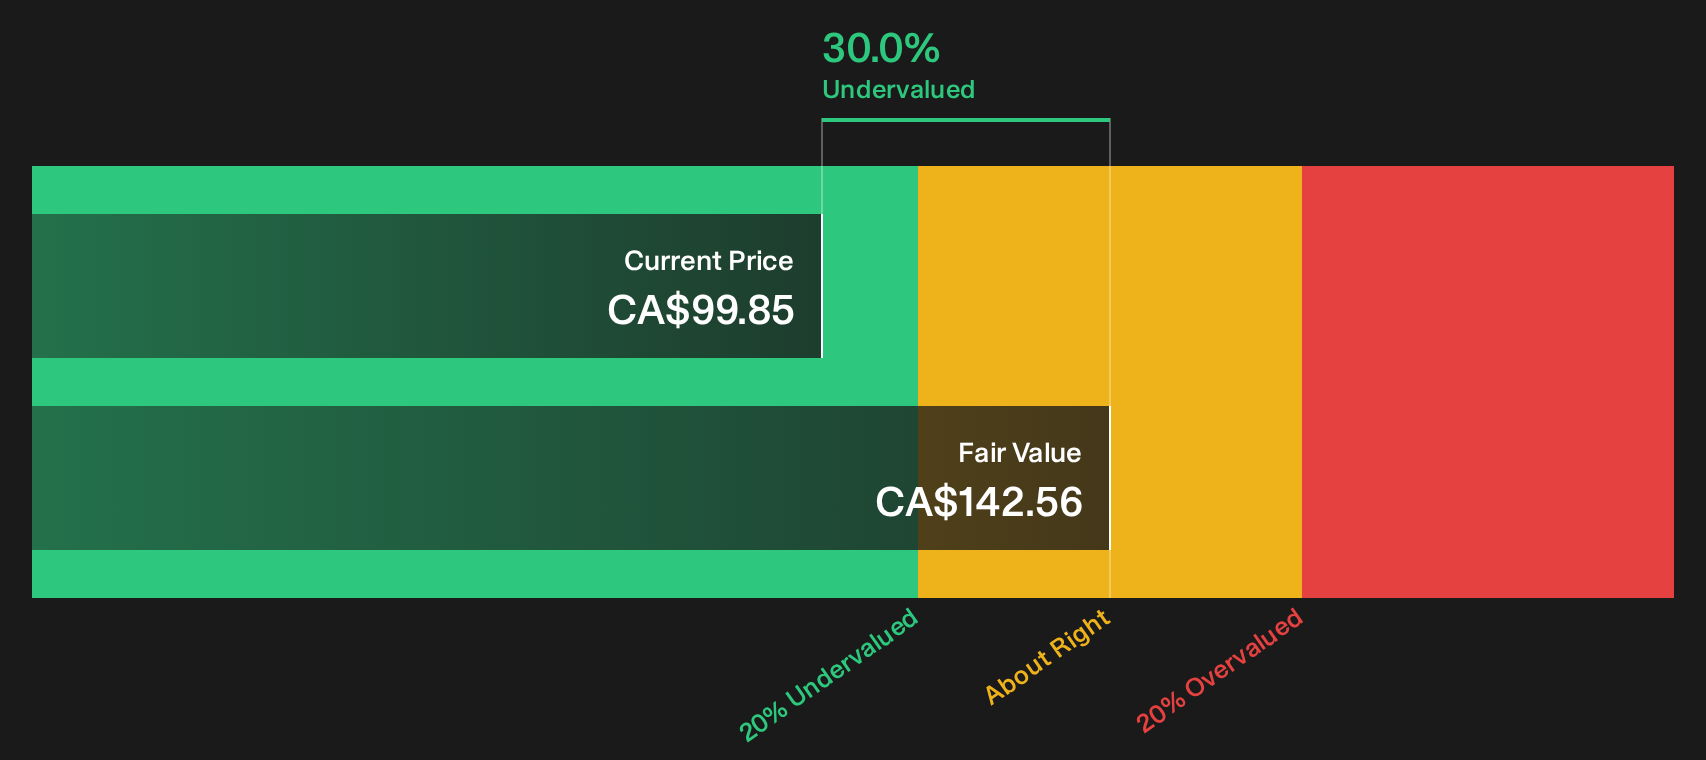
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Methanex for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split views on Methanex have you torn, that is the point. Move quickly, review the numbers yourself, then weigh up the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Methanex?
If Methanex has sharpened your thinking, do not stop there. Use the Simply Wall Street Screener to line up your next round of opportunities before the crowd.
- Target reliable cash generators by reviewing companies in the 4 high quality undervalued stocks that pair quality fundamentals with pricing that still looks reasonable.
- Prioritize resilience and aim to sleep easier at night by focusing on the 9 resilient stocks with low risk scores that score well on stability and downside protection.
- Look for tomorrow's potential leaders early by scanning the 8 high quality undiscovered gems that already show strong business quality before they reach wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com