


EN
Is FirstCash Holdings (FCFS) Overvalued On Strong Q3 Earnings And Higher Shareholder Payouts?
FirstCash Holdings (FCFS) just put a spotlight on shareholder payouts with fresh Q3 results, higher 2026 earnings guidance, a 10% dividend bump, and a larger buyback authorization now all on the table.
Despite the upbeat Q3 news, FirstCash Holdings shares have had a choppy run, with the 30 day share price return down 13.84% and the 90 day move lower by 13.42%. Yet the year to date share price return of 15.61% and five year total shareholder return of 123.48% still point to longer term momentum from the current US$181.25 level.
Spot opportunities with shareholder friendly policies similar to FirstCash Holdings by scanning our curated list of 5 dividend fortresses.The mixed share price over the past quarter, set against stronger recent earnings and richer shareholder returns from FirstCash Holdings, raises a simple issue. Is the latest pullback about the business or about sentiment, and what does that mean for valuation now?
Preferred P/E of 19.1x: Is it justified?
On traditional metrics, the question around FirstCash Holdings right now is simple. At a last close of $181.25, investors are paying a P/E of 19.1x in a Consumer Finance group where peers on average trade at 11.3x and the broader US Consumer Finance industry sits at 8.5x.
The P/E ratio compares the current share price to earnings per share and is a quick shorthand for how much you pay for each dollar of profit. For a lender and pawn-focused operator like FirstCash Holdings, which serves cash and credit constrained customers across multiple regions, this benchmark matters because earnings quality, growth durability, and balance sheet risk often differ widely across the sector.
Recent numbers show annual earnings growth of 31.2% against a 5 year earnings growth rate of 18.7% per year, with revenue up 8.5% on an annual basis and net income of $406.493m on revenue of $4.286b. That kind of profit expansion, combined with high quality earnings, higher current net margins of 9.5% compared with 8.9% last year, and returns that exceeded both the US market and the Consumer Finance industry over one year, helps explain why the market is willing to pay more than the peer average. At the same time, a fair P/E estimate of 14.5x suggests the 19.1x price tag is rich and points to a level the multiple could gravitate toward if expectations cool or growth normalises.
Against US peers on 11.3x and an industry average multiple of 8.5x, FirstCash Holdings is trading on a meaningfully higher earnings valuation today. The stock is not only above the peer group but also well above the estimated fair P/E of 14.5x. This implies the current premium multiple bakes in optimistic assumptions that leave less room for error if earnings growth or returns on equity, currently 17.9%, do not improve from here.
Explore the SWS fair ratio for FirstCash Holdings.
Result: Price-to-earnings of 19.1x (OVERVALUED)
Still, a richer P/E for FirstCash Holdings could come under pressure if earnings growth slows or if credit and pawn customers face a tougher backdrop.
Find out about the key risks to this FirstCash Holdings narrative.
Another view on FirstCash Holdings’ valuation
The P/E argument paints FirstCash Holdings as expensive, but the SWS DCF model goes further. It values the shares at $94.90, well below the current $181.25 level. This frames the stock as overvalued based on future cash flows. So which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
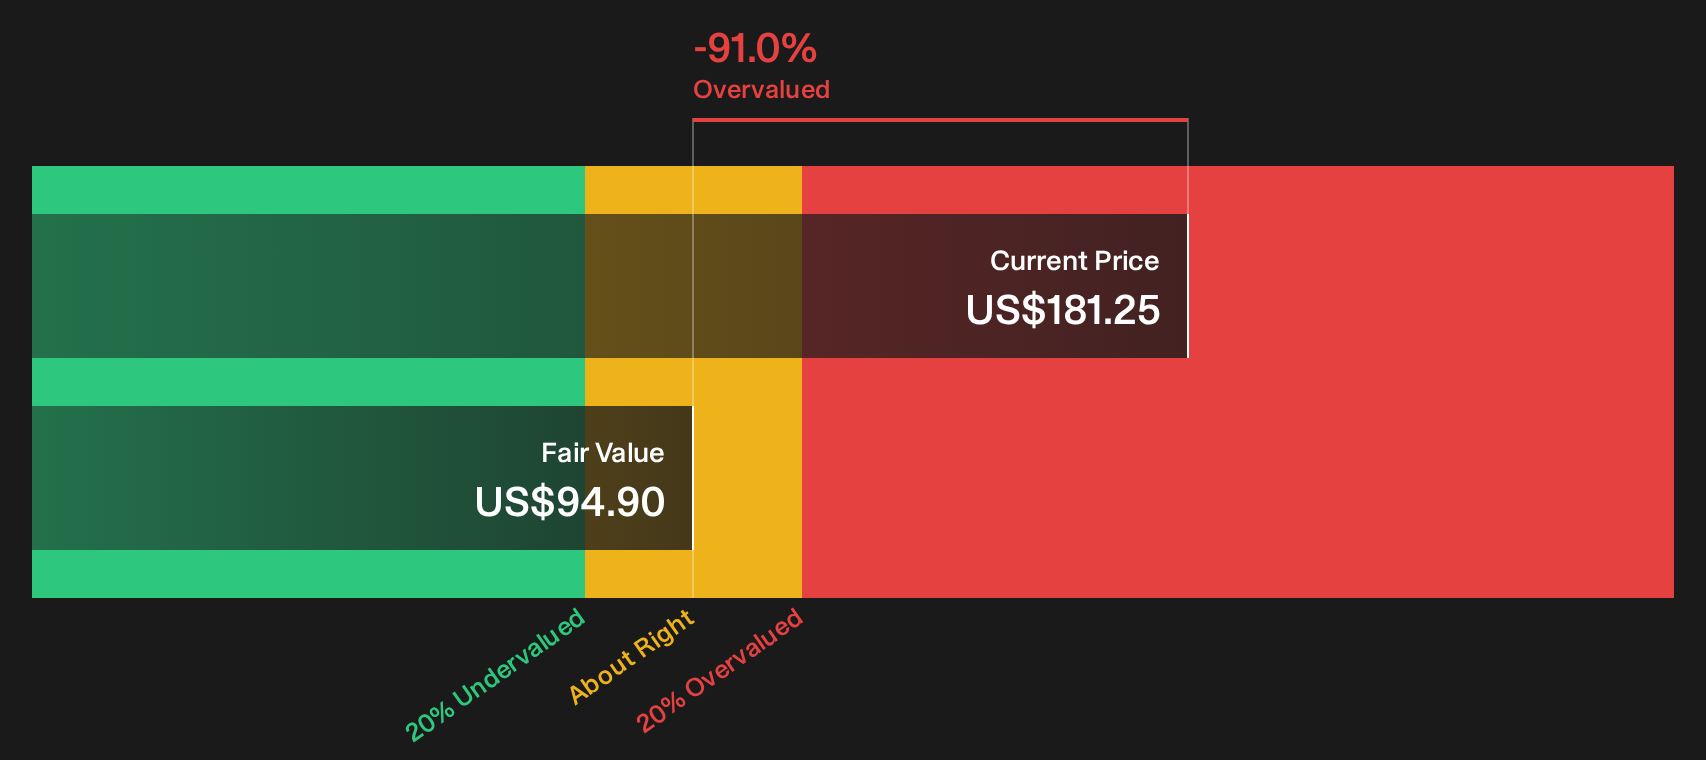
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FirstCash Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment on FirstCash Holdings clearly split between rich valuation signals and shareholder friendly actions, it makes sense to move fast and check the details for yourself while this setup is still fresh. To weigh the trade off between concerns and upside potential, start with our summary of 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond FirstCash Holdings?
If you stop with FirstCash Holdings, you risk missing other opportunities that line up better with your goals, risk comfort, and income needs right now.
- Target resilient income by scanning a focused 5 dividend fortresses designed to highlight businesses that pair cash returns with balance sheet support.
- Hunt for potential mispriced quality with a curated 30 high quality undervalued stocks that filters for financial strength alongside attractive valuations.
- Spot future contenders early using a research ready 19 high quality undiscovered gems that surfaces fundamentally sound businesses before they attract broader attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com