


EN
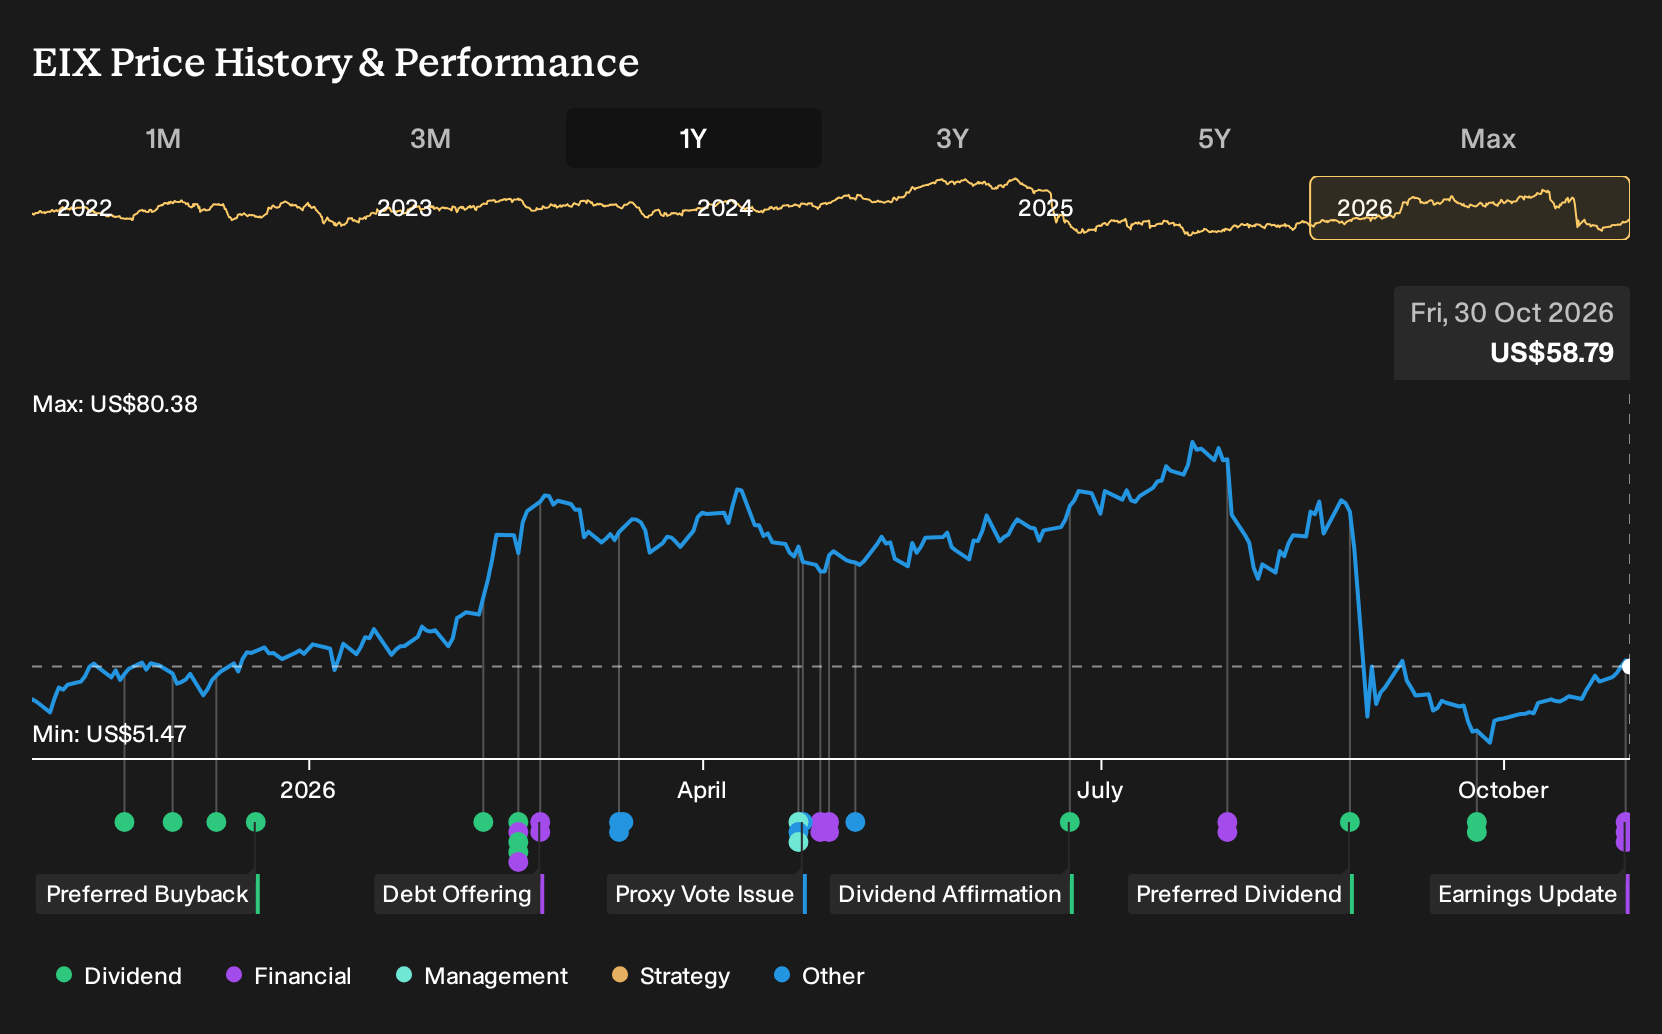
How Wildfire Liability Risks At Edison International (EIX) Have Changed Its Investment Story
- Edison International reported third quarter 2026 revenue of US$4.886b and net income of US$724m, with basic EPS from continuing operations at US$1.88. The company modestly lowered full year 2026 basic EPS guidance to a range of US$5.66 to US$5.96.
- Wildfire exposure tied to the 2025 Eaton Fire, thousands of related lawsuits and the rejection of California liability reform are putting legal, regulatory and funding pressure on Edison International as it pursues a large grid investment and wildfire mitigation program.
- This article examines how Edison International's investment narrative is being reshaped by rising wildfire liabilities and rejected California liability reform.
Edison International Investment Narrative Recap
To own Edison International, you need to be comfortable with a regulated utility that is trying to execute a very large grid upgrade program while carrying heavy wildfire exposure. The thesis leans on policy driven electrification and a multi year US$38b to US$41b capital plan, while accepting that wildfire costs and rate decisions can tighten financial flexibility.
Right now the main near term swing factor is how wildfire liabilities and any credit implications affect that investment agenda. The Q3 2026 revenue and EPS step down, plus slightly lower full year basic EPS guidance, highlight that earnings are already under pressure, but do not on their own change the central wildfire and regulation risk.
The shelf registration and dividend reinvestment plan sit closest to the current story. By putting a framework in place to issue common stock tied to reinvested dividends, Edison International gives itself another funding lever for grid spending and wildfire related needs, alongside debt, securitizations and insurance recoveries where available.
For you as an investor, that matters because the pace and mix of future funding is one of the key catalysts to watch, along with wildfire case developments and regulatory outcomes. Any equity issuance under the shelf could modestly dilute existing holders, yet it also has the potential to support balance sheet resilience if wildfire settlements or grid projects demand more capital than cash generation comfortably covers.
Edison International is framed around analysts projecting US$20.9b in revenue and US$2.7b in earnings by 2029, based on an assumed 2.4% yearly revenue growth rate and a move from US$3.7b in earnings today to that lower figure. This represents a US$1.0b earnings decline over the period.
Uncover why Edison International's fair value indicates a 9% potential upside to its current price, which could materialize more quickly than wildfire liabilities are resolved.
Exploring Other Perspectives
One alternate view focuses on credit strain rather than the grid build. In that pessimistic story, wildfire liabilities and higher borrowing costs keep Edison International boxed in, with bearish analysts penciling in flat revenue and only about US$2.5b of earnings by 2029. Those projections were set before this latest guidance cut, so you may see forecasts shift again as views adjust.
Explore 4 other Edison International fair value estimates, including one that suggests as much as 29% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Edison International research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Edison International. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Edison International's overall financial health at a glance.
Looking for more investment ideas beyond Edison International?
If Edison International's wildfire and grid profile feels like a bit too much drama for your portfolio, you can broaden your watchlist with other companies that line up more closely with your risk and income preferences using the Simply Wall St Screener.
- For investors who want potential mispricings backed by solid fundamentals, scan a curated set of 19 high quality undiscovered gems that might not yet be on every analyst's radar.
- If capital preservation and resilience sit at the top of your checklist, focus on a 29 resilient stocks with low risk scores that filters for businesses with steadier risk scores.
- When reliable income is the priority, zero in on a hand picked group of 5 dividend fortresses that combine elevated yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com