


EN
AS ONE (TSE:7476) Resets Dividend Policy As A Richer Valuation Debate Builds
Dividend policy reset puts AS ONE in focus
AS ONE (TSE:7476) has called a board meeting for 30 October 2026 to review its dividend framework, including a proposal for performance linked payouts and a higher targeted payout ratio.
On the agenda is a progressive dividend policy for FY03/2026 to FY03/2028 and a suggested lift in the FY03/2027 year end dividend by ¥3 per share to ¥36, for a full year total of ¥69 per share based on the company’s stated calculation method.
AS ONE’s dividend rethink comes after a mixed run in the market, with the share price delivering a 7.33% year to date return and a 7.11% 90 day share price gain. However, the 5 year total shareholder return of a 20.42% decline points to much weaker longer term results and fading momentum over that horizon.
Scan how AS ONE’s dividend rethink compares with peers by running the same lens over 29 dividend fortresses that have already put shareholder returns at the forefront.
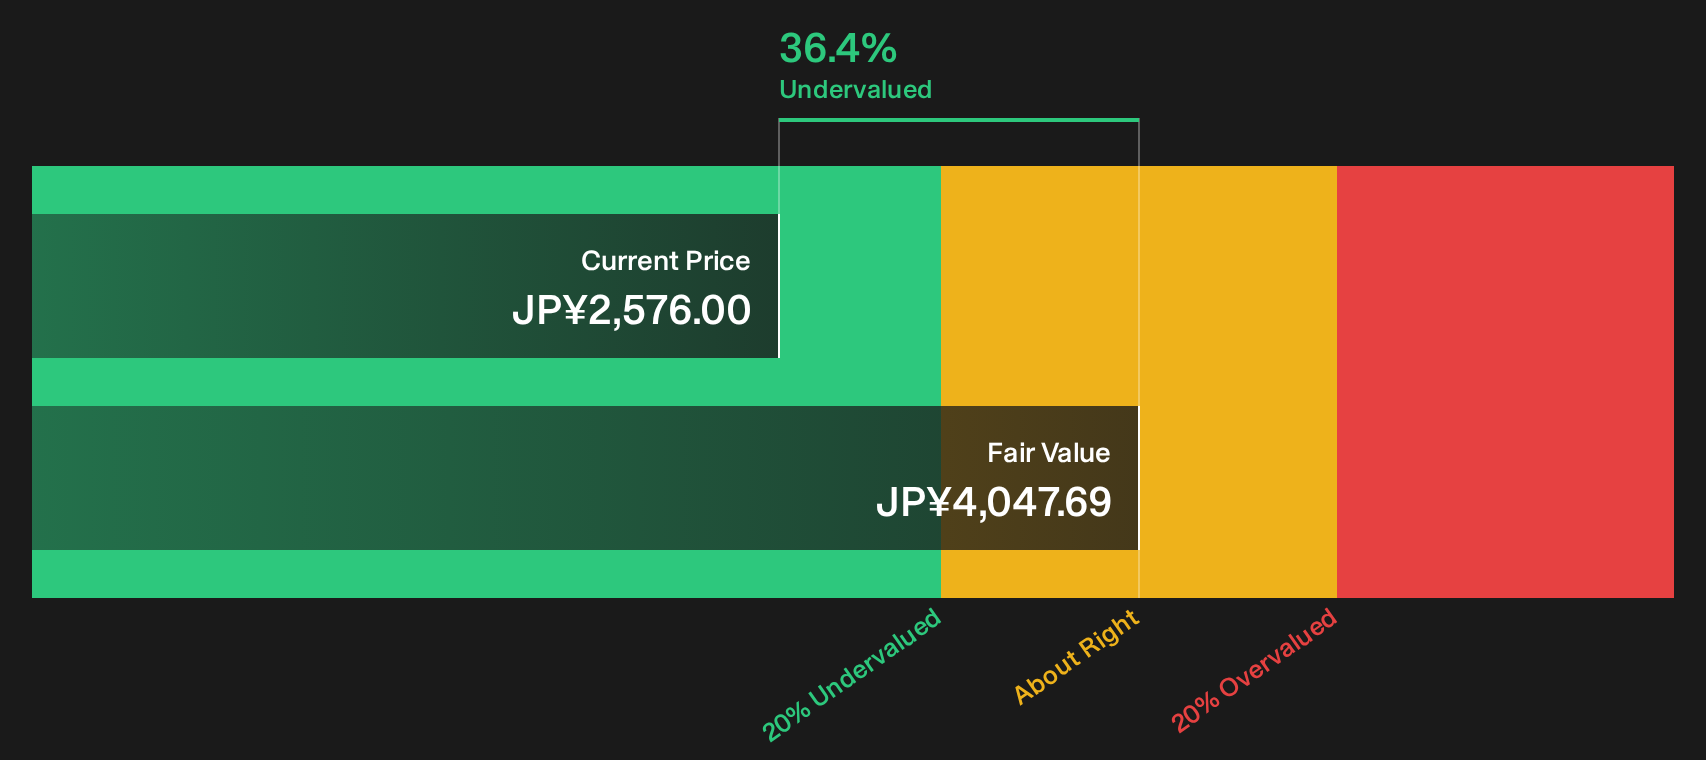
AS ONE now trades with a richer dividend story and a 36.4% implied discount to its intrinsic value estimate. Does that combination still tilt the risk reward in favour of buyers from here?
Most Popular Narrative: 22% Overvalued
AS ONE last closed at ¥2,576, while the widely followed narrative from AstrisCorporateAdvisory places fair value nearer ¥2,114. This implies the shares trade ahead of that assessment and puts extra weight on whether growth investments pay off.
FY3/27 expected to be a transitional year, AS ONE delivered full year operating profit growth ahead of revenue growth in FY3/26, demonstrating the operating leverage in its model. The FY3/27 financial guidance points to a year of growth investments, which should translate to profitability improvement in future years.
See why 1 investors see AS ONE as 22% overvalued.
According to AstrisCorporateAdvisory, this view of AS ONE leans heavily on the idea that current spending on a larger Rental & Calibration Center and logistics upgrades eventually supports a more recurring and higher margin service stream, even though near term guidance builds in higher SG&A and softer earnings per share. That puts the current premium over this narrative fair value in context, since the market price already reflects a degree of confidence in those projects and in management’s recent track record of 14.1% earnings growth and a 13.3% return on equity.
Result: Fair Value of ¥2,113.81 (OVERVALUED)
Still, the AS ONE story can break if rental and calibration adoption lags expectations, or if higher SG&A spend fails to translate into healthier profitability.
Find out about the key risks to this AS ONE narrative.
Another View: AS ONE and the SWS DCF Model
The AstrisCorporateAdvisory narrative tags AS ONE as roughly 22% overvalued against its ¥2,113.81 fair value, yet our SWS DCF model points in the opposite direction. Viewed through that lens, the shares at ¥2,576 trade about 36.4% below an estimated future cash flow value of ¥4,047.69. Which story do you trust when the next bout of volatility hits?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AS ONE for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of confidence and concern around AS ONE feels familiar, take a moment now to review the data yourself, examine your assumptions in detail, and stress test your own thesis while keeping an eye on 3 key rewards and 1 important warning sign.
Looking for more AS ONE style investment ideas?
AS ONE might already be on your radar, but the next opportunity could be sitting in a corner of the market you have not checked yet.
- Target resilient income by scanning for 29 dividend fortresses that focus on dependable payouts instead of short term excitement.
- Hunt for mispriced quality by reviewing the 15 high quality undervalued stocks that combine solid fundamentals with potential upside on valuation.
- Protect your downside by filtering for 24 resilient stocks with low risk scores that emphasise balance sheet strength and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com