


EN
DXC Technology (DXC), What Is Behind The Fresh Attention Now?
DXC earnings and guidance reset put recent rebound under fresh scrutiny
DXC Technology (DXC) just reported fiscal Q2 2027 results, updated its outlook for the rest of the year, and watched the stock fall after weaker bookings and lower guidance caught investors’ attention.
The selloff followed a 4% year over year revenue decline in the quarter and a reduction in full year revenue and adjusted earnings expectations. Management also projected Q3 sales below earlier market expectations and reported a slimmer operating margin compared with the same period last year.
Recent trading has been choppy for DXC Technology. The stock has given back some ground with a 1-day share price return of down 1.64% and a 7-day share price return of down 6.90%, after a strong 30-day share price return of 34.96% and a 90-day share price return of 36.55% lifted it to US$14.98. That rebound sits against a much weaker long-run picture, with total shareholder return of 5.49% over 1 year, down 32.83% over 3 years and down 56.36% over 5 years. This suggests that recent momentum is rebuilding from a low base while investors continue to reassess the risk around revenue declines, the possible insurance division sale and the latest guidance reset.
Spot fresh rebounds and potential value resets like DXC Technology by scanning our hand picked 30 high quality undervalued stocks in similar sectors and across the wider market.After a sharp rebound followed by a guidance cut, DXC Technology now sits at a level where falling revenue, potential asset sales and a lowly value score collide. Does that mix still tilt the risk reward towards buyers?
Most Popular Narrative: 20% Overvalued
DXC Technology closed at $14.98, while the most followed narrative pegs fair value at $12.50. The current price already leans toward a richer outcome that assumes meaningful execution on its plan.
The main thing that has to go right is DXC Technology executing on its shift from labor intensive services to AI driven, product and SaaS led offerings while delivering the planned $1.0 to $1.5 billion cost reduction and margin uplift.
The current valuation and this narrative’s view that DXC Technology is fairly valued and bullish together imply that the share price already reflects both the execution risks around the AI transition and the potential benefits from higher margin, capital light growth.
See why 14 investors see DXC Technology as 20% overvalued.
Result: Fair Value of $12.50 (OVERVALUED)
Still, the story around DXC Technology can change quickly if organic revenue keeps declining or if pressure on the GIS margin becomes a longer-term drag.
Find out about the key risks to this DXC Technology narrative.
Another View on DXC Technology’s Valuation
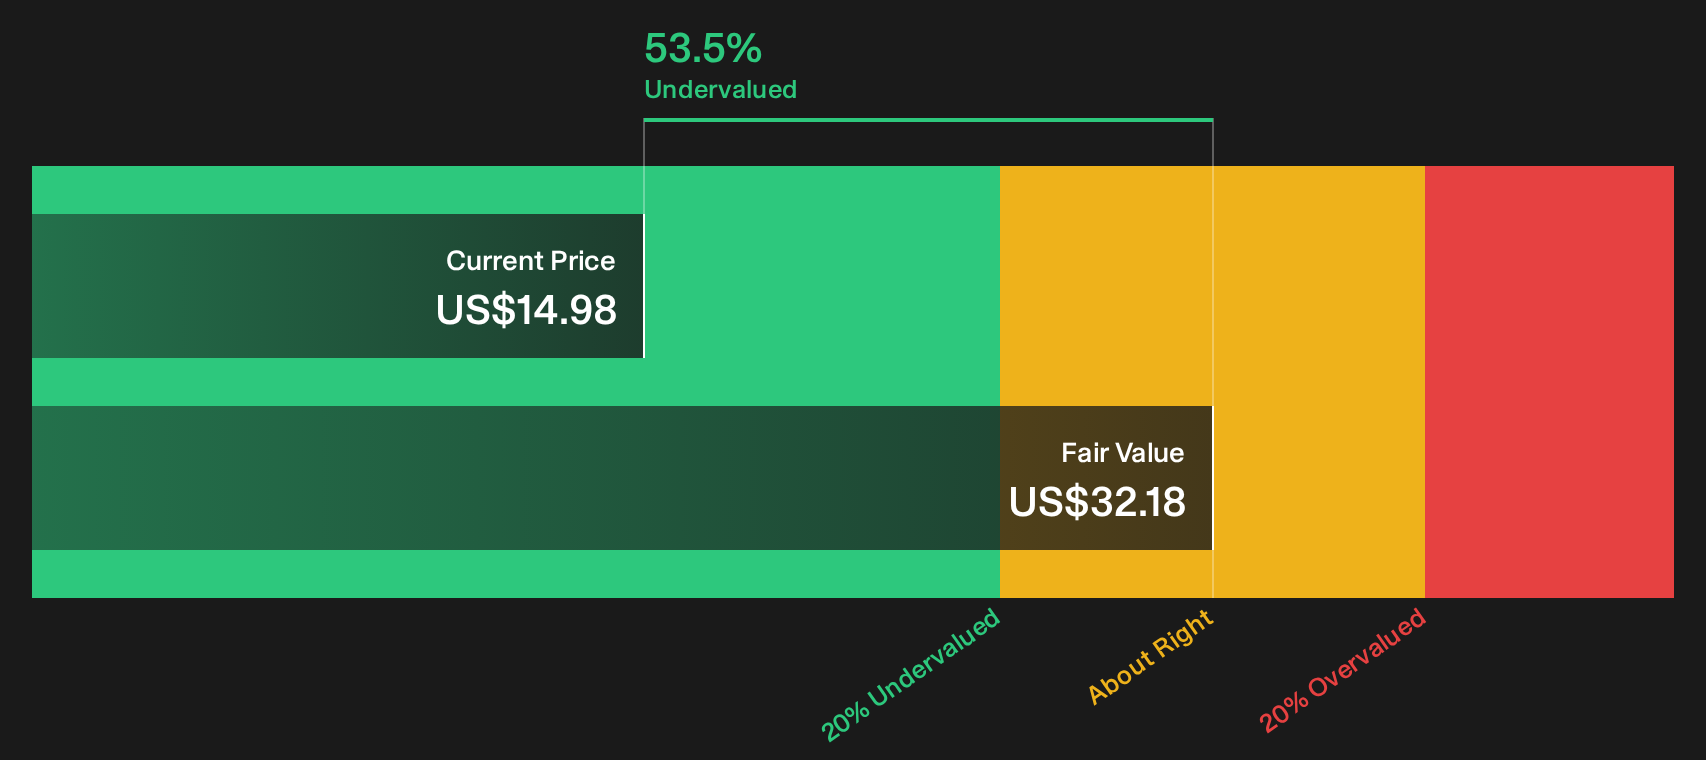
Multiples point one way, but the SWS DCF model points another. At a share price of $14.98, DXC Technology is trading about 53.5% below an estimated future cash flow value of $32.18, which frames the stock as undervalued. This gap may reflect potential opportunity or may instead indicate higher execution risk.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around DXC Technology can feel messy. Move quickly to test the numbers, weigh the downside and upside, and ground your own view with the 3 key rewards and 3 important warning signs
Looking for more DXC Technology sized opportunities?
If DXC Technology sits on your watchlist, do not stop there. Use curated screeners to surface other ideas before the next move leaves you watching from the sidelines.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) that filters for financial strength and cleaner capital structures.
- Hunt for misunderstood value by reviewing the 30 high quality undervalued stocks that highlight quality businesses trading at compressed valuations based on their fundamentals.
- Spot fresh ideas before the crowd by using the 19 high quality undiscovered gems focused on underfollowed companies with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com