


EN
CVS Health (CVS) Stock Could Be A Bargain After Its 44% Run
CVS Health has delivered a solid multi year share price gain while wrestling with questions about its Medicare Advantage ratings, pharmacy benefit management arm and how much earnings power the healthcare group can sustain. With the stock recently around US$90.25, the live issue for investors is whether that price fairly reflects what its current and expected profits justify.
- Over the past 3 years the stock has returned 43.9%, which puts real pressure on the question of whether today’s earnings base can shoulder that kind of move.
- Management has lifted its longer term revenue and adjusted earnings outlook and is investing in areas like AI and pharmacy benefits transparency, which can shape how investors think about the durability and growth profile of CVS Health’s profit stream.
- The analysts covering CVS Health have run their own numbers. See what analysts think CVS Health's shares could be worth.
The stock’s next move may depend on whether the current share price is appropriately tied to CVS Health’s earnings power once those factors are taken into account.
If you want to stress test the same earnings question that hangs over CVS Health against a broader group of candidates, run the numbers across 30 high quality undervalued stocks.
Is CVS Health Still Cheap on Earnings?
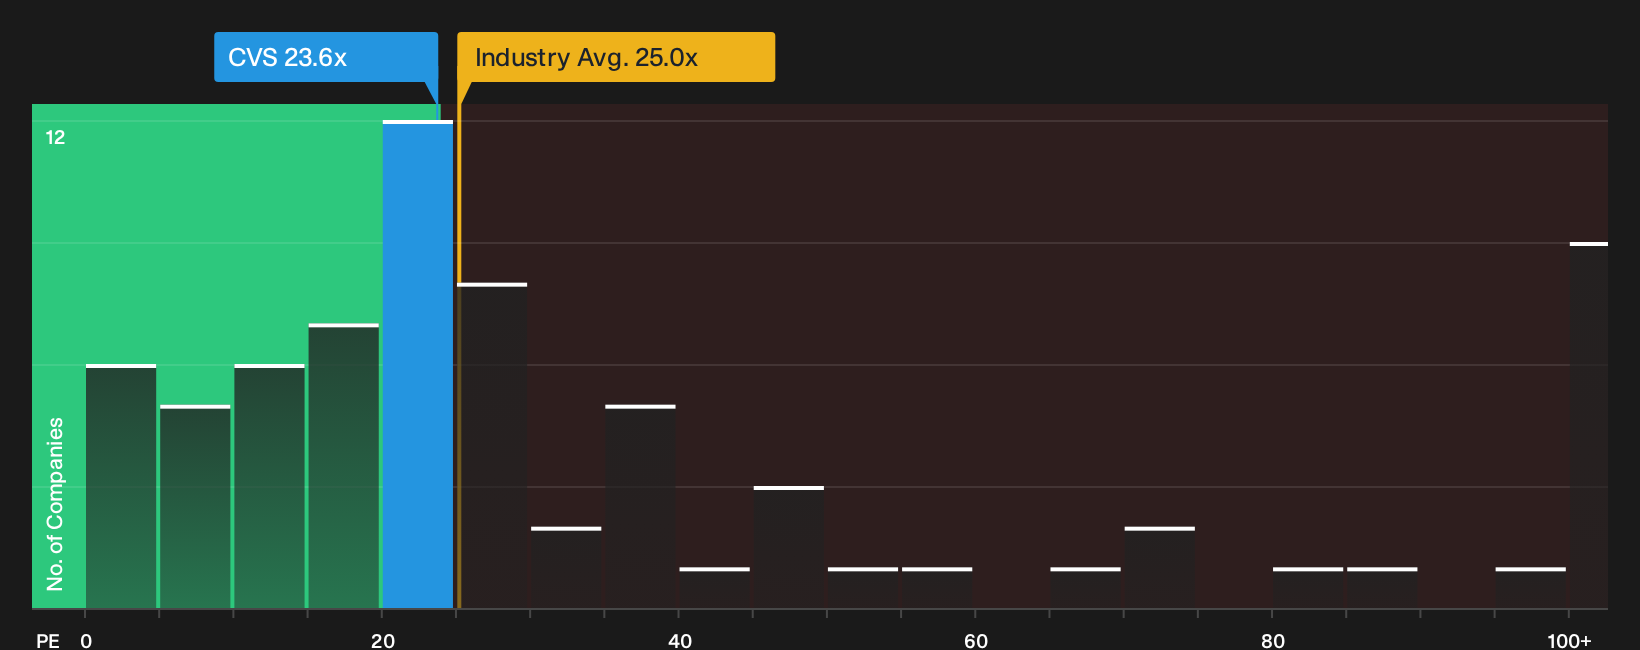
The P/E ratio is a useful way to look at CVS Health because earnings sit at the center of how investors judge a diversified healthcare group with insurance, pharmacy and services under one roof. On that yardstick, the shares trade around 23.6x earnings, which puts the stock above the peer average of roughly 19.8x but slightly under the broader healthcare sector on about 25.0x. That mix indicates the market is pricing CVS at a premium to direct comparables while still below the wider industry benchmark.
Because the firm’s raised 2026 earnings outlook directly affects what investors are willing to pay for each dollar of profit, the model-driven fair P/E points to a higher ratio than where the stock currently trades. On that basis, the shares screen as undervalued relative to this tailored yardstick. The Medicare Advantage star ratings lawsuit and potential effect on revenue remain a risk factor in the background, yet even with that in view the current P/E still comes in below the level implied by the fair multiple model. Explore the numbers behind CVS Health's P/E valuation.
The CVS Health Narrative: What Would Justify Today's Price?
Narratives on CVS Health pick up where the P/E puzzle leaves off by spelling out which assumptions on growth, profit margins and earnings would need to hold for the shares to be worth materially more or less than today’s price on Simply Wall St’s Community page. Each one treats fair value as a specific, testable idea about CVS Health’s business that you can watch over time, rather than a single frozen estimate.
One of the top community narratives on CVS Health: 13% undervalued
"CVS Health is rebuilding itself while still operating at full scale, a difficult balancing act that has weighed on investor confidence…"
Discover why this Narrative puts CVS Health at 13% undervalued.
The unanswered piece of CVS Health’s story
Price, profits and lawsuits say a lot about CVS Health, but the people setting priorities and how their pay is structured can quietly shape everything you care about as a shareholder. See who runs CVS Health and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com