


EN
Where Does FirstEnergy (FE) Valuation Sit After Its Latest Earnings?
FirstEnergy (FE) just put fresh numbers on the table. Third quarter revenue reached US$4,557 million and net income was US$557 million, while earnings per share from continuing operations came in at US$0.96.
Those earnings landed after a steady climb in FirstEnergy’s share price, which now trades at US$46.91 and has logged a 30 day share price return of 8.24% following the results, even though the 90 day share price return is still down 3.14%.
Scan utility peers that show similar earnings momentum to FirstEnergy, with the hand picked 41 power grid technology and infrastructure stocks shaping tomorrow's grid infrastructure.
The move in FirstEnergy shares has closed some of the gap to analyst targets, yet the stock still trades at a discount. Is that a cautious market misread, or a fair response to the risks priced in?
Most Popular Narrative: 9% Undervalued
FirstEnergy’s most followed narrative puts fair value at about $51.42, which sits above the latest close at $46.91 and frames the recent rally as only a partial catch up to the underlying thesis.
Surging demand from data centers, AI, and high growth sectors remains a central theme for FirstEnergy, with forecasted data center load of roughly 25 GW by Q2 2026 and 6.4 GW already contracted. This supports further investment in transmission and distribution assets and can lift long term revenue and earnings growth.
See why 16 investors see FirstEnergy as 9% undervalued.
That storyline leans on a 7.24% discount rate and assumes FirstEnergy can convert its planned US$36b capital program and data center linked projects into higher earnings and margins without eroding affordability or stretching the balance sheet too far.
The result is a fair value estimate of $51.42 that sits roughly 9% above the current share price, while still baking in earnings growth and profit margin assumptions that are not out of line with the company’s recent track record and regulatory framework.
Result: Fair Value of $51.42 (UNDERVALUED)
Still, the bullish FirstEnergy story hinges on regulators allowing recovery of that US$36b spend, and on high capital needs not squeezing cash flow and returns.
Find out about the key risks to this FirstEnergy narrative.
Another View: Multiples Point To Richer Pricing For FirstEnergy
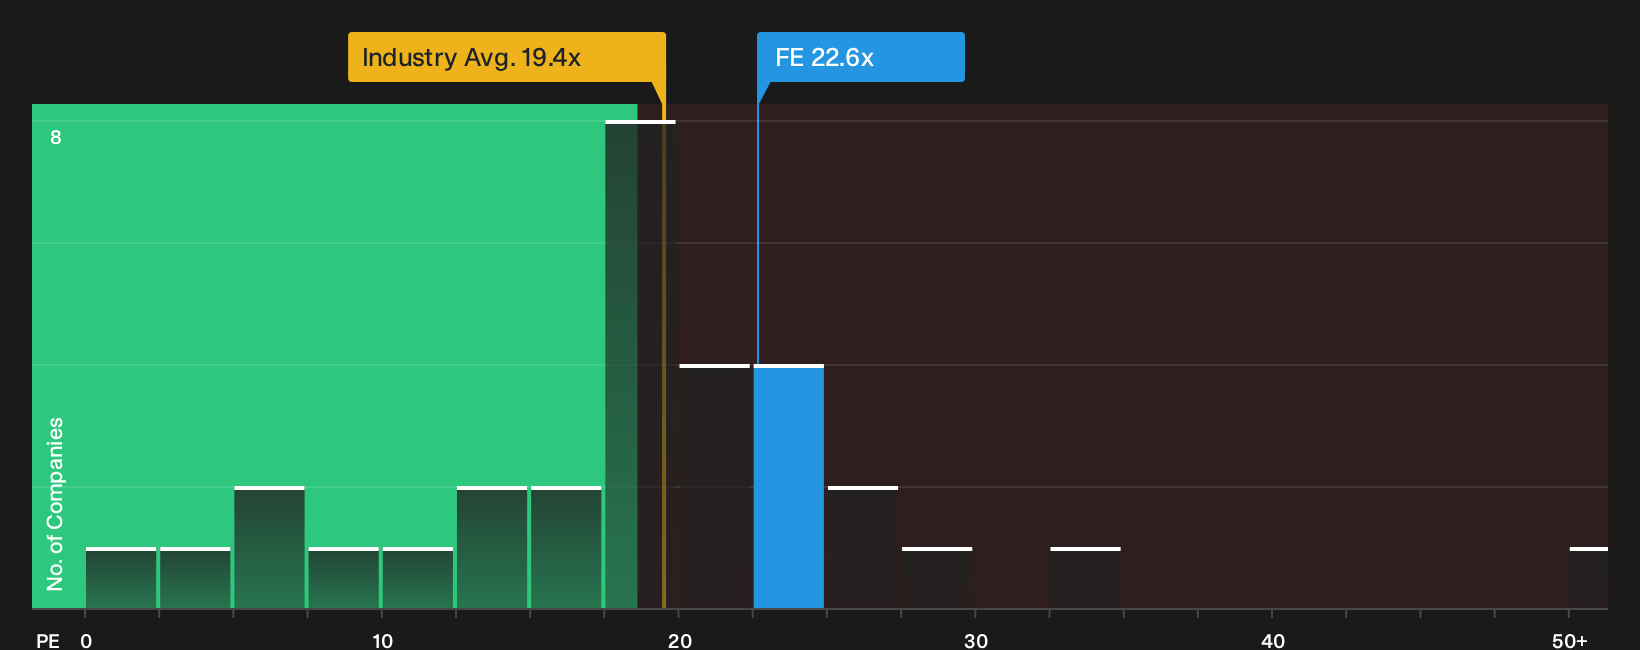
The DCF based fair value of $51.42 presents FirstEnergy as modestly undervalued. The P/E ratio tells a stricter story. At 22.6x earnings, the stock trades above the US Electric Utilities industry at 19.4x, above peer averages at 13.7x, and above a 21.2x fair ratio that our regression suggests the market could move toward. That gap narrows the margin of safety and raises a simple question for investors: Is the premium worth paying if sentiment cools or earnings fall short of forecasts?
To see how this compares with a valuation check anchored directly to earnings multiples, take a closer look at See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on FirstEnergy have probably come through clearly enough, so act while the data is fresh and build your own view using 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond FirstEnergy?
Do not stop with a single ticker. Broaden your watchlist using the Simply Wall Street Screener so your next opportunity is not one you only spot in hindsight.
- Target potential mispricing by scanning companies that score well on quality and valuation through the 30 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses flagged as potential 5 dividend fortresses.
- Prioritize resilience by filtering for companies in the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com