


EN
BP (LSE:BP.) Q3 Results Highlight Profit Strength And Write Down Risk
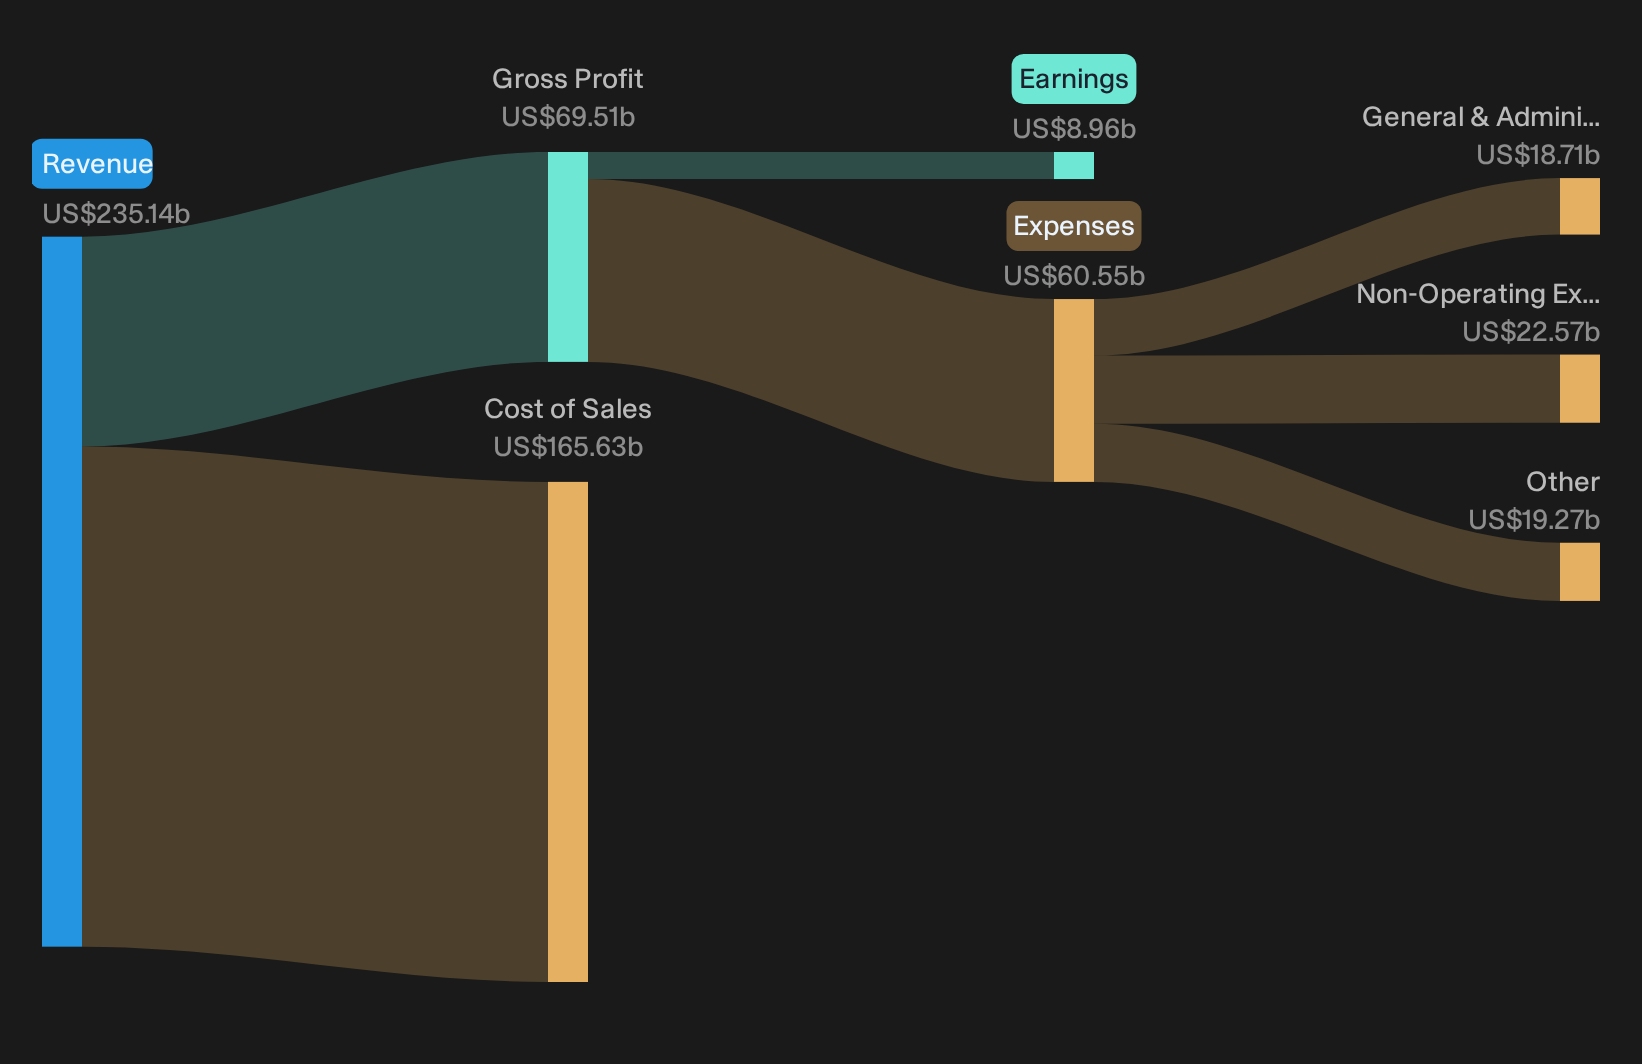
BP stock closed Friday at £6.27, slightly softer over the past week but still ahead over one and three months. That muted move masks a punchy Q3 2026 print. Basic earnings per share landed at US$0.30 and net income excluding one off items reached US$4.7b, both underpinned by very low production costs of US$6.54 per barrel of oil equivalent.
Short term traders saw a drifting share price. Longer term holders are now weighing a stronger profit run rate against mixed valuation signals and cautious multi year forecasts that already point to declining revenue and earnings.
Like the tight BP production costs but uneasy about forecasts that already bake in weaker earnings ahead? Screen for companies that combine efficient operations with stronger forward expectations in our 5 resilient stocks with low risk scores
Q3 2026 BP Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$67,857m vs. US$47,989m (higher reported top line year on year)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$4,696m vs. US$1,161m (strongly higher reported profit run rate)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.3019 vs. US$0.0748 (sharply higher earnings per share on a quarterly basis)
- Average Production Cost per BOE (Q3 2026 vs. Q3 2025): US$6.54 vs. US$6.19 (production unit costs held in a tight range)
Earnings grab the headlines, but the cash that actually comes through the door is what many valuation focused investors watch most closely.
Looking at BP's cash generation rather than the accounting profit alone, the stock could be a whopping 38% undervalued.
BP growth story: execution milestones under the microscope
Optimists argue BP can turn project delivery and tech driven savings into a structurally stronger business model.
"Analysts expect BP to keep leaning on project execution, cost reduction and technology deployment so that margins and cash generation remain well supported by high plant reliability, strong cash flow and a larger reserve base."
Q3 shows useful proof points. Earnings and basic EPS were sharply higher year on year, helped by very low US$6.54 per BOE production costs and strong refining and trading income. Net debt fell by about US$10b to US$13.9b, giving the balance sheet more breathing space. Management also flagged stable upstream volumes and high refinery utilization, both consistent with the reliability part of the story.
BP risk story: impairments and cost leakage still biting
On the flip side, BP still needs to show that transition missteps and cost friction are not eroding that same investment case.
"The earlier risk of capital being tied up in lower returning transition projects is still live, and the roughly $4.8b of recent after tax impairments in biogas and renewables show that further write downs in the gas and low carbon portfolio remain possible, which could weaken BP's earnings and dilute returns on invested capital."
Q3 results echo this concern. Around US$4b of losses tied to underperforming transition assets weighed on the quarter, even alongside record profit. Management also admitted structural savings are not yet flowing clearly to the bottom line, with underlying operating spend proving sticky. That mix, strong operating profit but continuing write downs and cost drag, keeps the bear case alive on execution risk.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt For Quiet Mispricings
BP reports strong earnings while the share price moves sideways. The real opportunity is hunting for stocks that could be undervalued before the market corrects them.
- Company 1 - 27% below our estimate - convert a long dated defence order book into higher margin projects as operations improve.
- Company 2 - 43% below our estimate - roll out an AI assisted technology stack so savings and SME banking products launch with limited extra spending.
- Company 3 - 47% below our estimate - open new bowling and family entertainment centres while using booking and pricing tools to support attractive returns.
Those are three of them. See all 14 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com