


EN
Advantage Energy (TSX:AAV) Could Be 15% Undervalued Following Its Q3 Profit Turnaround
Why Q3 2026 Changed the Conversation Around Advantage Energy
Advantage Energy (TSX:AAV) has just shifted the story with its third quarter 2026 update, moving from a prior loss to a C$56.43 million profit while also stepping up production and trimming net debt.
Investors have responded quickly to the Q3 rebound, with Advantage Energy’s share price up 5.12% over one day and 13.31% over 30 days, even though the year to date share price return is still down 2.05% and the 5 year total shareholder return sits at 47.88%. This points to momentum rebuilding on top of a longer record of gains.
Scan beyond Advantage Energy and see how it stacks up against 4 high quality undervalued stocks that are also showing fresh momentum and disciplined capital returns.
Advantage Energy now trades at a sizeable discount to both intrinsic estimates and analyst targets after a sharp earnings rebound and buyback. Is that genuine mispricing, or a market warning about risk that deserves respect?
Most Popular Narrative: 15% Undervalued
Against the last close at CA$11.49, the most followed narrative pegs Advantage Energy’s fair value at CA$13.54, framing today’s discount as a test of whether investors trust the current plan.
Planned share repurchases of up to 5% of common shares in 2026 and an additional 10% in 2027 under the renewed normal course issuer bid point to a shrinking share count. This can increase cash flow per share and earnings per share if corporate cash generation holds up.
See why 9 investors see Advantage Energy as 15% undervalued.
Result: Fair Value of CA$13.54 (UNDERVALUED)
Still, the Advantage Energy story can be knocked off course if AECO gas prices weaken again or if NGTL pipeline constraints pressure realized pricing and cash generation.
Find out about the key risks to this Advantage Energy narrative.
Another View On Advantage Energy’s Valuation
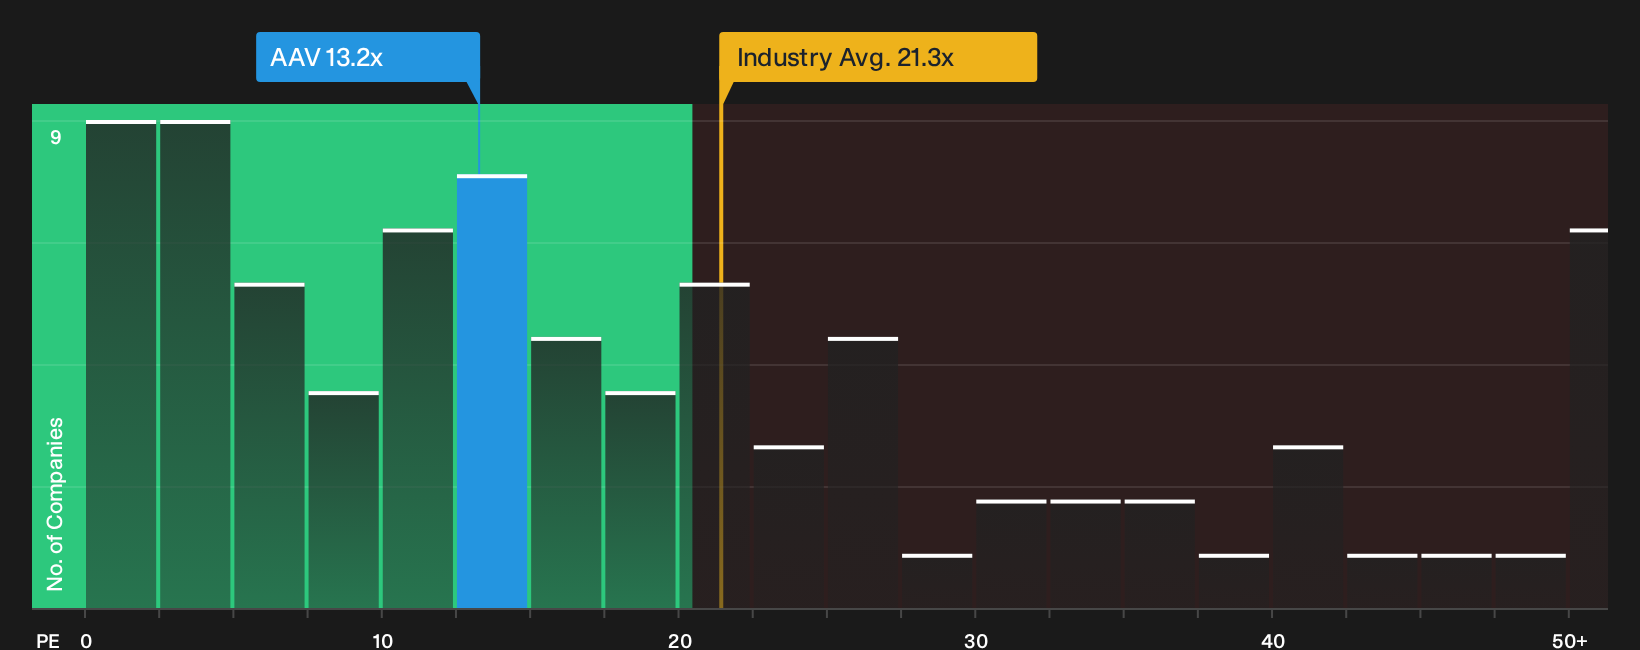
The earlier narrative leans on discounted cash flows and a fair value of CA$13.54, with Advantage Energy at a 72.9% discount to an internal future cash flow value of CA$42.45. Yet the P/E story is less one sided. The stock trades on 13.2x earnings, above a fair ratio of 11.6x, even though that multiple is well below the Canadian Oil and Gas industry at 21.3x and a peer average of 30.4x. Is the market signaling hidden risk, or is it just slow to close the gap?
To stress test this earnings based view against the current price, take a closer look at the detailed valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or clear opportunity? If you want to move faster than the crowd, review the full picture of risks and upside in the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Advantage Energy?
Do not stop at Advantage Energy. Broaden your watchlist now, compare different return profiles, and give yourself more options before the next round of market moves.
- Target potential mispricing by scanning for companies with solid fundamentals and appealing valuations through the 4 high quality undervalued stocks.
- Lock in income focused opportunities by reviewing a curated set of high yield stocks using the 3 dividend fortresses.
- Prioritise resilience by filtering for businesses with clean balance sheets and robust fundamentals in the list of solid balance sheet and fundamentals (6 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com