


EN
Monarch Casino (MCRI) Stock Slips After Q3 Results Despite Strong Margins
Monarch Casino & Resort entered this Q3 2026 report with a strong reputation for quietly compounding earnings while the stock has slipped, down about 11.7% over the past three months. Fresh numbers show another solid quarter of profitability, with basic earnings per share of about US$1.80 on revenue of roughly US$146.3 million. However, the share price eased 1.1% on the first full trading day after the release. The real story sits in the margins, where net profit over the last year has run at roughly 20.4%, far above where it was a year ago.
Love Monarch Casino & Resort's strong profitability but concerned about the recent share price weakness? Compare it with a curated group of resilient operators in our 29 resilient stocks with low risk scores
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$146.3 million vs. US$142.8 million (up about 2.4%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$32.0 million vs. US$31.6 million (up about 1.4%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.80 vs. US$1.73 (up about 4.3%)
- Net Profit Margin (Trailing 12 Months vs. Prior Year): 20.4% vs. 15.3% (higher profitability on recent results)
Earnings jumped faster than revenue and margins widened again. Ask Charlie what makes Monarch Casino & Resort look undervalued.
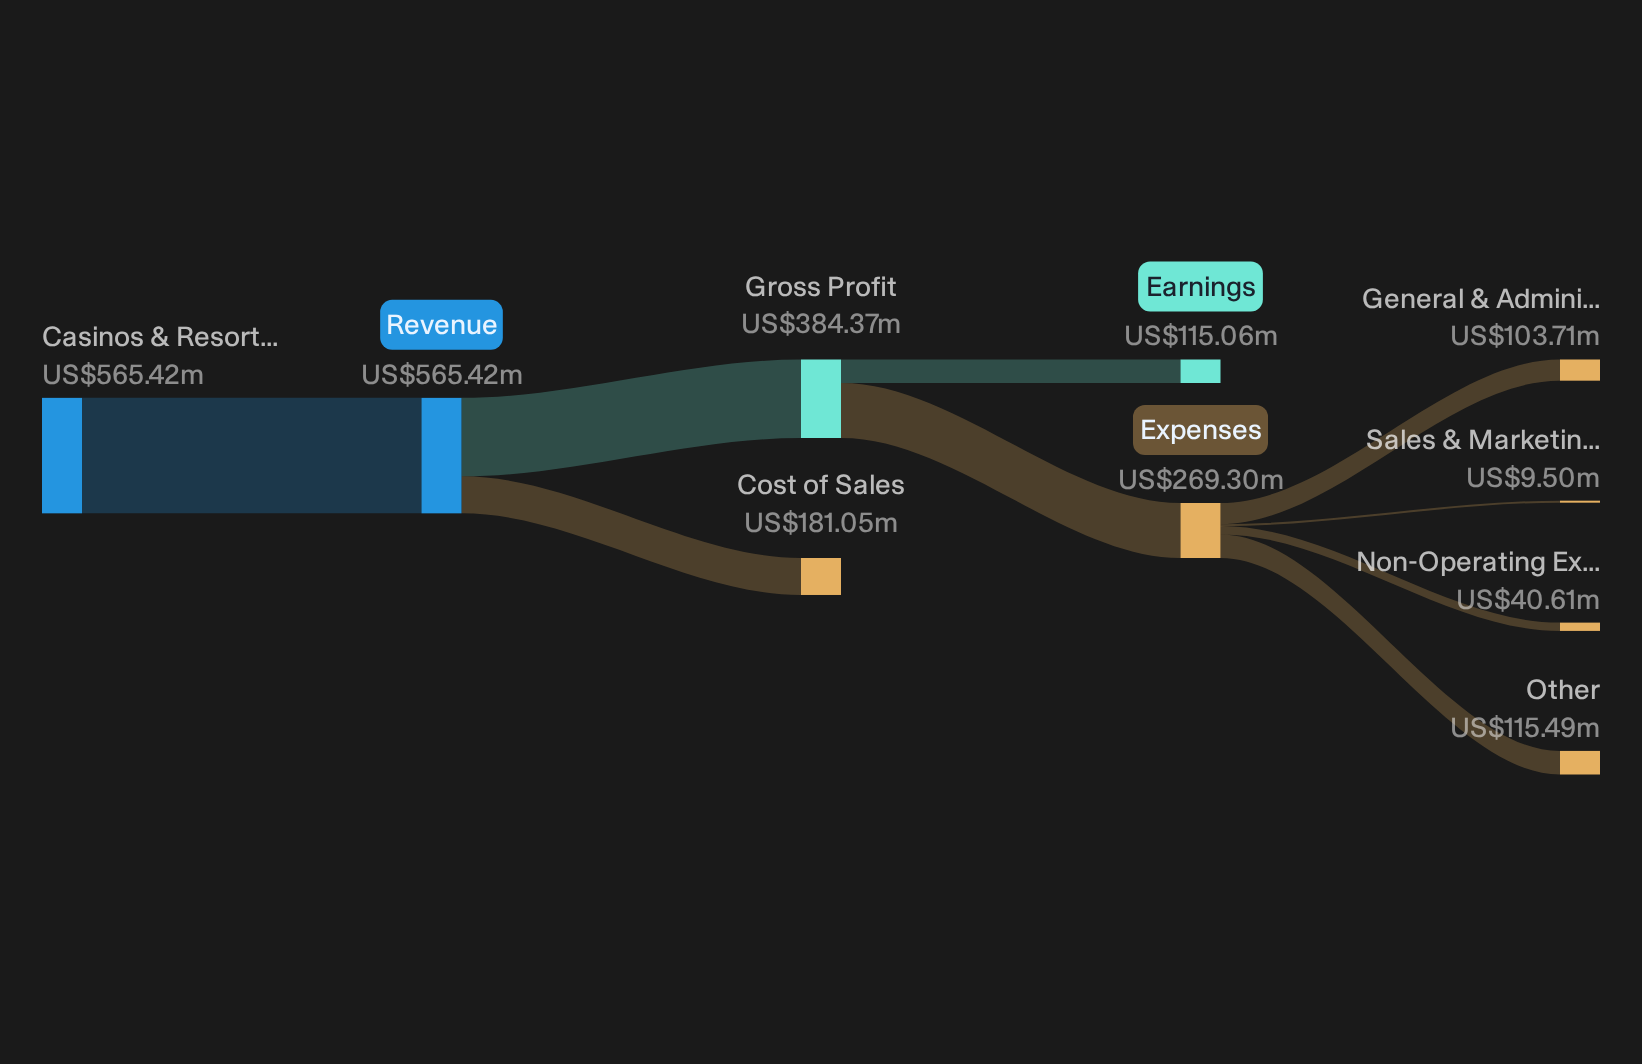
Monarch bullish story leans on quality earnings
For anyone leaning optimistic on Monarch Casino & Resort, this update gives some support. Net revenue, net income and basic EPS all moved higher versus Q3 2025, while the trailing 12 month net margin sits well above the prior year. That mix fits an experience focused regional operator that is extracting more profit from every dollar of sales. A debt free balance sheet and sizeable cash position from recent updates also backs the idea of a resilient regional resort platform with room to fund dividends, buybacks and potential deals from a position of strength.
Short term pressure keeps bearish worries alive
There is still ammo for the cautious view. The share price has slipped over the past 3 months and eased again after the Q3 release, even with record revenue headlines in recent coverage. That disconnect can speak to concerns about modest top line growth, concentrated exposure to two markets and the unresolved labor class action at Black Hawk that could influence costs. Acquisition speculation also cuts both ways. Investors get upside optionality, but any sizeable deal could test Monarch Casino & Resort’s disciplined track record and introduce integration risk.
Are analysts convinced Monarch Casino & Resort can keep turning a debt free balance sheet into shareholder friendly capital returns? Check the consensus price target analysis for Monarch Casino & Resort.Hunt Quiet Mispricings In Plain View
Monarch Casino & Resort just showed how a solid set of numbers can still sit alongside a drifting share price. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 44% below our estimate - focuses on rolling out cash recycling ATMs and compact branch-in-a-box units for banks modernizing physical networks.
- Company 2 - 38% below our estimate - expands high horsepower engine capacity to back multi-year power needs for data center and infrastructure projects.
- Company 3 - 28% below our estimate - sells grid testing equipment that utilities deploy as electrified transport and modernization programs reshape power infrastructure.
Three companies from the same screener. Open every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com