


EN
Stora Enso (HLSE:STERV) Stock Lags A Stronger Q3 Earnings Rebuild
Stora Enso Oyj came into this Q3 2026 earnings print with a stock that had drifted lower for months, down roughly 5% over both the past 30 and 90 days, and closing at €9.54 just as the results hit. The forestry and packaging group then reported adjusted EBIT of €161m with a margin above 7% and operating cash flow of €245m, alongside net debt reduced to €2.5b. The share price has not yet reflected that margin rebuild and balance sheet work, creating a clear gap between the long term thesis and the immediate reaction.
Love the margin rebuild and cash generation at Stora Enso but uneasy about whether the balance sheet progress is enough for your portfolio? Compare this earnings story with our list of solid balance sheet and fundamentals stocks (200 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026): €2,280 million vs. €2,283 million in Q3 2025 (broadly flat)
- Net Income (Excl. Extra Items, Q3 2026): €22 million vs. €198 million in Q3 2025 (fell about 89%)
- Basic EPS (Q3 2026): €0.01 vs. €0.25 in Q3 2025 (declined about 96%)
- Adjusted EBIT (Q3 2026): €161 million vs. approximately €126 million in Q3 2025 (management indicates a 28% improvement)
Stora Enso is carving out Bergslagets Skogar to ‘unlock value’. Ask Charlie what Stora Enso’s demerger means for earnings.
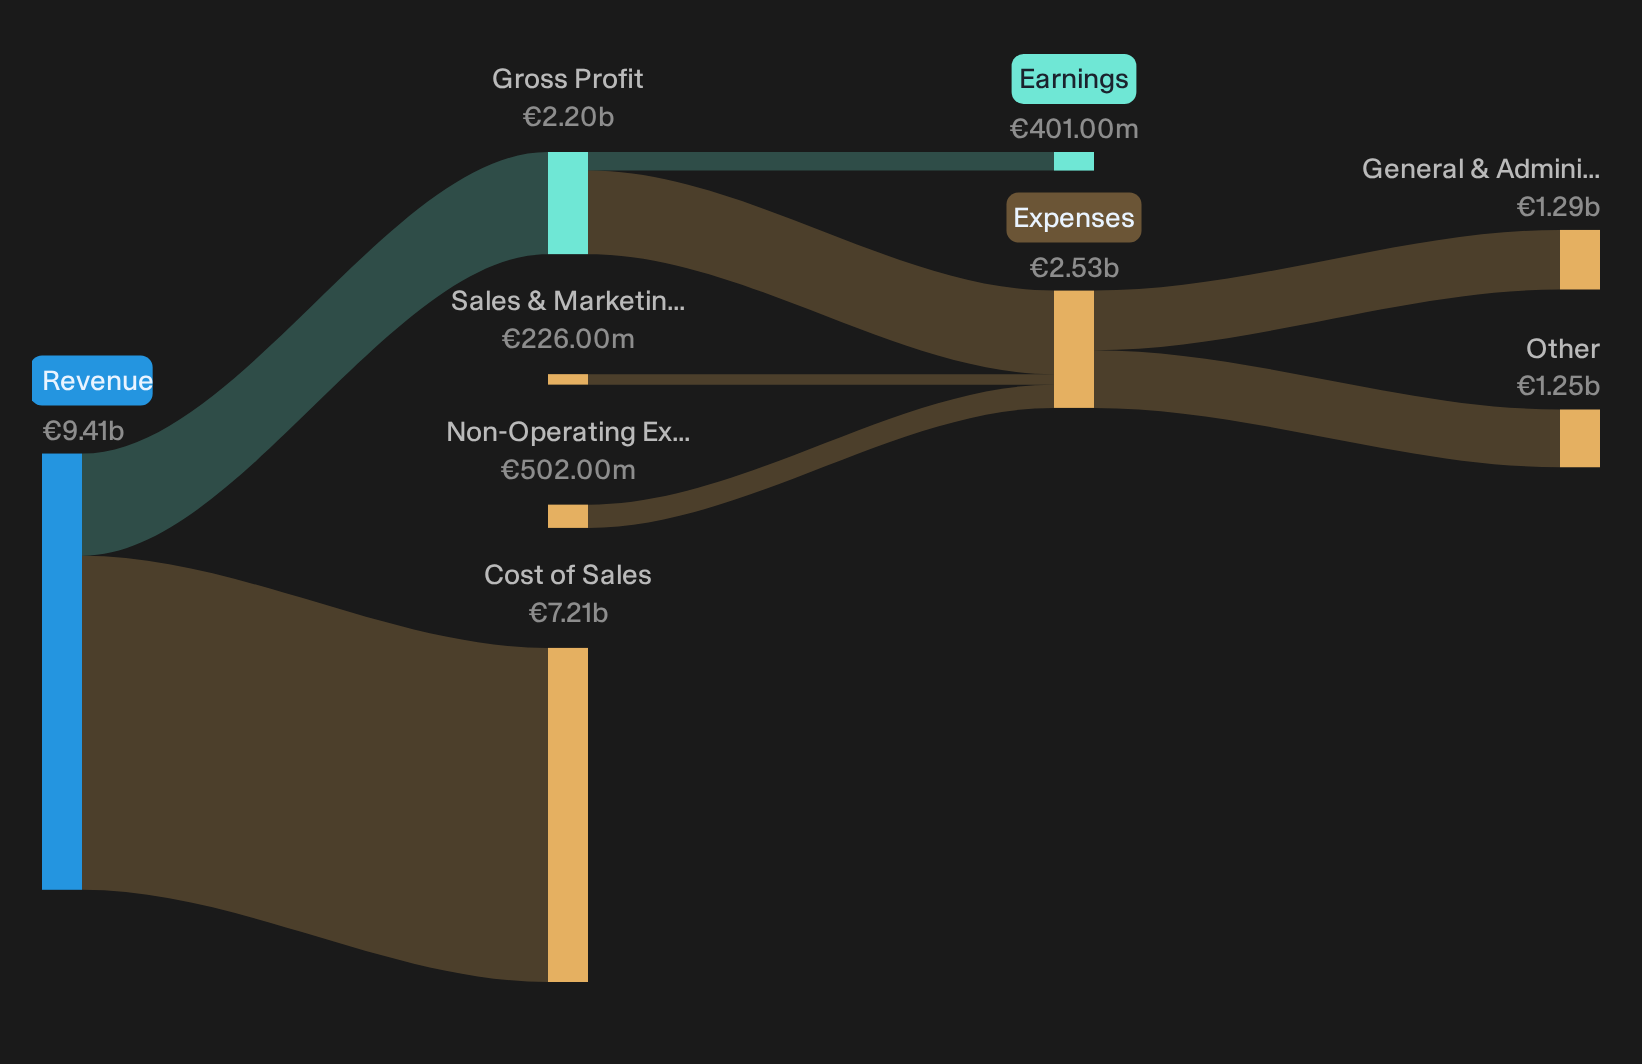
Evaluating Stora Enso’s Execution-led Bull Case
The upbeat story on Stora Enso hinges on portfolio simplification and self help translating into a leaner, more cash generative group.
"The main thing that has to go right is continued delivery on the EUR 500 to 700m value creation initiatives while the Swedish forest assets separation and Oulu consumer board line ramp-up are executed without eroding the improving EBIT trend."
Q3 points in the right direction. Adjusted EBIT reached €161m with a margin above 7% and volumes, cost actions and pricing all contributing. Operating cash of €245m and net debt down to €2.5b suggest the value creation program is showing through in both profitability and leverage, while the Bergslagets Skogar separation and Oulu ramp proceed without obvious earnings damage so far.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Stora Enso Bear Case: Cost Fears Still Largely Theoretical
The harsher view on Stora Enso argues that rising carbon and wood costs could overwhelm internal fixes and keep profitability stuck.
"Although Stora Enso highlights thousands of efficiency programs and identified value creation actions, the upcoming loss of over €50 million of free CO2 allowances from tighter EU emissions rules could more than absorb these savings and cap future EBIT margin expansion and net margin improvement."
Q3 adjusted EBIT margin above 7% and a €35m uplift in adjusted EBIT built mainly on volumes and variable cost improvements do not yet show that squeeze. Wood costs even helped Consumer Packaging. The risk is real but still sits ahead of the reported numbers rather than inside them.
Hunt For Mispriced Earnings Stories
Stora Enso Oyj shows how execution and market reaction do not always align. The real opportunity is finding stocks that could be undervalued before the market closes that gap.
- Company 1 - 23% below our estimate - uses cheaper inputs and richer prepared food offerings to tilt earnings toward higher margin branded products.
- Company 2 - 29% below our estimate - scales a low cost digital banking platform as customer counts, revenue per user and new geographies all build operating leverage.
- Company 3 - 48% below our estimate - co-designs complex hardware with clients through a sketch to scale model that embeds its know how into long product lifecycles.
Three companies from the same screener. Open all 194 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com