


EN
Learn Why The Bull Case For NXP Semiconductors Stock Could Change Following Earnings Beat
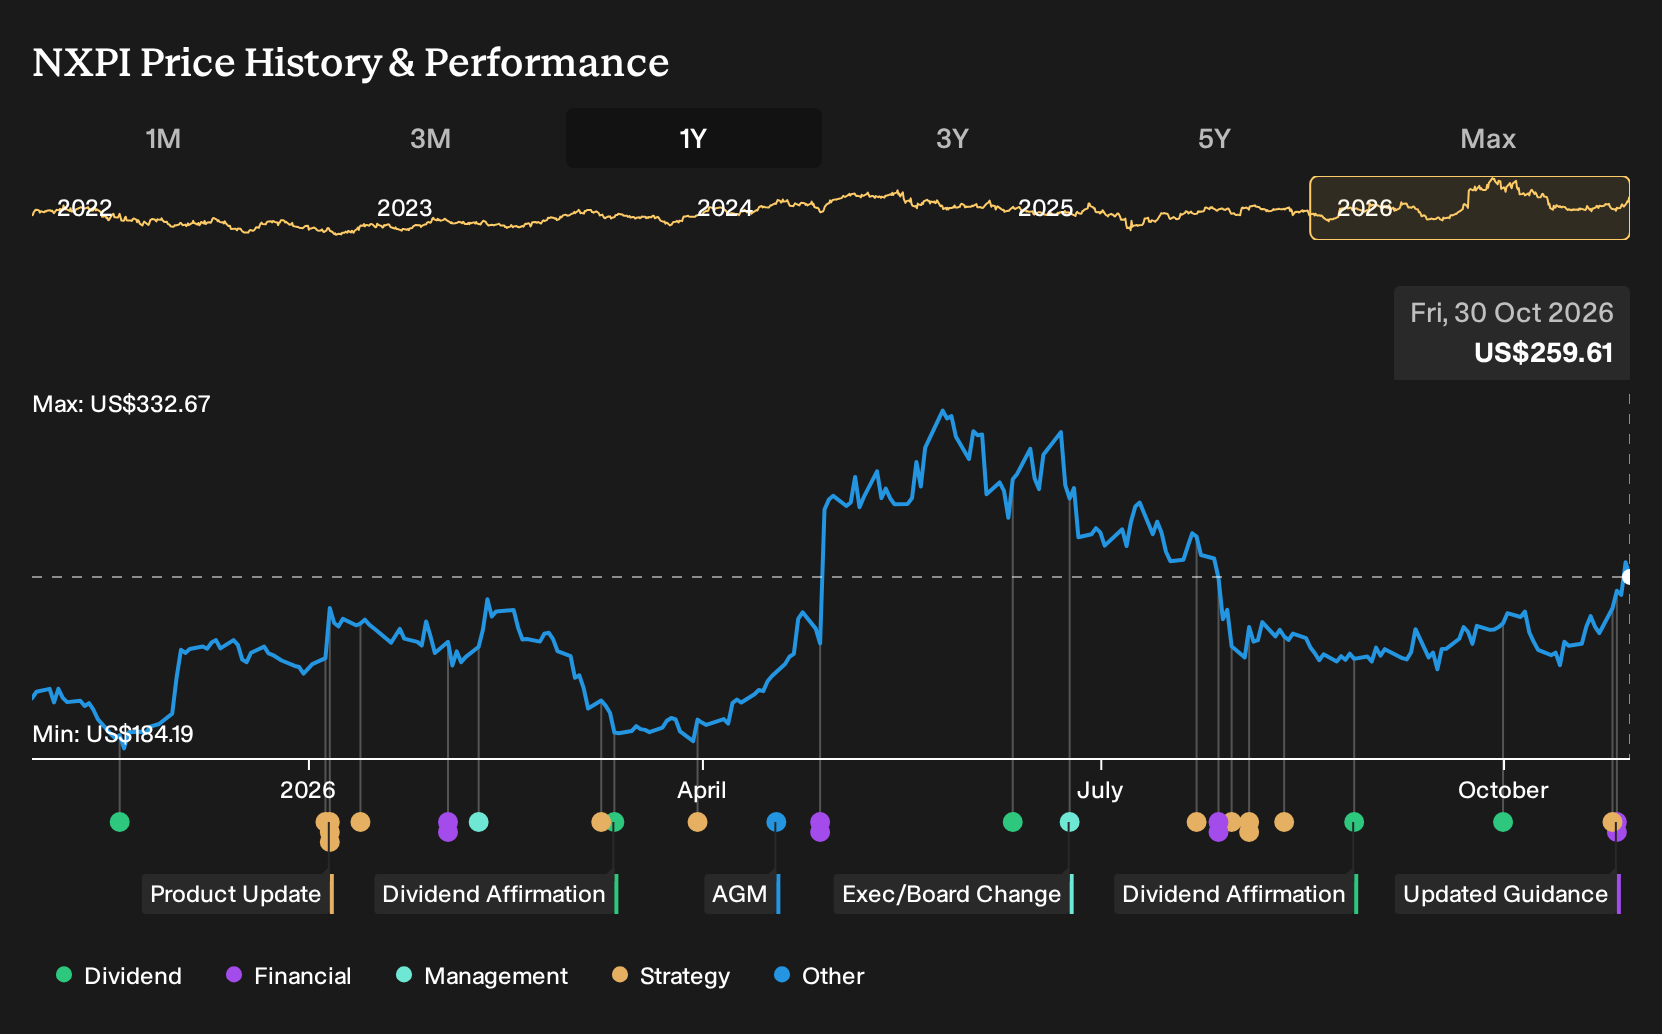
- NXP Semiconductors reported Q3 2026 earnings with higher diluted EPS from continuing operations and issued Q4 guidance that targets US$3.75b to US$3.95b in revenue, together with a projected operating income range of US$1.17b to US$1.30b and diluted EPS guidance of US$3.36 to US$3.79.
- The new partnership with Volkswagen Group to use NXP’s S32K5 microcontrollers in future software-defined vehicle architectures highlights how the company is tying its automotive portfolio directly to long term zonal control designs across multiple brands and segments.
- This article examines how NXP Semiconductors' investment narrative is influenced by this updated guidance and the Volkswagen software-defined vehicle partnership.
Scan NXP Semiconductors' auto and chip momentum against a curated set of peers by checking out 54 AI infrastructure stocks as potential beneficiaries of the same hardware and software tailwinds.
NXP Semiconductors Investment Narrative Recap
For NXP Semiconductors, the core belief is that automotive, industrial and data center demand for its processors and microcontrollers keeps building enough to absorb any bumps in Chinese auto or inventory trends. The latest Q4 2026 guide for US$3.75b to US$3.95b of sales with US$1.17b to US$1.30b of operating income keeps that operational story intact rather than redefining it.
The more immediate swing factor remains how cleanly automotive orders normalize as Tier 1 customers refill toward targeted inventory levels. The biggest operational risk still sits in a potential auto correction in China or a large edge AI deal that stretches the balance sheet. Neither of these possibilities is fundamentally resolved by Q3 earnings or guidance.
The Volkswagen Group partnership around NXP Semiconductors S32K5 microcontrollers looks most relevant to this earnings update because it ties directly into the software defined vehicle catalyst that management keeps highlighting. Zonal controllers that replace multiple standalone ECUs align with the idea of rising semiconductor content per car, which supports the auto thesis investors already focus on.
That agreement also concentrates execution risk. NXP now needs to deliver on complex SDV rollouts with both Volkswagen and the RV Tech joint venture, while also handling possible Chinese auto softness and keeping capital discipline, especially if an Ambarella style edge AI transaction eventually appears. For investors, SDV traction and any signs of auto destocking sit at the center of the watchlist.
NXP Semiconductors Analyst Assumptions in Focus
Analyst models around NXP Semiconductors put numbers around the auto-heavy narrative that management describes on earnings calls. The current consensus framework leans on revenue growing by 10.2% a year over the next three years and on profit margins rising from 22.6% today to 26.5% by around 2029. Together, these assumptions shape how much operating leverage investors expect from the shift toward software-defined vehicles and higher value industrial processors.
On earnings, the group of covering analysts projects profit of US$4.7b by 2029 versus US$3.0b today. That implies an earnings increase of about US$1.7b over the period on their base case, with a more optimistic cohort modeling as much as US$5.3b. These figures matter because they feed directly into the P/E math that underpins price targets, including the move from a current multiple of 19.3x to a future 23.5x against those 2029 earnings that some models use to justify upside.
The same set of forecasts assumes only modest dilution, with shares outstanding rising by about 0.19% per year over the next three years. For you as an investor, that means most of the projected earnings per share story in NXP Semiconductors comes from absolute profit growth and margin expansion rather than heavy buybacks or big changes in the share count.
NXP Semiconductors' narrative projects US$17.6b revenue and US$4.7b earnings by 2029. This requires 10.2% yearly revenue growth and an earnings increase of about US$1.7b from US$3.0b today.
Uncover why NXP Semiconductors' fair value indicates a 16% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle you may want to consider is the bullish view that NXP Semiconductors turns its software defined vehicle pipeline into much faster expansion than consensus. The most optimistic analysts were already modeling revenue of about US$19.4b and earnings of US$5.3b by 2029 before this Volkswagen news, so their narrative could shift further once they update models.
Explore 5 other NXP Semiconductors fair value estimates, including one that suggests a potential upside of as much as 51% from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so consider trusting your own research and judgment.
- A great starting point for your NXP Semiconductors research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NXP Semiconductors. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review NXP Semiconductors' overall financial position at a glance.
Looking For More Investment Ideas Beyond NXP Semiconductors?
If the NXP Semiconductors story has sharpened your thinking about where to put fresh capital to work, it can help to line it up against a wider field of candidates that share some of the same quality markers.
- For investors who want income plus resilience, review potential yield opportunities that also emphasise balance sheet strength through 5 dividend fortresses.
- If capital preservation ranks high on your list, scan companies with steadier risk profiles and stronger fundamentals using 30 resilient stocks with low risk scores.
- When you are hunting for underfollowed potential, sort through financially solid businesses that have not yet attracted broad attention via 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com