


EN
Does Wynn Resorts (WYNN) Look Reasonable After A 39% Slide?
Wynn Resorts shares have slid sharply this year, and with the price now near recent lows, the key issue for you is whether that drop lines up with what the casino operator is currently earning. With the stock under pressure as headlines focus on debt, strikes and sector weakness, the question is how much of that strain is already reflected in the earnings that underpin today’s valuation.
- The stock is down 39.1% year to date. This puts the focus squarely on whether the current earnings base can support the move lower in Wynn Resorts’ market value.
- Union action at Encore Boston Harbor has hit revenue and likely increased short term costs. This can affect how investors think about Wynn’s future margins and the timing of cash flows that its earnings need to justify.
- The analysts covering Wynn Resorts have run their own numbers. See what analysts think Wynn Resorts's shares could be worth.
The issue now is whether Wynn Resorts’ latest share price is adequately backed by the earnings power that the business is generating today.
If you want more context around Wynn Resorts and the pressure on highly leveraged gaming operators, it can help to compare this situation with companies in other areas using 30 resilient stocks with low risk scores.
Does Wynn Resorts Look Fairly Valued on Earnings?
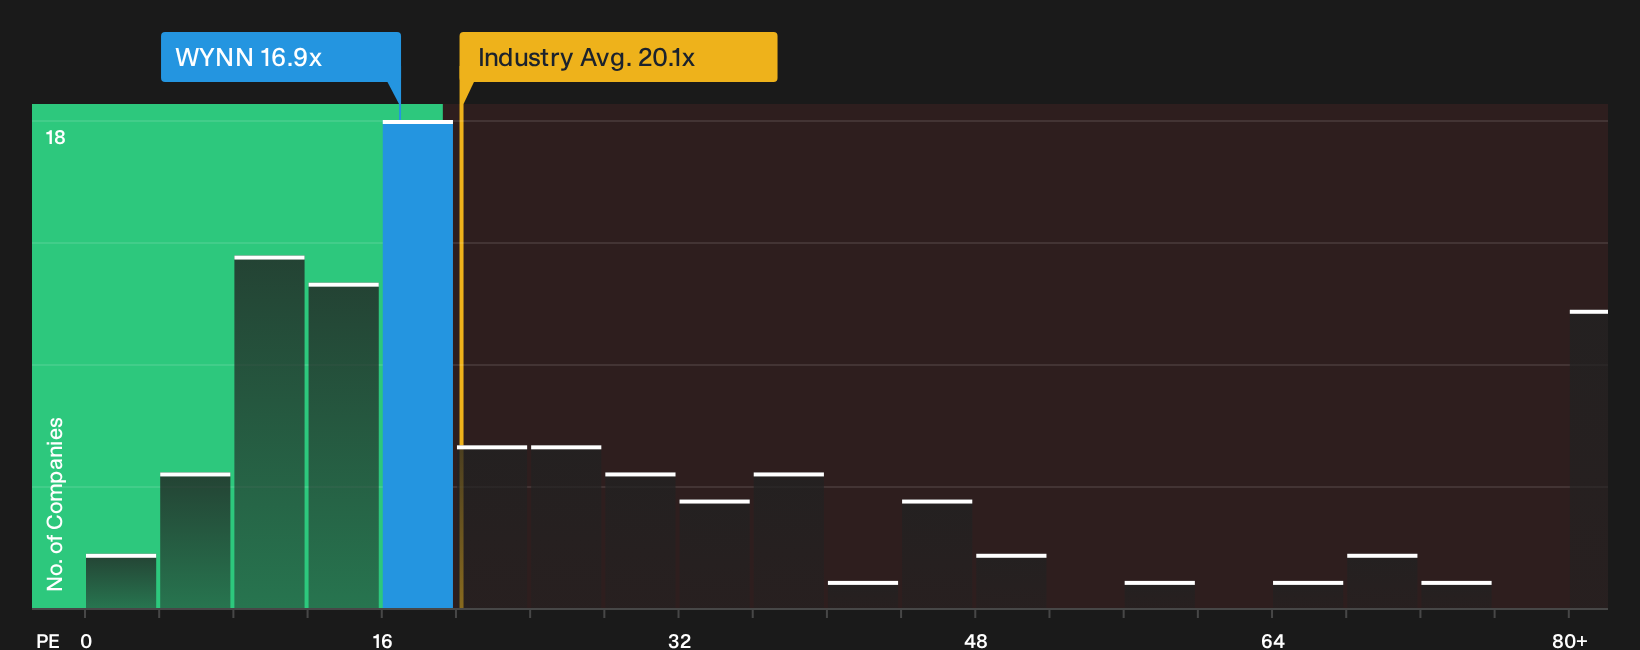
The P/E ratio suits Wynn Resorts because investors often focus on earnings power for mature casino operators. The stock trades on a P/E of 16.9x, compared with a hospitality sector average of 20.1x and a peer mark of 13.1x. On Simply Wall St’s tailored yardstick for this business, the current multiple sits close to what that framework would expect given Wynn’s risk profile and cash generation.
Because the Encore Boston Harbor strike has weighed on revenue and raised short term costs, the P/E reflects a period when earnings carry clear labour and leverage questions. For you as a shareholder or potential buyer, the key judgment is whether those issues feel temporary or more entrenched, since that shapes how supportive a roughly mid teens earnings multiple really is for Wynn Resorts at this price. Explore the numbers behind Wynn Resorts's P/E valuation.
The Wynn Resorts Narrative: What Would Justify Today's Price?
Narratives for Wynn Resorts sit between the current P/E puzzle and the earnings story investors are trying to test. They spell out which combinations of future growth, margins and cash generation would need to play out for the stock to be worth materially more or less than today. Where a simple ratio or model offers a single valuation number, these lay out the future that number leans on, so you can watch how the reality lines up over time.
One of the top community narratives on Wynn Resorts: 27% undervalued
"The main thing that has to go right is that Wynn Resorts converts its premium oriented expansion pipeline in Macau, the U.S., and the UAE into profitable, resilient cash flow..."
Discover why this Narrative puts Wynn Resorts at 27% undervalued.
The price of Wynn Resorts is only one piece of your decision
Share price, earnings and headlines only tell part of the story for Wynn Resorts, since separate checks on the business have raised concerns that deserve your attention before you commit fresh capital. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com