


EN
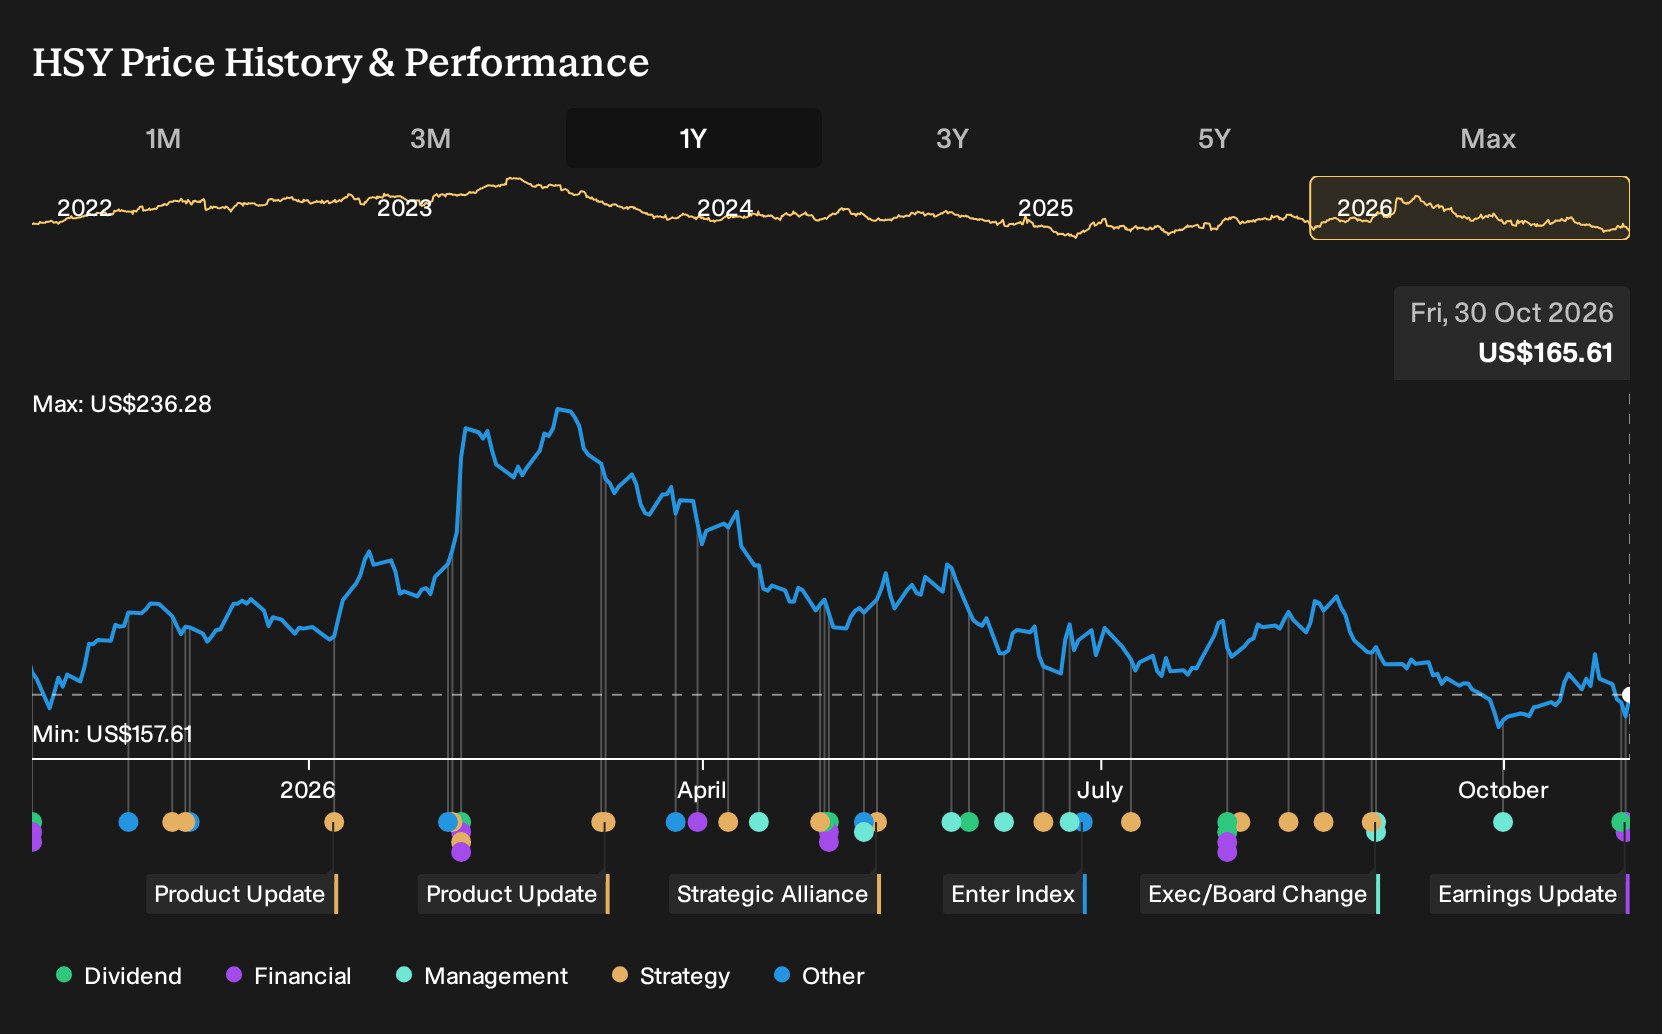
Does Raised 2026 Outlook Change The Bull Case For Hershey (HSY)?
- Hershey raised its full year 2026 outlook after reporting third quarter results that showed higher sales of US$3,275.51 million and sharply higher earnings, supported by pricing and tariff refunds, while still flagging consumer and cost pressures.
- The surge in profitability came even as North American confectionery volume fell and salty snacks faced supply constraints. This underscored how much Hershey is leaning on pricing, efficiency and a heavier product pipeline rather than pure volume growth.
- We will now look at how Hershey's higher 2026 earnings guidance, driven by stronger profit power, could reshape its investment narrative.
Hershey Investment Narrative Recap
To own Hershey, you need to believe its pricing power, brand strength and snacking expansion can offset softer volumes and consumer pushback on higher candy prices. The raised 2026 earnings guidance, helped by tariff refunds and strong Q3 profit, supports that profitability story but does not fully resolve concerns about volume declines and market share pressure.
The key near term catalyst is whether 2027 product launches and pack sizes stabilize demand as shoppers trade down and shift channels. The biggest risk remains reliance on pricing while North America confectionery volumes fall and salty snacks are constrained by capacity and logistics, which could pressure growth once pricing benefits fade.
The updated 2026 outlook is the most relevant fresh data point. Management now targets about 5% net sales growth and reported EPS of US$8.00 to US$8.26, with reported EPS growth of 84% to 90%, including tariff refunds already received. That reset frames Hershey as a profit power story built on pricing, efficiency and mix.
For you as an investor, the question is how repeatable that earnings level is once one off tariff benefits roll out of the base and cocoa, freight and other inputs remain a swing factor. Execution on salty snacks capacity, the larger 2027 pipeline and demand shaping in lower cost lines now sits at the center of Hershey’s catalyst and risk balance.
Hershey's narrative projects US$13.1b revenue and US$2.1b earnings by 2029. That assumes 2.5% yearly revenue growth and about a US$0.6b earnings increase from US$1.5b today.
Uncover how Hershey's fair value indicates a 17% potential upside to its current price before other investors close that gap.
Exploring Other Perspectives
One alternate view on Hershey focuses heavily on cocoa cost risk. The most cautious analysts were forecasting revenue of about US$13.0b and earnings near US$1.9b by 2029 before this guidance update, and they see less room for margin relief. Their more muted earnings path shows how sharply expectations can differ, so it can be useful to compare several narratives before considering how this latest outlook might influence your own.
Explore 6 other Hershey fair value estimates, including one that suggests as much as 52% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hershey research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hershey. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hershey's overall financial health at a glance.
Looking for more investment ideas beyond Hershey?
Once you have a view on Hershey, it can help to line it up against other opportunities that match your risk tolerance, dividend needs and balance sheet preferences. The Simply Wall St Screener gives you a quick way to scan for stocks that fit those filters so you can build a watchlist that actually matches how you want to invest.
- If you want income with staying power, shortlist potential high yield candidates by starting with 5 dividend fortresses. These combine payouts with more resilient profiles.
- If your priority is limiting downside risk, focus your research on a 30 resilient stocks with low risk scores screener and see which businesses score better on stability and financial strength.
- If you are hunting for quality that the market may be overlooking, start your stock hunt with a 18 high quality undiscovered gems screener and see which tickers deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com