


EN
Akamai Technologies (AKAM) Rolls Out New AI Stack, Is The Valuation Still Cheap?
Akamai Technologies (AKAM) just rolled out Akamai Inference and Akamai Agent Sandbox, two core AI stack offerings that let enterprises run and secure advanced models and agents on its cloud and global network.
Akamai Technologies has been through a choppy few months, with the share price down 14.87% over the past 30 days and 21.34% over 90 days, even as launches like the Anthropic partnership and the new AI stack keep attention on its cloud ambitions. Despite that pullback, the stock still has an 8.95% year to date share price return and a 23.46% total shareholder return over 1 year. As a result, recent weakness looks more like cooling momentum after a stronger run than a story of long term value creation reversing.
Scan beyond Akamai Technologies and line up other AI infrastructure players using our curated list of 54 AI infrastructure stocks.
Akamai Technologies now looks like a solid AI infrastructure story trading at a very different level from a few months ago. The real work starts with evaluating whether that recent reset leaves the valuation generous or still demanding.
Most Popular Narrative: 40% Undervalued
Akamai Technologies closed at $92.72, while the most followed narrative anchors fair value at $154.96. The gap between price and story is wide and built almost entirely on how its AI infrastructure build out plays through earnings and cash flows.
Active capital deployment toward cloud infrastructure growth, including an expected 2026 CapEx level of about 40% of revenue and roughly US$5.5b of planned Anthropic related CapEx supported by zero coupon convertible debt financing and new power sourcing arrangements, is intended to build a 95 to 105 megawatt AI infrastructure portfolio. Management expects this portfolio to deliver about US$22m in annual revenue per megawatt and support future cash gross margins in the mid 60s to mid 70s range.
See why 38 investors see Akamai Technologies as 40% undervalued.
Result: Fair Value of $154.96 (UNDERVALUED)
Still, the thesis can wobble if the capital heavy Anthropic build fails to hit targeted cash margins, or if legacy delivery declines outpace security and cloud gains.
Find out about the key risks to this Akamai Technologies narrative.
Another View on Akamai Technologies: Paying Up for Quality?
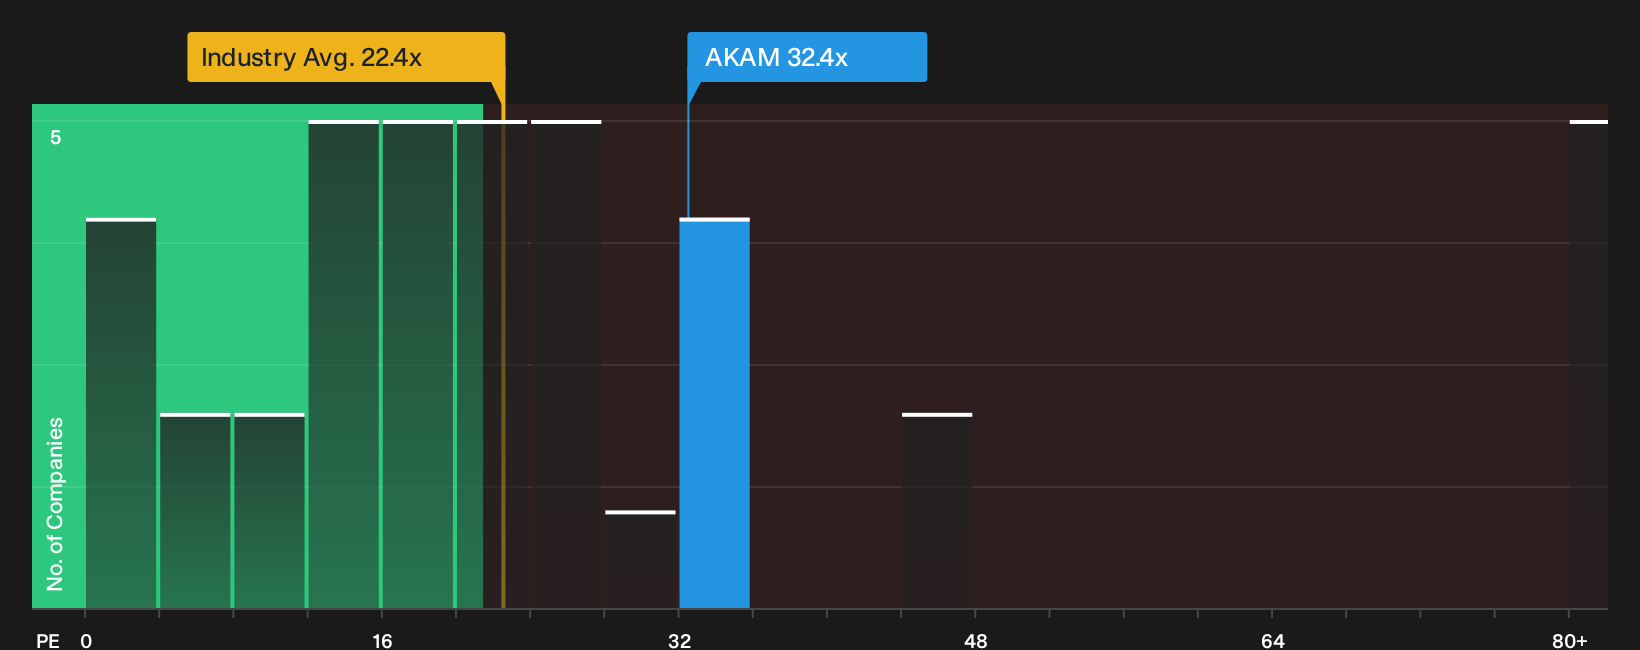
On price multiples, Akamai Technologies tells a different story. The stock trades on a P/E of 32.4x compared with 22.4x for the wider US IT group and 25x for peers, while the fair ratio is 36.4x. That leaves some upside implied, but also signals less room for disappointment.
For a closer look at how this P/E gap could cut both ways for future returns, including how it compares with the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Akamai Technologies feels familiar, do not wait for consensus to harden before you review the details yourself. Start by weighing both sides of the story with 2 key rewards and 1 important warning sign.
Looking for more Akamai Technologies style investment ideas?
If Akamai Technologies has your attention, do not stop here. Take a few minutes to scan other ideas that could suit your watchlist before markets move on.
- Target resilient value by focusing on companies that pair solid balance sheets with healthy fundamentals through our list of solid balance sheet and fundamentals (25 results).
- Spot potential mispricing by zeroing in on financially strong businesses trading below what their quality suggests using the 29 high quality undervalued stocks.
- Build a more defensive core by concentrating on companies with lower overall risk profiles through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com