


EN
Can Stellantis (BIT:STLAM) Stay Reasonable After Its Q3 Rebound?
Stellantis has rebounded sharply in recent weeks after a difficult stretch, which puts fresh focus on whether the current share price lines up with the revenue the group is generating across its global brands. With investors weighing product launches, cost cuts and cash flow goals, the open question is how much of the Stellantis sales story is already reflected in the stock.
- Over the past 3 years the share price has fallen 74.2%. This puts considerable weight on whether the present valuation can still be explained by the scale and durability of Stellantis automotive sales.
- Recent announcements around micromobility, aluminium intensive vehicle design and extended range electric models can influence how investors think about future revenue mix, profitability and the timing of cash returns from the Stellantis product pipeline.
- There is a second opinion on Stellantis worth weighing. See what analysts think Stellantis's shares could be worth.
The issue now is whether the Stellantis current market price is appropriately grounded in the level and quality of its sales.
If you want to test the same sales driven valuation question beyond Stellantis, it helps to compare this against other companies screened for 193 high quality undervalued stocks
Does Stellantis Look Undervalued on Sales?
P/S fits Stellantis because investors are currently focused on how much revenue the group can drive from its broad portfolio while cash flow and earnings targets are still in transition.
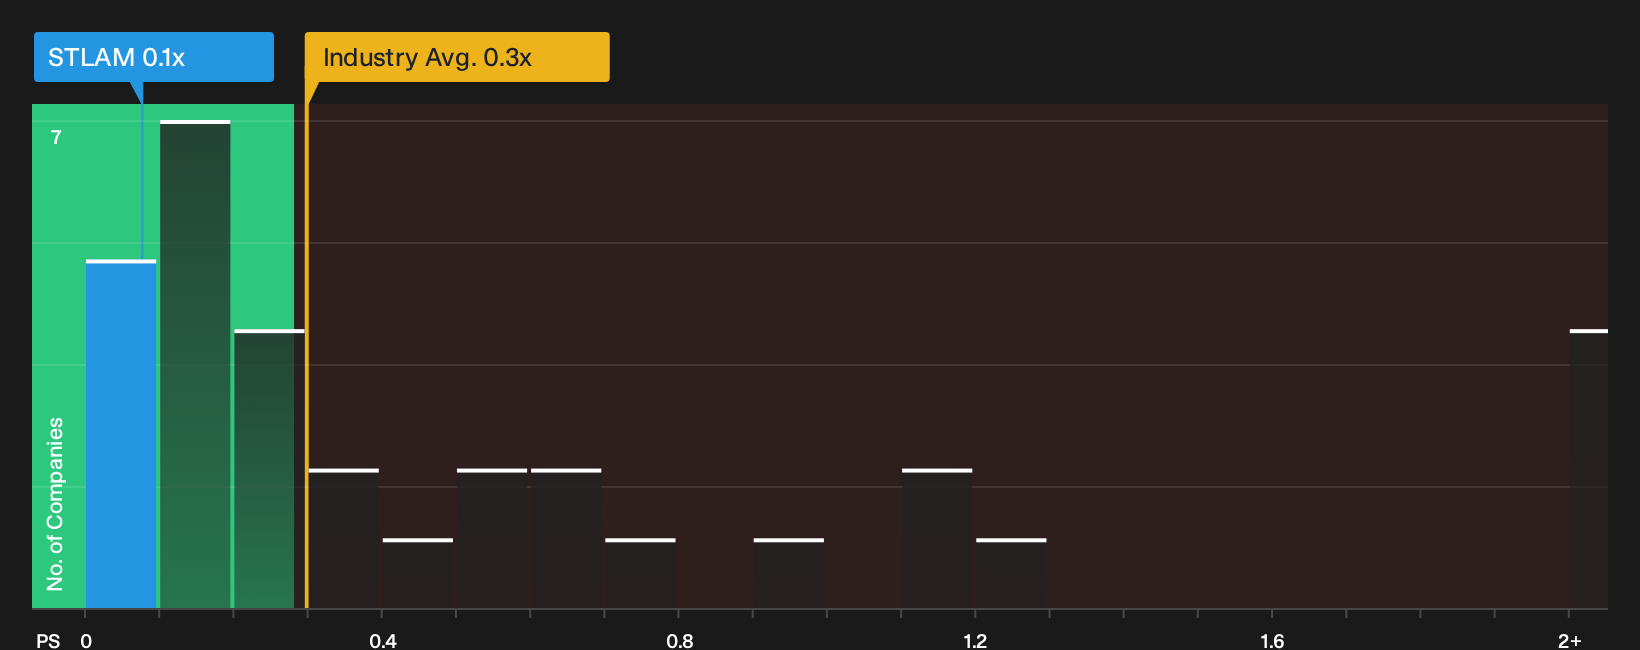
The Stellantis P/S multiple sits at 0.1x, compared with an Auto industry average of 0.6x and a peer group around 3.0x. On the more tailored fair multiple that adjusts for the group’s size, margins and risk profile, the current P/S still screens on the low side, which points to a valuation that prices the revenue base cautiously rather than aggressively. Because the recent Q3 update flagged cost cuts, product launches and a 2027 cash flow target, the current discount on sales comes after a period where the story around profitability has been very much in the headlines. Explore the numbers behind Stellantis's P/S valuation.
The Stellantis Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Stellantis' valuation puzzle leaves off and spell out which combinations of future growth, margins and earnings would need to line up for the share price to sit well above or below today's level on the Community page. Rather than stopping at a single ratio or model output, they unpack the path that figure assumes, so you can watch how Stellantis' actual progress lines up with that story over time.
Community views on Stellantis are split between those who see a repaired balance sheet story and those who focus on cost and tariff headwinds.
Bull case: 55% undervalued
"My Base does not require Stellantis to return to the margins it earned a few years ago…"
Discover why this Narrative puts Stellantis at 55% undervalued.
Bear case: 26% overvalued
"Although Stellantis targets €6 billion of annual cost reductions by 2028 through its Value Creation Program, raw material inflation expected to reach up to roughly 1% of revenue in 2026…"
Explore why this Narrative puts Stellantis at 26% overvalued.
For Stellantis, the share price is only one piece of the story
Market ratios tell you what traders are paying today, while analyst projections sketch out where this business might be a few years from now. This gives you a separate lens to compare with the current valuation. Explore where analysts expect Stellantis to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com