


EN
Will Raised Earnings Guidance Change Ventas Stock Narrative
- Ventas reported third quarter 2026 results with revenue of US$1,831.79 million and net income of US$65.38 million, and raised full year 2026 net income guidance to a range of US$324 million to US$339 million.
- The firmer outlook is tied to extensive senior housing investment activity that management describes as accretive, set against ongoing interest rate and foreign exchange pressures.
- We will now look at how Ventas's raised earnings guidance, tied to senior housing performance, could influence its broader investment narrative.
Scan beyond Ventas and see how other income-focused real estate plays stack up on balance sheet strength and fundamentals with our curated list of solid balance sheet and fundamentals (25 results).
Ventas Investment Narrative Recap
To own Ventas, an investor needs to be comfortable with a senior housing story that leans on demographic demand, an expanded footprint and the operating leverage that can come from keeping occupancy around recent levels. The raised 2026 net income outlook signals management sees that engine still working, although recent quarterly net income and EPS were broadly flat year on year.
The most important near term catalyst remains execution in the senior housing operating portfolio, given its growing weight in overall earnings. Interest expense coverage and local market occupancy are still the key swing factors. The latest results and guidance tweak that balance but do not fundamentally change those near term risks.
The updated full year 2026 net income guidance to US$324 million to US$339 million, or US$0.64 to US$0.67 per share, is the announcement that really matters here. Management tied the uplift mainly to accretive senior housing investment activity, with interest rates and foreign exchange acting as partial offsets.
For you, that guidance revision puts more focus on whether the US$5.2b of senior housing deals closed year to date can keep translating into cash net operating income and funds from operations in line with expectations. It also sharpens the question of how much room Ventas has on funding costs, given interest payments are described as not well covered by earnings.
What The Long Term Ventas Forecast Implies
Ventas' long term story, at least as analysts frame it, leans heavily on a sizeable step up in both revenue and profitability over the next few years. Their models assume the business can compound its top line at 11.6% a year while lifting profit margins from 4.1% today to 7.6% in three years, largely off the back of a bigger, more efficient senior housing portfolio.
On earnings, the current consensus points to US$262.7 million today moving to US$677.2 million by about 2029, which is roughly 2.6x higher. That forecast sits inside a wide range though, with the most optimistic analysts at US$1.1b in earnings and the most cautious nearer to US$542.7 million, underlining how much uncertainty still surrounds the end point of Ventas' expansion plan.
Those profit forecasts sit alongside an expectation that the number of shares on issue climbs by 7.0% per year for the next three years, reflecting continued use of equity to fund senior housing investments. For you as a prospective or current holder, that makes the gap between total earnings growth and per share earnings growth an important detail to watch, since heavy issuance can dilute the benefit of higher aggregate profits.
Ventas' narrative projects US$8.9b revenue and US$677.2 million earnings by 2029. This assumes 11.6% yearly revenue growth and an earnings increase of about US$414.5 million from current earnings of US$262.7 million.
The valuation bridge that ties these assumptions together is demanding. To line up with the analyst consensus price target of US$101.86, the stock would need to be trading on a P/E of 117.4x those 2029 earnings, down from 169.3x today but still far above the current 28.7x P/E cited for the US Health Care REITs industry. That gap is really a confidence measure, because it shows how much faith the market would need to place in Ventas converting its senior housing thesis into durable cash flow.
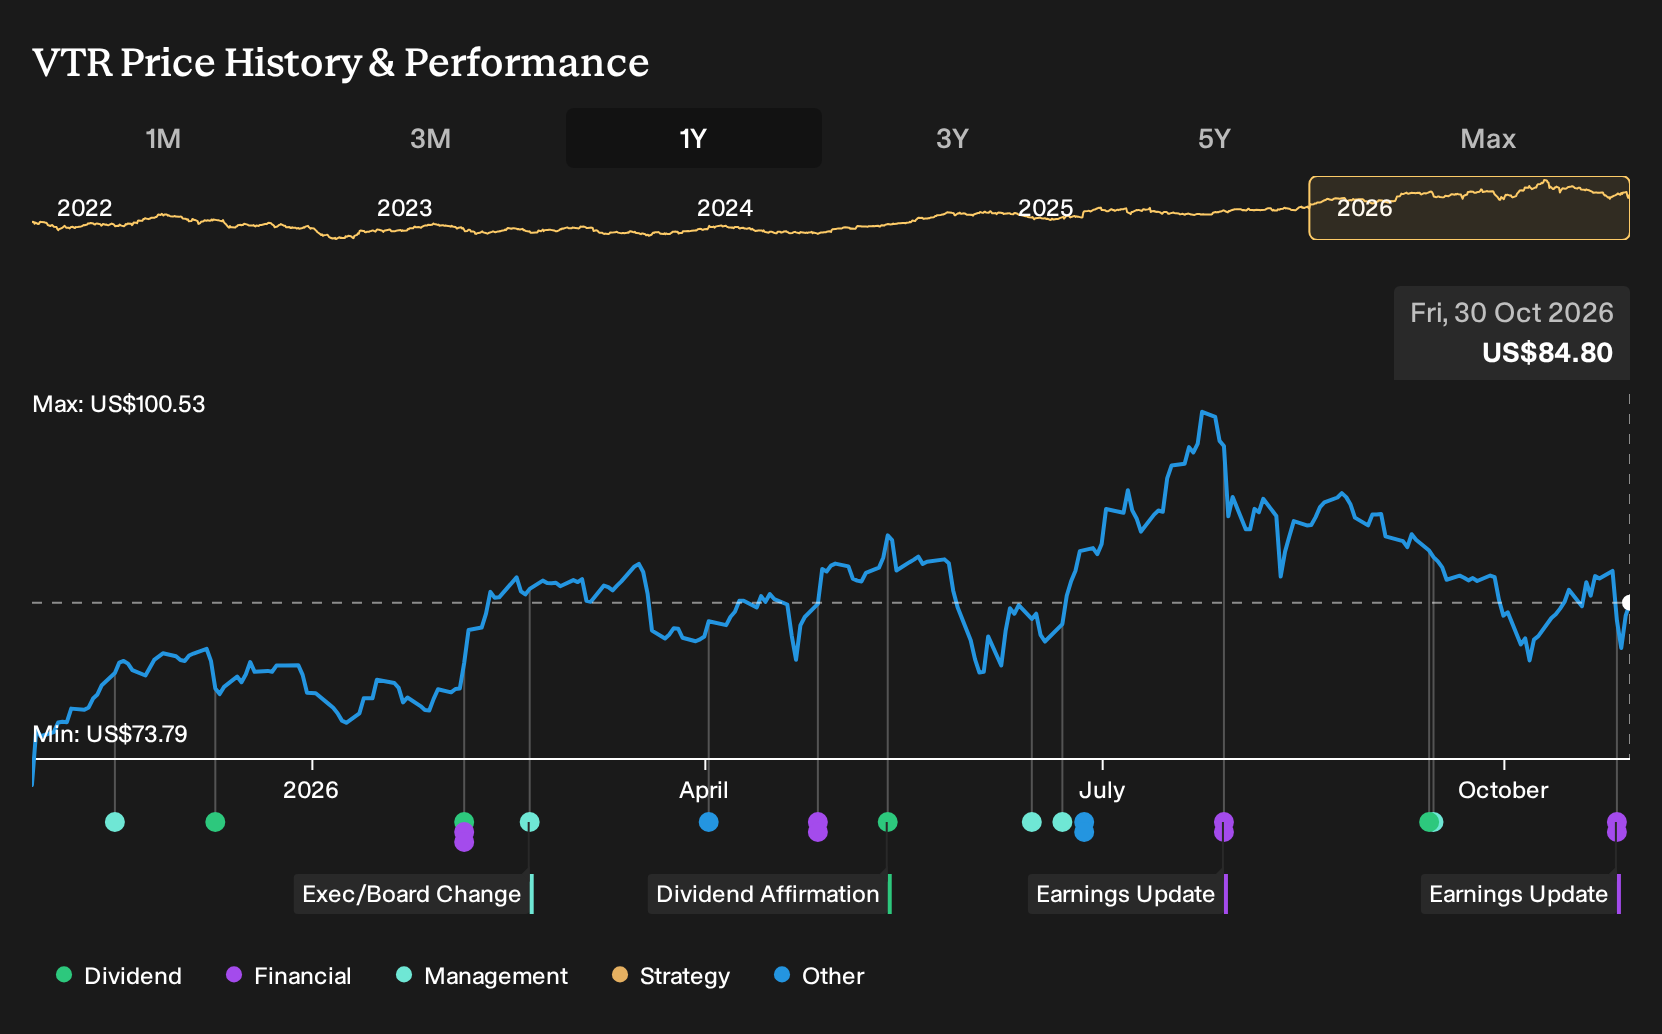
Price targets themselves are spread out. The most bullish estimate sits at US$113.0, while the most cautious is US$90.0, against a recent share price of US$86.69 and a consensus that is 14.9% higher. Rather than taking any of those figures at face value, use them as reference points while you test your own assumptions about senior housing demand, funding costs and Ventas' ability to hold margins closer to the levels analysts are building into their spreadsheets.
Uncover how Ventas' fair value indicates an 18% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster between about US$99.73 and US$114.92, which puts Ventas close to the top of that retail investor range already. Those assessments pre date the raised 2026 guidance and heavy senior housing investment, so treat them as starting points and explore how your own expectations around funding costs, competition and occupancy might differ.
Explore another Ventas fair value estimate, including one that suggests as much as 36% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ventas research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ventas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ventas' overall financial health at a glance.
Looking For More Investment Ideas Beyond Ventas?
Once you have a view on Ventas, it can help to put that thinking in context by scanning other businesses with different income profiles, balance sheet setups and risk levels using the Simply Wall St Screener.
- Focus on value first and see which companies combine quality fundamentals with prices that imply potential mispricing through our 29 high quality undervalued stocks.
- If income is your priority, compare how other high-yield opportunities stack up on payout strength and resilience with the 5 dividend fortresses.
- Prefer to keep risk contained while you search for ideas? Use the 30 resilient stocks with low risk scores to zero in on businesses with more defensive profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com